

Periodic/Sector reports
Consumer: China Consumer: 2026 Mid-Autumn And Golden Week Preview
OVERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- The 13-day holiday stretch, supported by school autumn breaks in some regions, is creating the longest travel period of the year and is driving broad-based tourism demand. Domestic air ticket bookings for the holiday period are up more than 10% yoy, with long-haul routes outperforming.
- Hotel demand remains healthy, with H World reporting improving booking trends. Although Macau’s daily visitor arrivals during the Mid-Autumn holiday are expected to be only in line with, or slightly above, the 8M26 average at the upper end of forecasts, hotel occupancy during the National Day holiday is expected to exceed last year's level, with over half the 36 luxury hotels at Macau casino resorts already sold out for at least five nights.
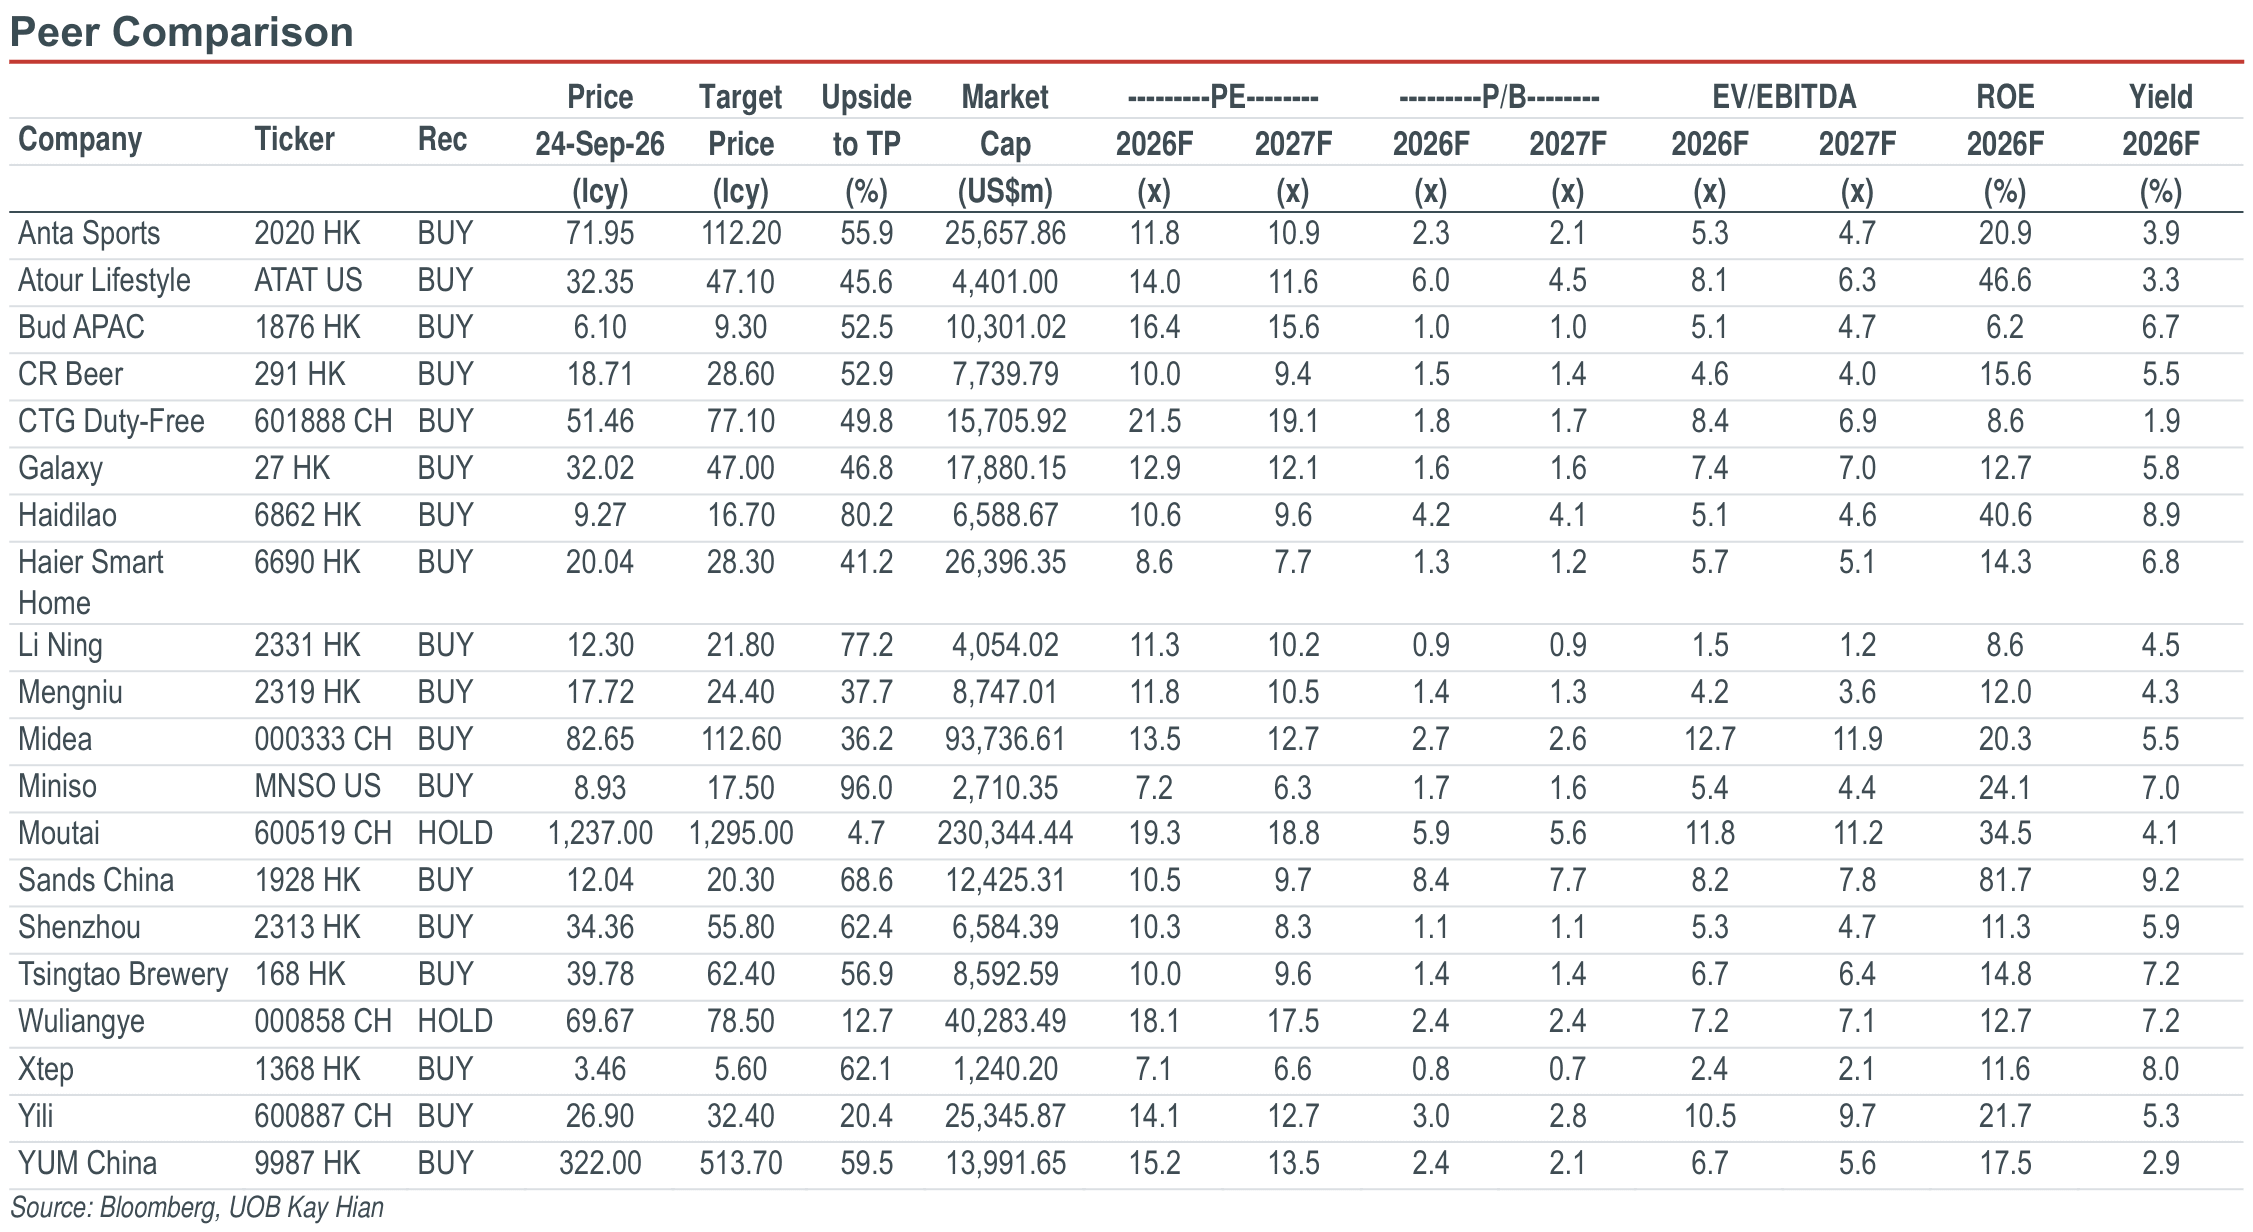
- For baijiu, industry insiders pointed to a weaker-than-usual holiday season. Nevertheless, the premium segment, particularly Moutai, has remained resilient, while mass-market products are benefitting from a shift toward at-home consumption and are seeing relatively stronger demand than the sub-premium segment. Maintain OVERWEIGHT. Our top picks are Anta, Atour, Midea and YUM China in consumer discretionary, and Mengniu in consumer staples.
Analysis
- 13-day holiday stretch supported by school autumn break, the longest of the year. This year, the Mid-Autumn holiday falls on 25-27 September and the National Day holiday on 1-7 October, compared with the combined 1-8 October holiday period last year. Some regions have designated 28-30 September as a school autumn break period, effectively creating a 13-day holiday period, the longest of the year.
- Baijiu seeing weaker-than-usual holiday demand, but premium segment remained resilient. Industry insiders pointed to a weaker-than-usual holiday season. This year, several distilleries have shifted their focus from pushing inventories into channels to closely monitoring sell-through trends. Retail sell-through performance diverged across price segments ahead of the holiday. The premium segment, particularly Moutai, remained resilient. Feitian Moutai’s retail price reportedly stayed firm at above Rmb1,800/bottle, compared with the official retail price of Rmb1,639/bottle on i-Moutai and Rmb1,766/bottle in offline stores. The wholesale market also showed signs of stabilisation. The latest wholesale prices for original case and unpacked Feitian Moutai stood at Rmb1,745/bottle and Rmb1,740/bottle, respectively, both largely flat mtd. Retail prices of Wuliangye 8th-generation and Guojiao 1573 stood at around Rmb820/bottle and Rmb900/bottle, respectively. In contrast, the sub-premium segment (Rmb300-800) continued to face pressure, while mass-market products (Rmb100-300) proved more resilient. This was mainly due to consumption demand shifting from banquet and business occasions to at-home consumption, driving consumers towards products in the Rmb100-300 price range.
- Hotel booking trend remained solid. As of 18 September, H World’s Mid-Autumn holiday booking rate was 10ppt higher than the level recorded at end-August (28-30 August), while the National Day holiday booking rate continued to climb. Among tier 1 cities, Beijing ranked first in bookings, with strong demand also seen in tier 2 and 3 coastal cities. UrCove, a hotel brand jointly established by Hyatt Hotels and BTG Home Inn, reported yoy increases in both national average room rates and bookings per hotel. Inbound travel also provided incremental support, albeit modestly. According to Umetrip, inbound air ticket bookings for 25 September-7 October exceeded 1.11m, up about 6% yoy, with Shanghai, Beijing and Guangzhou ranking as the top destinations.
Highlights
- The 13-day holiday stretch, supported by school autumn breaks in some regions, is creating the longest travel period of the year and is driving broad-based tourism demand. Domestic air ticket bookings for the holiday period are up more than 10% yoy, with long-haul routes outperforming.
- Hotel demand remains healthy, with H World reporting improving booking trends. Although Macau’s daily visitor arrivals during the Mid-Autumn holiday are expected to be only in line with, or slightly above, the 8M26 average at the upper end of forecasts, hotel occupancy during the National Day holiday is expected to exceed last year's level, with over half the 36 luxury hotels at Macau casino resorts already sold out for at least five nights.
- For baijiu, industry insiders pointed to a weaker-than-usual holiday season. Nevertheless, the premium segment, particularly Moutai, has remained resilient, while mass-market products are benefitting from a shift toward at-home consumption and are seeing relatively stronger demand than the sub-premium segment. Maintain OVERWEIGHT. Our top picks are Anta, Atour, Midea and YUM China in consumer discretionary, and Mengniu in consumer staples.
Analysis
- 13-day holiday stretch supported by school autumn break, the longest of the year. This year, the Mid-Autumn holiday falls on 25-27 September and the National Day holiday on 1-7 October, compared with the combined 1-8 October holiday period last year. Some regions have designated 28-30 September as a school autumn break period, effectively creating a 13-day holiday period, the longest of the year.
- Baijiu seeing weaker-than-usual holiday demand, but premium segment remained resilient. Industry insiders pointed to a weaker-than-usual holiday season. This year, several distilleries have shifted their focus from pushing inventories into channels to closely monitoring sell-through trends. Retail sell-through performance diverged across price segments ahead of the holiday. The premium segment, particularly Moutai, remained resilient. Feitian Moutai’s retail price reportedly stayed firm at above Rmb1,800/bottle, compared with the official retail price of Rmb1,639/bottle on i-Moutai and Rmb1,766/bottle in offline stores. The wholesale market also showed signs of stabilisation. The latest wholesale prices for original case and unpacked Feitian Moutai stood at Rmb1,745/bottle and Rmb1,740/bottle, respectively, both largely flat mtd. Retail prices of Wuliangye 8th-generation and Guojiao 1573 stood at around Rmb820/bottle and Rmb900/bottle, respectively. In contrast, the sub-premium segment (Rmb300-800) continued to face pressure, while mass-market products (Rmb100-300) proved more resilient. This was mainly due to consumption demand shifting from banquet and business occasions to at-home consumption, driving consumers towards products in the Rmb100-300 price range.
- Hotel booking trend remained solid. As of 18 September, H World’s Mid-Autumn holiday booking rate was 10ppt higher than the level recorded at end-August (28-30 August), while the National Day holiday booking rate continued to climb. Among tier 1 cities, Beijing ranked first in bookings, with strong demand also seen in tier 2 and 3 coastal cities. UrCove, a hotel brand jointly established by Hyatt Hotels and BTG Home Inn, reported yoy increases in both national average room rates and bookings per hotel. Inbound travel also provided incremental support, albeit modestly. According to Umetrip, inbound air ticket bookings for 25 September-7 October exceeded 1.11m, up about 6% yoy, with Shanghai, Beijing and Guangzhou ranking as the top destinations.
OVERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

10 Sept 2026
Consumer: China Consumer: 2Q/1H26 Results Wrap-up

8 Sept 2026
China Property: Shanghai Shifts Housing Supply From New Build To Renewal; National Land Supply Keeps Shrinking

4 Sept 2026
Internet - 2Q26 Results Recap: AI Cloud Accelerates; E-Commerce Still Soft; Gaming Resilient
Our latest research

25 Sept 2026
Automobile: China Auto Sector Weekly (19-25 Sep 26)

24 Sept 2026
China Property: Faster Mortgage Contraction Raises The Odds Of A National Rate Subsidy; Maintain UNDERWEIGHT

23 Sept 2026