
Periodic/Sector reports
Automobile: China Auto Sector Weekly
Highlights
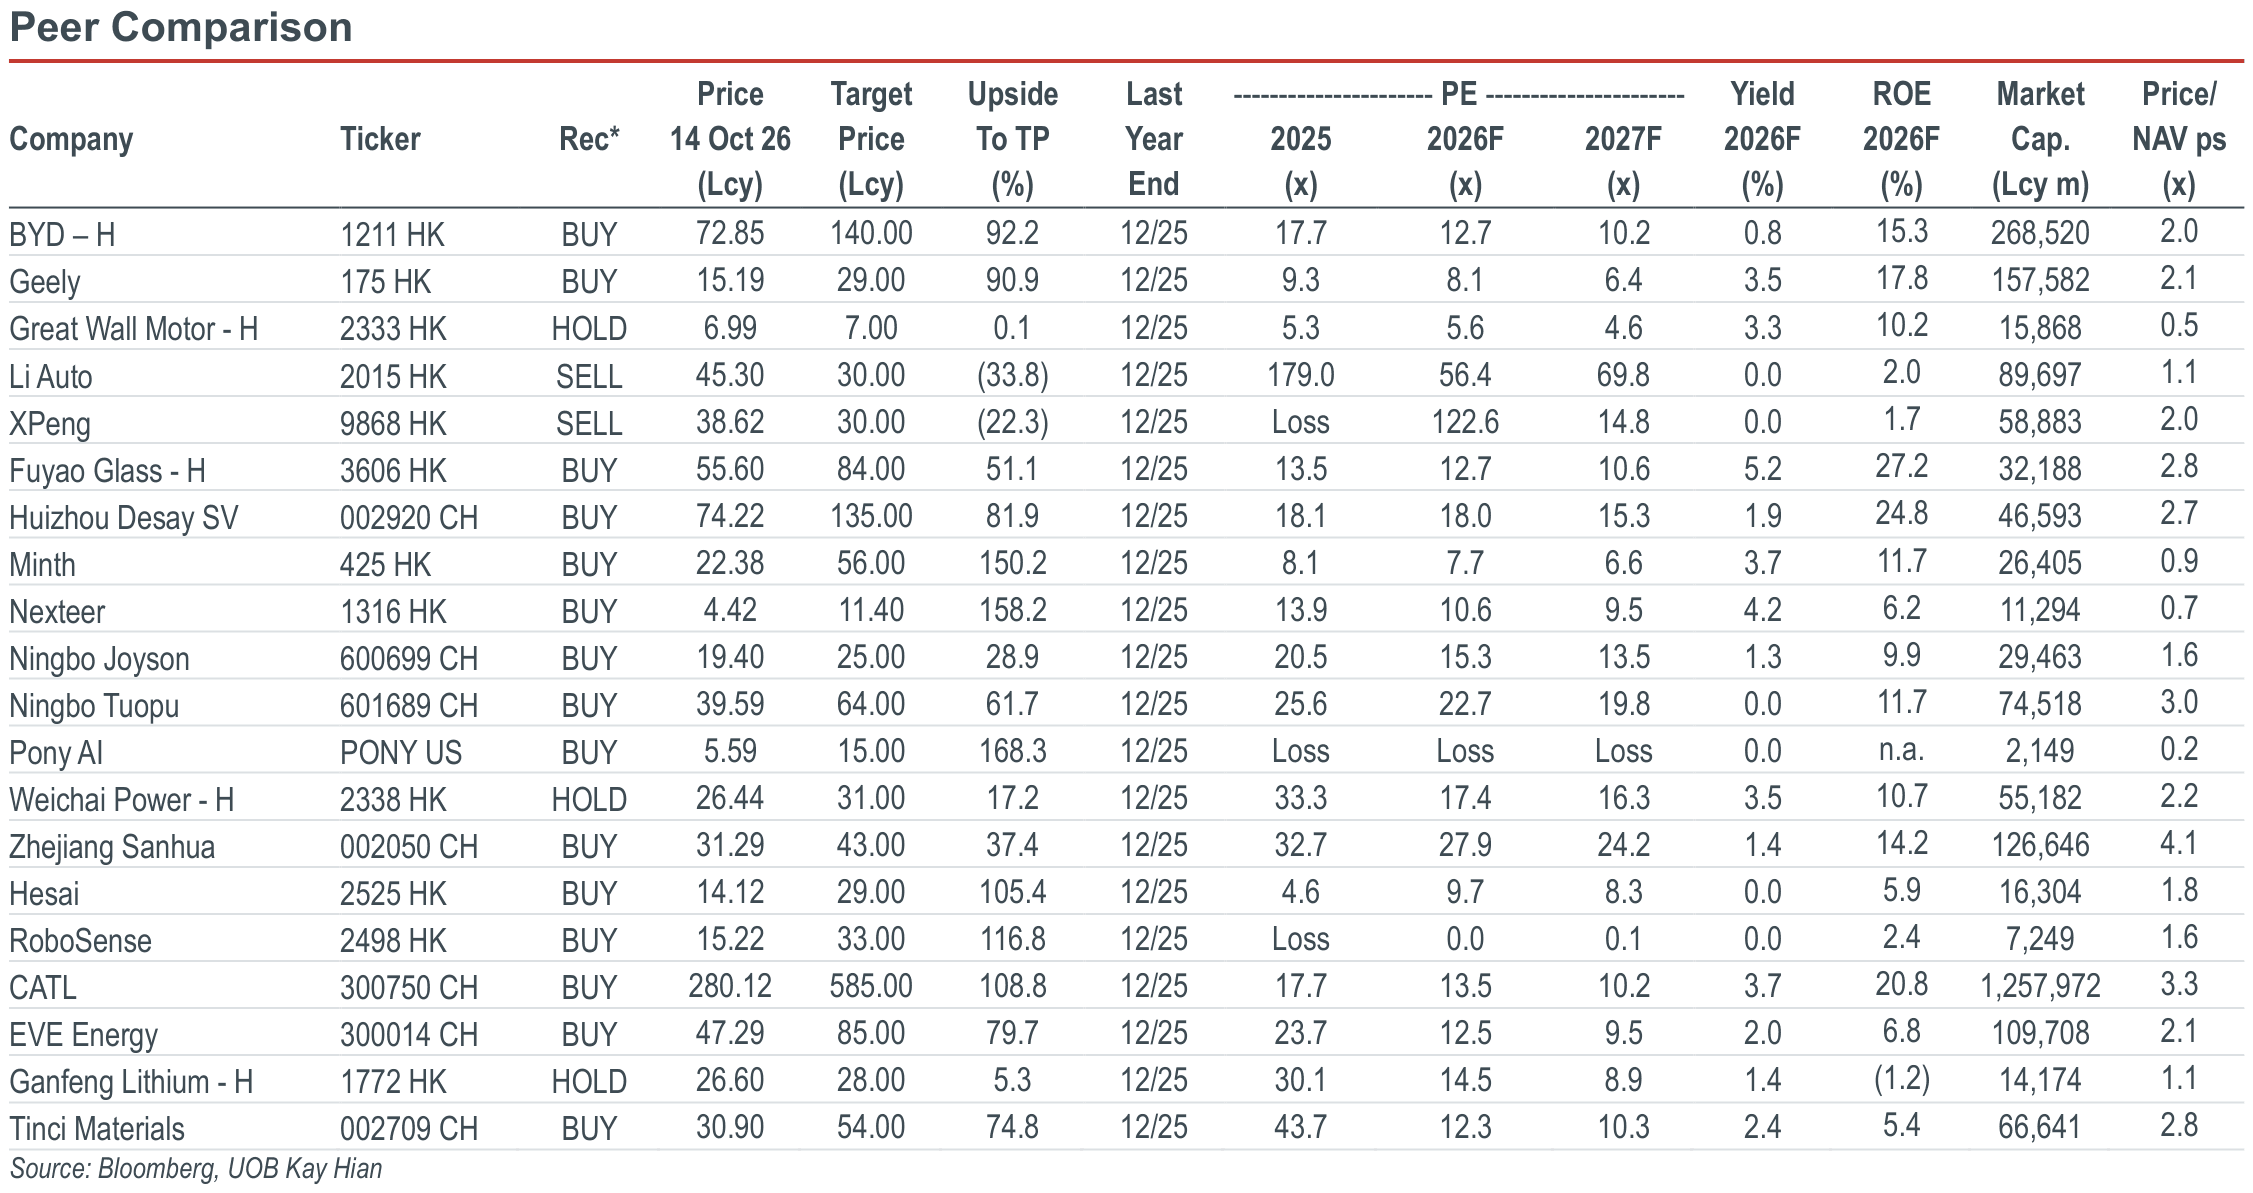
- China and the EU have agreed on a hybrid export quota. China will cut the export VAT rebate on EVs to 9% from 13% from 1 Apr 27. BYD and Geely can navigate these measures by producing overseas.
- Lithium carbonate prices are weaker than expected; downgrade Ganfeng Lithium from BUY to HOLD.
- RoboSense’s 3Q26 LiDAR sales volume rose 221% yoy and 53% qoq, in line. However, its 3Q26 bottom line was dragged by the product recall.
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely, and CATL. Top SELLs: Li Auto, and XPeng.
Analysis
- September PV sales down 9.3% yoy and up 8.2% mom, with domestic sales decline offsetting export growth. China Passenger Car Association (CPCA) reported China’s Sep 26 passenger vehicle (PV) wholesale sales at 2.566m units (-9.3% yoy/+8.2% mom), domestic retail sales at 1.631m units (-28.1% yoy/+5% mom), and export at 923,000 units (+73.2% yoy/+3.2% mom), in line with our estimates. China’s PV export growth ytd was driven by EVs. Among the 923,000 units of PV exports, 559,000 units (+163.7% yoy/+7.7% mom) or 60.6% were EVs.
- China-EU hybrid deal: A 350,000-unit quota pushes Chinese OEMs to build cars in Europe. After talks in Beijing on 8-9 October, China accepted a quota on hybrid exports to the EU. Bloomberg reported that the cap would be 350,000 units a year from as early as 1 Dec 26, rising 6% a year from the second year over four years; the European Commission has not published the figure. China’s Ministry of Commerce said the quota is set based on the 302,000 China-made hybrids the EU imported in 2025 and an annual growth rate. The deal is yet to be finalised, and EU leaders will discuss further at the 15-16 October summit.
Highlights
- China and the EU have agreed on a hybrid export quota. China will cut the export VAT rebate on EVs to 9% from 13% from 1 Apr 27. BYD and Geely can navigate these measures by producing overseas.
- Lithium carbonate prices are weaker than expected; downgrade Ganfeng Lithium from BUY to HOLD.
- RoboSense’s 3Q26 LiDAR sales volume rose 221% yoy and 53% qoq, in line. However, its 3Q26 bottom line was dragged by the product recall.
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely, and CATL. Top SELLs: Li Auto, and XPeng.
Analysis
- September PV sales down 9.3% yoy and up 8.2% mom, with domestic sales decline offsetting export growth. China Passenger Car Association (CPCA) reported China’s Sep 26 passenger vehicle (PV) wholesale sales at 2.566m units (-9.3% yoy/+8.2% mom), domestic retail sales at 1.631m units (-28.1% yoy/+5% mom), and export at 923,000 units (+73.2% yoy/+3.2% mom), in line with our estimates. China’s PV export growth ytd was driven by EVs. Among the 923,000 units of PV exports, 559,000 units (+163.7% yoy/+7.7% mom) or 60.6% were EVs.
- China-EU hybrid deal: A 350,000-unit quota pushes Chinese OEMs to build cars in Europe. After talks in Beijing on 8-9 October, China accepted a quota on hybrid exports to the EU. Bloomberg reported that the cap would be 350,000 units a year from as early as 1 Dec 26, rising 6% a year from the second year over four years; the European Commission has not published the figure. China’s Ministry of Commerce said the quota is set based on the 302,000 China-made hybrids the EU imported in 2025 and an annual growth rate. The deal is yet to be finalised, and EU leaders will discuss further at the 15-16 October summit.
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

25 Sept 2026
Automobile: China Auto Sector Weekly (19-25 Sep 26)

9 Oct 2026
Automobile: China Auto Sector Weekly (26 Sep-8 Oct 26)

11 Sept 2026
Automobile: Weekly: 60-Day Payment Policy Reinforced; September’s New Model Launch Calendar Busier Than That Of Chengdu Auto Show
Our latest research

13 Oct 2026
China Property: Second-hand Sales Outperform New-Home Sales In Sep 26; Tier 1 Cities Property Transactions Rebound In Oct 26
9 Oct 2026
Automobile: China Auto Sector Weekly (26 Sep-8 Oct 26)

9 Oct 2026