

Periodic/Sector reports
Automobile: China Auto Sector Weekly (20 Nov 26)
Highlights
- NEV retail sales fell 13% yoy during 1-15 November, while ICE car retail sales almost halved.
- Memory chip prices could add Rmb4,000-8,000 to an ADAS-equipped BEV’s cost in 2027.
- MIIT will check supplier payment terms at 17 carmakers annually.
- We estimate Li Auto’s and Robosense’s 3Q26 net loss at Rmb1.7b (+172% yoy/flat qoq) and Rmb225m (+248% yoy/+186% qoq) respectively.
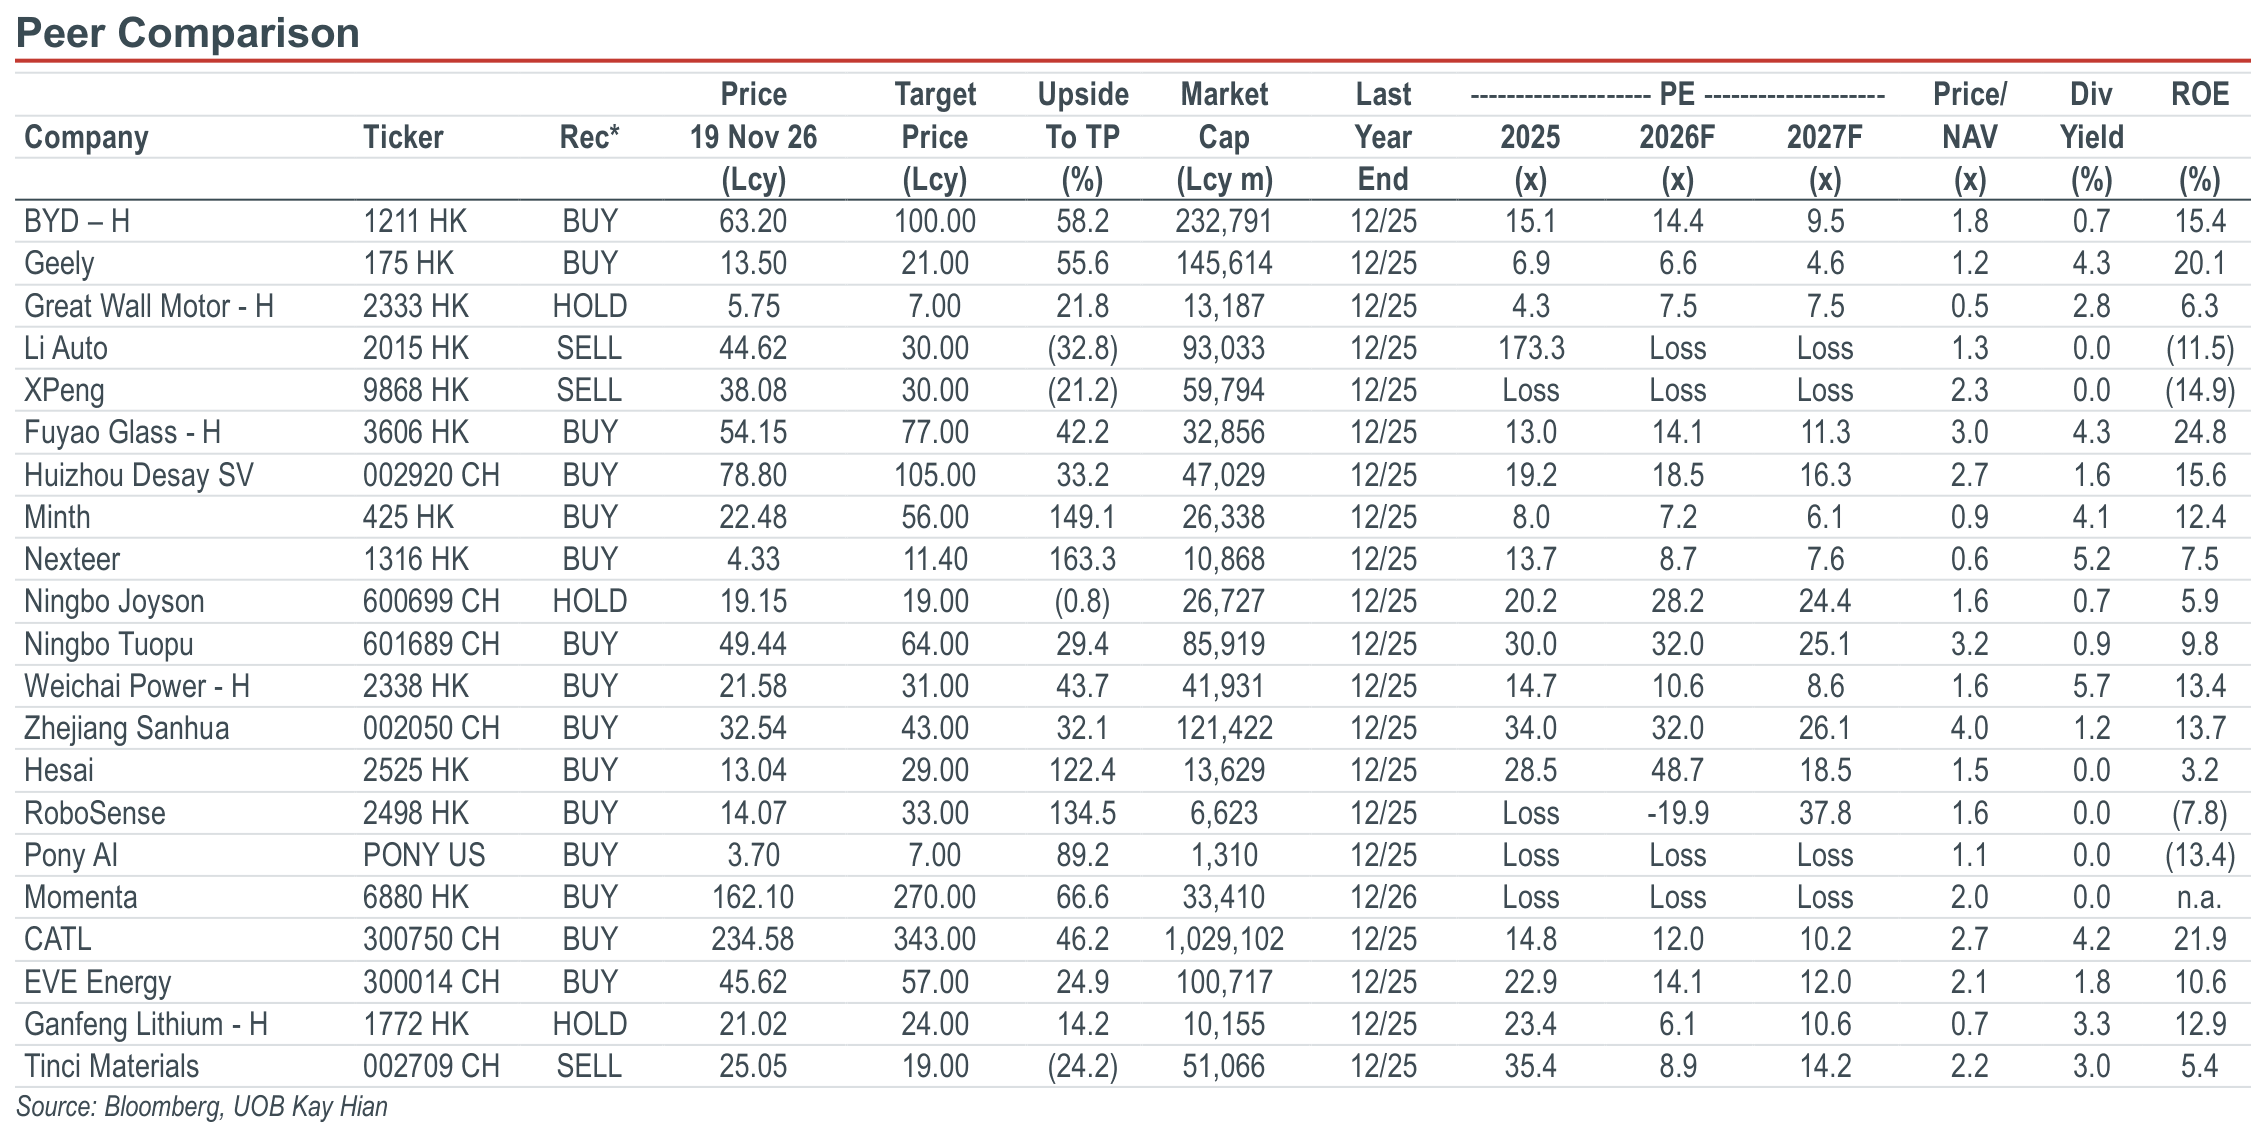
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely. Top SELLs: Li Auto, XPeng.
Analysis
- November sales: NEV retail sales continued to fall in 1-15 November, while ICE car retail sales almost halved. According to the China Passenger Car Association (CPCA), passenger vehicle retail sales fell 25% yoy and 6% mom to 611,000 units, and NEV retail sales fell 13% yoy but rose 7% mom to 447,000 units. NEV penetration of retail sales rose to 73.2% from 67.5% for the whole of October.
- Retail sales of internal combustion engine (ICE) cars fell about 46% yoy. By our calculation, this is about 137,000 units, two-thirds of the fall in total retail sales. The CPCA attributed the ICE decline to high fuel prices.
- NEV wholesale rose 3% yoy while retail fell 13%. Exports explain part of the gap, but the CPCA stated that carmakers are also pushing stock onto dealers to meet year-end targets. The extra dealer stock raises the risk of December and January price cuts for domestically focused Li Auto (2015 HK/SELL/Target: HK$30.00), while BYD (1211 HK/BUY/Target: HK$100.00) and Geely (175 HK/BUY/Target: HK$21.00) are less exposed, as most of their sales growth will come from exports.
- Retail sales of internal combustion engine (ICE) cars fell about 46% yoy. By our calculation, this is about 137,000 units, two-thirds of the fall in total retail sales. The CPCA attributed the ICE decline to high fuel prices.
Highlights
- NEV retail sales fell 13% yoy during 1-15 November, while ICE car retail sales almost halved.
- Memory chip prices could add Rmb4,000-8,000 to an ADAS-equipped BEV’s cost in 2027.
- MIIT will check supplier payment terms at 17 carmakers annually.
- We estimate Li Auto’s and Robosense’s 3Q26 net loss at Rmb1.7b (+172% yoy/flat qoq) and Rmb225m (+248% yoy/+186% qoq) respectively.
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely. Top SELLs: Li Auto, XPeng.
Analysis
- November sales: NEV retail sales continued to fall in 1-15 November, while ICE car retail sales almost halved. According to the China Passenger Car Association (CPCA), passenger vehicle retail sales fell 25% yoy and 6% mom to 611,000 units, and NEV retail sales fell 13% yoy but rose 7% mom to 447,000 units. NEV penetration of retail sales rose to 73.2% from 67.5% for the whole of October.
- Retail sales of internal combustion engine (ICE) cars fell about 46% yoy. By our calculation, this is about 137,000 units, two-thirds of the fall in total retail sales. The CPCA attributed the ICE decline to high fuel prices.
- NEV wholesale rose 3% yoy while retail fell 13%. Exports explain part of the gap, but the CPCA stated that carmakers are also pushing stock onto dealers to meet year-end targets. The extra dealer stock raises the risk of December and January price cuts for domestically focused Li Auto (2015 HK/SELL/Target: HK$30.00), while BYD (1211 HK/BUY/Target: HK$100.00) and Geely (175 HK/BUY/Target: HK$21.00) are less exposed, as most of their sales growth will come from exports.
- Retail sales of internal combustion engine (ICE) cars fell about 46% yoy. By our calculation, this is about 137,000 units, two-thirds of the fall in total retail sales. The CPCA attributed the ICE decline to high fuel prices.
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


