

Periodic/Sector reports
China Property: Faster Mortgage Contraction Raises The Odds Of A National Rate Subsidy; Maintain UNDERWEIGHT
UNDERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- The market is again abuzz with rumours of a nationwide mortgage-interest subsidy. With mortgage balance contraction having accelerated sharply in 2026, we see a marginally higher possibility of mortgage rate subsidy. A 100bp one-year subsidy scheme covering new first-home loans would cost about Rmb23b a year, which is 0.1% of annual fiscal income.
- We remain cautious about recent rumours that the government has provided window guidance for banks to extend loans to Vanke.
- A potential mortgage-interest subsidy is worth watching out for. However, share prices could correct if the subsidy comes later or is smaller in scale than expected. Maintain UNDERWEIGHT. Our top picks are COLI and CR Mixc.
Analysis
- Market again abuzz with rumours of a nationwide mortgage-interest subsidy. There has been market speculation during the past week that the government may introduce a nationwide mortgage-interest subsidy before end-Sep 26. Rumours suggest that combined central and local subsidies could cut effective mortgage rates for first-time buyers of new homes by 40-100bp. Including this latest round, similar rumours have surfaced at least three times since Nov 25.
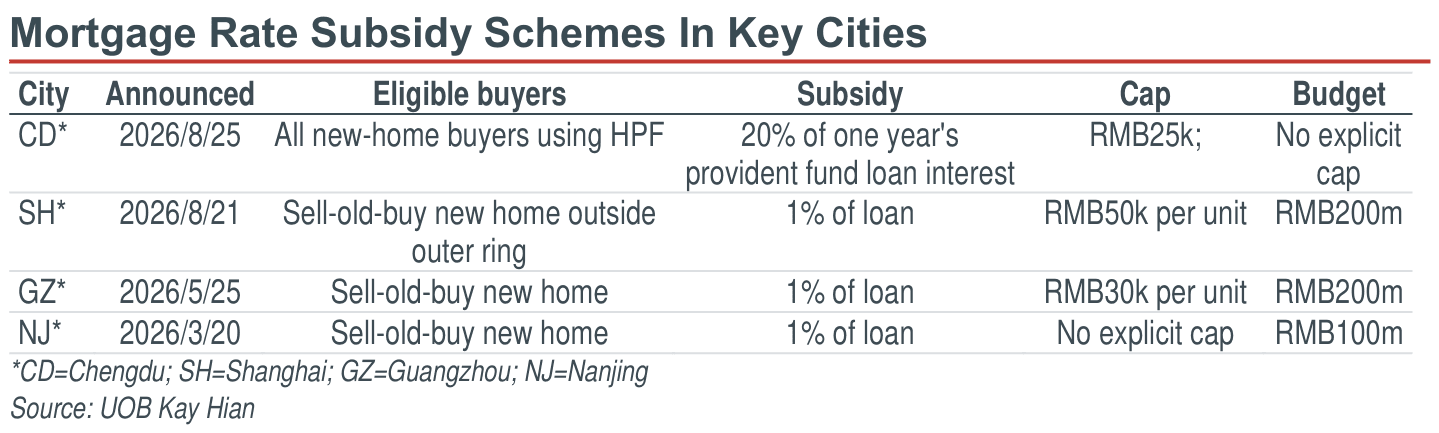
- Mortgage rate subsidies have been adopted by a growing number of cities to stabilise their housing markets, but tight local finances limit the size of packages. So far, around 20 cities have introduced their own mortgage rate subsidy schemes. Many of the schemes mainly target homebuyers who sell their existing homes and use mortgage financing to purchase new homes. The interest subsidy is generally capped at around Rmb25,000–50,000 per buyer. However, the rollout of these policies has so far been relatively limited across cities, with total subsidy budgets ranging from only Rmb100m to Rmb200m per city. This may be mainly because the subsidies are funded and implemented by local governments, and are thus constrained by the tight financing of local governments.
Highlights
- The market is again abuzz with rumours of a nationwide mortgage-interest subsidy. With mortgage balance contraction having accelerated sharply in 2026, we see a marginally higher possibility of mortgage rate subsidy. A 100bp one-year subsidy scheme covering new first-home loans would cost about Rmb23b a year, which is 0.1% of annual fiscal income.
- We remain cautious about recent rumours that the government has provided window guidance for banks to extend loans to Vanke.
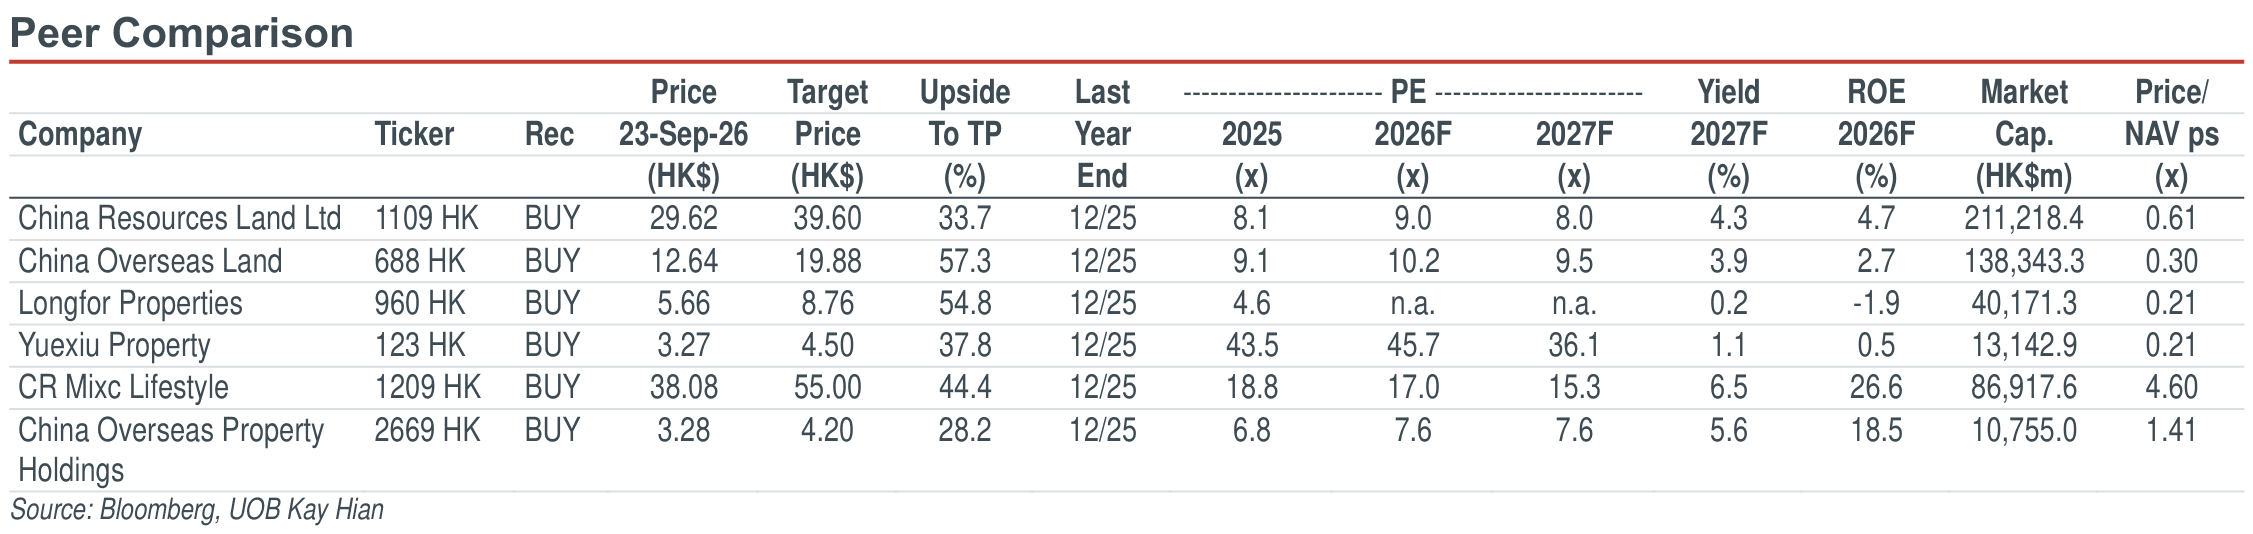
- A potential mortgage-interest subsidy is worth watching out for. However, share prices could correct if the subsidy comes later or is smaller in scale than expected. Maintain UNDERWEIGHT. Our top picks are COLI and CR Mixc.
Analysis
- Market again abuzz with rumours of a nationwide mortgage-interest subsidy. There has been market speculation during the past week that the government may introduce a nationwide mortgage-interest subsidy before end-Sep 26. Rumours suggest that combined central and local subsidies could cut effective mortgage rates for first-time buyers of new homes by 40-100bp. Including this latest round, similar rumours have surfaced at least three times since Nov 25.
- Mortgage rate subsidies have been adopted by a growing number of cities to stabilise their housing markets, but tight local finances limit the size of packages. So far, around 20 cities have introduced their own mortgage rate subsidy schemes. Many of the schemes mainly target homebuyers who sell their existing homes and use mortgage financing to purchase new homes. The interest subsidy is generally capped at around Rmb25,000–50,000 per buyer. However, the rollout of these policies has so far been relatively limited across cities, with total subsidy budgets ranging from only Rmb100m to Rmb200m per city. This may be mainly because the subsidies are funded and implemented by local governments, and are thus constrained by the tight financing of local governments.
UNDERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Sept 2026
China Property: NBS Publishes Inaugural Second-Hand Transactions Data; Household Mortgage Borrowing Is Still Shrinking

8 Sept 2026
China Property: Shanghai Shifts Housing Supply From New Build To Renewal; National Land Supply Keeps Shrinking

15 Sept 2026
China Property: New Home Sales Accelerate In Tier 1 Cities In Early-Sep 26 But Weaken In Lower-tier Cities
Our latest research
23 Sept 2026
China Property: NBS Publishes Inaugural Second-Hand Transactions Data; Household Mortgage Borrowing Is Still Shrinking

22 Sept 2026
IT Hardware: Takeaways From 2026 Huawei Connect

21 Sept 2026