
Country Daily
China Economics PMI / Macau Gaming / China Tourism Group Duty Free / Estun Automation / Inner Mongolia Yili / Kweichow Moutai / Shenzhen Mindray / TAL Educational / Tinci Materials / Weichai Power / Xiaomi
Analyst
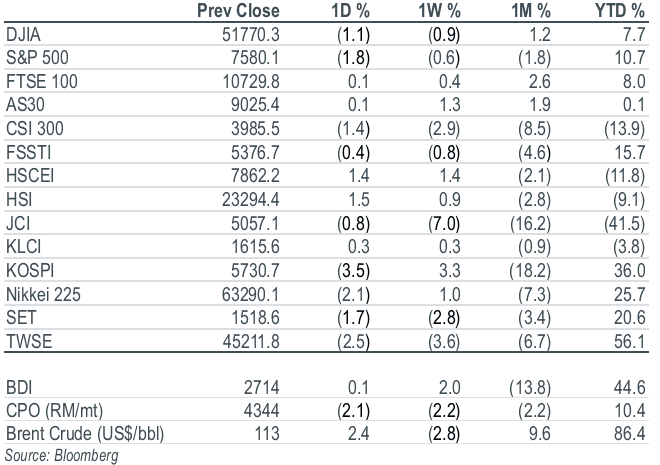
Key Indices
Top Stories
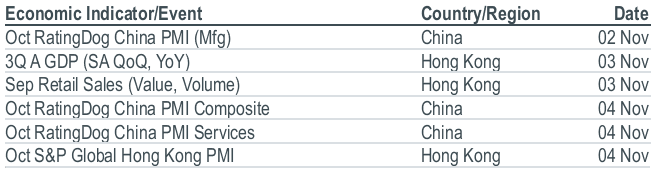
Economics | PMI
October’s PMI was negative, with manufacturing PMI contracting to 49.3 (-0.8ppt mom) and non-manufacturing PMI at 49.7 (-0.5ppt mom), both below Bloomberg’s consensus. The decline in manufacturing PMI was similar to Oct 25, with the NBS partly attributing it to demand brought forward ahead of the National Day holiday, while the construction industry index fell back into contraction after September’s rebound. The narrowing price gap eases margin pressure, but further targeted support is needed to sustain activity in 4Q26.
Sector Update | Macau Gaming
Macau’s October 26 GGR reached MOP21.7b, down 10% yoy, but up 20% mom. October’s GGR figure was in line with market consensus, and recovered to 82% of 2019’s level. For 10M26, GGR rose by 2% yoy to MOP208.8b, recovering to 85% of 2019’s level. We lower our full-year GGR estimate by 2% from MOP258b to MOP 252b, implying 2% yoy growth and an 86% recovery rate vs 2019’s level. Maintain OVERWEIGHT; Galaxy remains our top pick.
Company Results | China Tourism Group Duty Free (601888 CH/BUY/Rmb50.30/Target: Rmb68.70)
CTGDF’s 3Q26 results missed. Revenue declined 5% yoy, but net profit rose 25% yoy, driven by gross margin expansion, lower minority interests and non-operating items. Hainan’s offline duty-free sales growth slowed to 2% yoy (vs +4% in 2Q26), with per capita spending flat yoy (+1% yoy in 2Q26). CTGDF’s international business continued to expand, with revenue growing 71% yoy in 9M26, following the acquisition of DFS’ Greater China retail business. Maintain BUY; cut target price by 11% to Rmb68.70.
Company Results | Estun Automation Technology (002747 CH/BUY/Rmb29.24/Target: Rmb35.70)
Estun’s 3Q26 results missed on revenue due to seasonality and focus shifting away from low-value orders, but in return, profitability improved with margins expanding 3.8ppt yoy. Full-year revenue and profit guidance had been revised down, but management remained upbeat on 2027’s growth, citing robust overseas orders growth alongside solid embodied robot development. Upgrade to BUY and raise target price to Rmb35.70.
Company Results | Inner Mongolia Yili Industrial Group (600887 CH/BUY/Rmb30.15/Target: Rmb33.70)
Yili’s 3Q26 revenue missed expectations. However, core operating profit increased 7% yoy, with margin expanding 0.5ppt yoy. Net profit declined 6% due to higher impairment losses, lower fair value gains and a higher effective tax rate. With an improving distributor inventory and a low base, management expects the liquid milk business’s growth to accelerate in 4Q26. Management reiterated its full-year target of mid-single-digit revenue growth, with core operating margin improving yoy. Maintain BUY. Raise target price by 4% to Rmb33.70.
Company Results | Kweichow Moutai (600519 CH/HOLD/Rmb1,392.05/Target: Rmb1,458.00)
Moutai’s 3Q26 revenue rose 3% yoy and net profit rose 4% yoy, both in line with consensus estimates. By channel, direct sales rose 40% yoy, while wholesale channel sales declined 22% yoy. i-Moutai sales came in at Rmb18.3b, contributing 84% of direct sales. As of end-3Q26, contract liabilities fell 73% yoy and 34% qoq to Rmb2.1b, while cash inflow from sales of goods and services rose 3% yoy to Rmb45.1b. Maintain HOLD; raise target price by 13% to Rmb1,458.00.
Company Results | Shenzhen Mindray Bio-Medical Electronics (300760 CH/BUY/Rmb181.75/Target: Rmb210.00)
9M26 revenue rose 4.9% yoy to Rmb27.1b and adjusted net earnings declined 2.8% yoy to Rmb7.3b, in line with our full-year growth estimates. 3Q26 revenue growth slowed to 2.9% and earnings declined 1.6% yoy on forex losses. On a constant currency basis, 3Q26 revenue grew 6.0% yoy. Overseas revenue rose 11.0% yoy in 9M26 to account for 53% of sales. Mindray expects the overseas and emerging businesses to continue driving growth in 2027. Maintain BUY. Raise target price to Rmb210.00.
Company Results | TAL Educational Group (TAL US/BUY/US$10.14/Target: US$15.00)
TAL's 2QFY27 revenue grew 15% yoy to US$995m, 7% and 8% below our and consensus estimates. Non-GAAP operating profit more than doubled to US$248m, with operating margin expanding 12.4ppt yoy to 25% as S&M expenses fell 15% yoy. Non-GAAP net profit fell short of expectations and came in at losses of US$36m vs the street’s estimate of US$200m due to fair-value losses on investments and tax charges. Maintain BUY with a lower target price of US$15.00.
Company Results | Tinci Materials (002709 CH/SELL/Rmb26.12/Target: Rmb19.00)
Tinci’s 3Q26 adjusted net profit of Rmb1,033m (+646% yoy/-17% qoq) missed on margins as LiPF6 prices fell. We expect LiPF6 weakness to drag earnings despite volume growth, and cut 2026-28 net profit forecasts by 22%/62%/62% to Rmb5.71b/Rmb3.60b/Rmb4.31b on lower ASP and gross margin. Downgrade to SELL; target price cut from Rmb54.00 to Rmb19.00.
Company Results | Weichai Power (2338 HK/BUY/HK$23.52/Target: HK$31.00)
Weichai’s 3Q26 adjusted net profit rose 13.9% yoy to Rmb3,220m, in line, while GAAP net profit fell 8.6% on Ballard fair value losses, credit provisions and forex. Power and energy will be the primary growth drivers, contributing about 20% of profit. Data centre diesel genset is guided to come in above 4,000 units in 2026 and above 6,000 in 2027. Upgrade to BUY. Target price: HK$31.00.
Company Update | Xiaomi Corp (1810 HK/HOLD/HK$26.48/Target: HK$25.90)
Xiaomi’s 3Q26 earnings are expected to be underwhelming in light of weakened consumer demand across smartphones, automobiles and IoT. That said, we expect a pleasant surprise in its smartphone business which was primarily driven by a better product mix. Maintain HOLD with a lower target price of HK$25.90.
Top Stories
Economics | PMI
October’s PMI was negative, with manufacturing PMI contracting to 49.3 (-0.8ppt mom) and non-manufacturing PMI at 49.7 (-0.5ppt mom), both below Bloomberg’s consensus. The decline in manufacturing PMI was similar to Oct 25, with the NBS partly attributing it to demand brought forward ahead of the National Day holiday, while the construction industry index fell back into contraction after September’s rebound. The narrowing price gap eases margin pressure, but further targeted support is needed to sustain activity in 4Q26.
Sector Update | Macau Gaming
Macau’s October 26 GGR reached MOP21.7b, down 10% yoy, but up 20% mom. October’s GGR figure was in line with market consensus, and recovered to 82% of 2019’s level. For 10M26, GGR rose by 2% yoy to MOP208.8b, recovering to 85% of 2019’s level. We lower our full-year GGR estimate by 2% from MOP258b to MOP 252b, implying 2% yoy growth and an 86% recovery rate vs 2019’s level. Maintain OVERWEIGHT; Galaxy remains our top pick.
Company Results | China Tourism Group Duty Free (601888 CH/BUY/Rmb50.30/Target: Rmb68.70)
CTGDF’s 3Q26 results missed. Revenue declined 5% yoy, but net profit rose 25% yoy, driven by gross margin expansion, lower minority interests and non-operating items. Hainan’s offline duty-free sales growth slowed to 2% yoy (vs +4% in 2Q26), with per capita spending flat yoy (+1% yoy in 2Q26). CTGDF’s international business continued to expand, with revenue growing 71% yoy in 9M26, following the acquisition of DFS’ Greater China retail business. Maintain BUY; cut target price by 11% to Rmb68.70.
Company Results | Estun Automation Technology (002747 CH/BUY/Rmb29.24/Target: Rmb35.70)
Estun’s 3Q26 results missed on revenue due to seasonality and focus shifting away from low-value orders, but in return, profitability improved with margins expanding 3.8ppt yoy. Full-year revenue and profit guidance had been revised down, but management remained upbeat on 2027’s growth, citing robust overseas orders growth alongside solid embodied robot development. Upgrade to BUY and raise target price to Rmb35.70.
Company Results | Inner Mongolia Yili Industrial Group (600887 CH/BUY/Rmb30.15/Target: Rmb33.70)
Yili’s 3Q26 revenue missed expectations. However, core operating profit increased 7% yoy, with margin expanding 0.5ppt yoy. Net profit declined 6% due to higher impairment losses, lower fair value gains and a higher effective tax rate. With an improving distributor inventory and a low base, management expects the liquid milk business’s growth to accelerate in 4Q26. Management reiterated its full-year target of mid-single-digit revenue growth, with core operating margin improving yoy. Maintain BUY. Raise target price by 4% to Rmb33.70.
Company Results | Kweichow Moutai (600519 CH/HOLD/Rmb1,392.05/Target: Rmb1,458.00)
Moutai’s 3Q26 revenue rose 3% yoy and net profit rose 4% yoy, both in line with consensus estimates. By channel, direct sales rose 40% yoy, while wholesale channel sales declined 22% yoy. i-Moutai sales came in at Rmb18.3b, contributing 84% of direct sales. As of end-3Q26, contract liabilities fell 73% yoy and 34% qoq to Rmb2.1b, while cash inflow from sales of goods and services rose 3% yoy to Rmb45.1b. Maintain HOLD; raise target price by 13% to Rmb1,458.00.
Company Results | Shenzhen Mindray Bio-Medical Electronics (300760 CH/BUY/Rmb181.75/Target: Rmb210.00)
9M26 revenue rose 4.9% yoy to Rmb27.1b and adjusted net earnings declined 2.8% yoy to Rmb7.3b, in line with our full-year growth estimates. 3Q26 revenue growth slowed to 2.9% and earnings declined 1.6% yoy on forex losses. On a constant currency basis, 3Q26 revenue grew 6.0% yoy. Overseas revenue rose 11.0% yoy in 9M26 to account for 53% of sales. Mindray expects the overseas and emerging businesses to continue driving growth in 2027. Maintain BUY. Raise target price to Rmb210.00.
Company Results | TAL Educational Group (TAL US/BUY/US$10.14/Target: US$15.00)
TAL's 2QFY27 revenue grew 15% yoy to US$995m, 7% and 8% below our and consensus estimates. Non-GAAP operating profit more than doubled to US$248m, with operating margin expanding 12.4ppt yoy to 25% as S&M expenses fell 15% yoy. Non-GAAP net profit fell short of expectations and came in at losses of US$36m vs the street’s estimate of US$200m due to fair-value losses on investments and tax charges. Maintain BUY with a lower target price of US$15.00.
Company Results | Tinci Materials (002709 CH/SELL/Rmb26.12/Target: Rmb19.00)
Tinci’s 3Q26 adjusted net profit of Rmb1,033m (+646% yoy/-17% qoq) missed on margins as LiPF6 prices fell. We expect LiPF6 weakness to drag earnings despite volume growth, and cut 2026-28 net profit forecasts by 22%/62%/62% to Rmb5.71b/Rmb3.60b/Rmb4.31b on lower ASP and gross margin. Downgrade to SELL; target price cut from Rmb54.00 to Rmb19.00.
Company Results | Weichai Power (2338 HK/BUY/HK$23.52/Target: HK$31.00)
Weichai’s 3Q26 adjusted net profit rose 13.9% yoy to Rmb3,220m, in line, while GAAP net profit fell 8.6% on Ballard fair value losses, credit provisions and forex. Power and energy will be the primary growth drivers, contributing about 20% of profit. Data centre diesel genset is guided to come in above 4,000 units in 2026 and above 6,000 in 2027. Upgrade to BUY. Target price: HK$31.00.
Company Update | Xiaomi Corp (1810 HK/HOLD/HK$26.48/Target: HK$25.90)
Xiaomi’s 3Q26 earnings are expected to be underwhelming in light of weakened consumer demand across smartphones, automobiles and IoT. That said, we expect a pleasant surprise in its smartphone business which was primarily driven by a better product mix. Maintain HOLD with a lower target price of HK$25.90.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


Our latest research

30 Oct 2026
Momenta Global / Budweiser APAC / BYD Electronics / Foxconn Industrial Internet / Geely Auto / Haier Smart Home / Midea Group / NAURA Technology / New Oriental Education / Zhejiang Sanhua Intelligent Controls

29 Oct 2026
ASMPT / CSPC Innovation Pharmaceutical / Ningbo Joyson Electronic Corporation / Tsingtao Brewery / Tencent Holdings

28 Oct 2026