Analyst
Analyst
3Q26 Growth Edges Up To 4.5% yoy; September Data Mixed
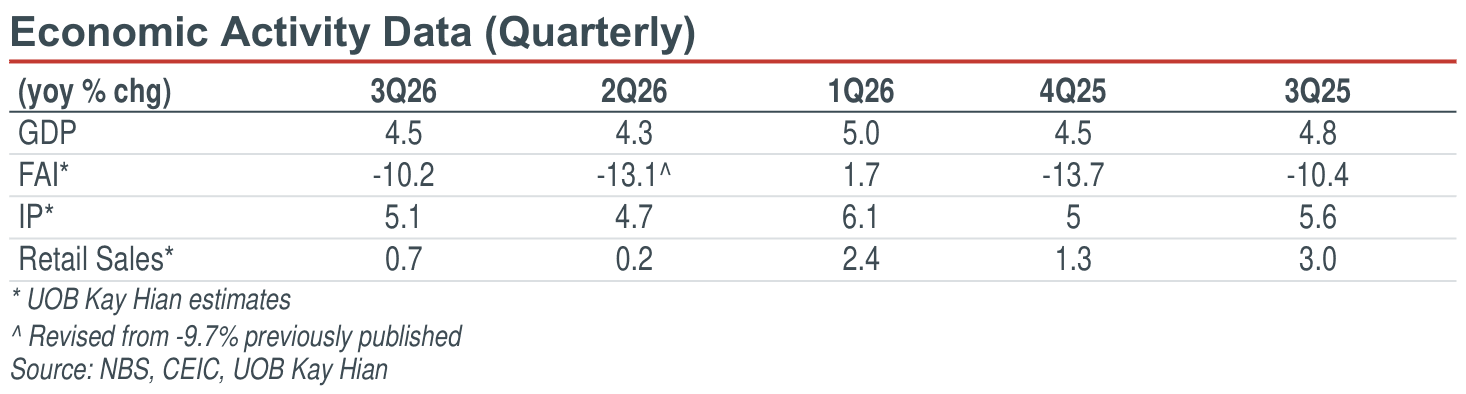
- China’s 3Q26 real GDP growth edged up to 4.5% yoy (+0.2ppt qoq), slightly above consensus of 4.4% yoy, bringing 9M26 growth to 4.6% yoy. The secondary sector led the improvement, with quarterly IP growth rising to 5.1% yoy from 4.7% yoy, while the quarterly FAI contraction narrowed to 10.2% yoy from 13.1% yoy.
- September data was mixed. Retail sales growth rebounded to 1.1% yoy (+0.7ppt mom), above consensus of 0.5% yoy, and industrial production growth rose to 5.5% yoy (+0.3ppt mom). However, FAI fell 7.2% ytd yoy as property FAI ytd deepened to -20.6% yoy, worse than expected. The unemployment rate improved to 5.2%.
- With 9M26 growth at 4.6% yoy and a low 4Q25 base for comparison, we raise our 2026 real GDP forecast to 4.5% yoy from 4.2% yoy. The changes are supported by stronger-than-expected contribution from external demand.
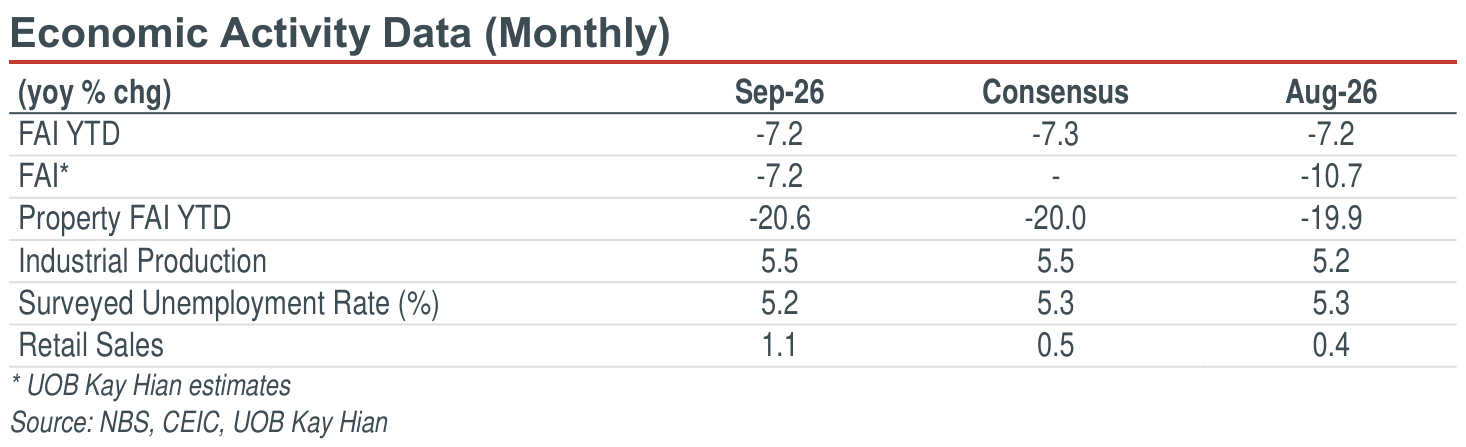
What’s New
- China’s 3Q26 real GDP growth edged up to 4.5% yoy, up from 2Q26’s 4.3% yoy but below 3Q25’s 4.8% yoy, bringing 9M26 growth to 4.6% yoy. On a qoq basis, GDP grew 1.2% in 3Q26, above Bloomberg’s consensus estimate of 1.0% and up from 0.9% in 2Q26. By industry, the tertiary sector posted 5.2% yoy (+0.1ppt qoq) growth, while the secondary sector led the improvement by growing 3.4% yoy (+0.4ppt qoq) and the primary sector rose 3.6% yoy (-0.1ppt qoq). Quarterly IP growth improved to 5.1% yoy (+0.4ppt qoq) and quarterly retail sales growth to 0.7% yoy (+0.5ppt qoq), while the quarterly FAI contraction narrowed to 10.2% yoy (+2.9ppt qoq). Quarterly retail sales growth also picked up to 0.7% yoy (+0.5ppt qoq) from 2Q26’s 0.2% yoy, but remained well below 1Q26’s 2.4% yoy. With consumption growth still below 1% yoy against IP growth of 5.1% yoy, the recovery remains led by production rather than consumption.
- Industrial production growth rose to 5.5% yoy in September (+0.3ppt mom), in line with Bloomberg’s consensus estimate of 5.5% yoy. In September, 31 of 41 major industries maintained yoy growth in output value (vs 29 in August). High-tech manufacturing continued to stand out (15.3% yoy, -1.4ppt mom), led by industrial robots (18.9% yoy), integrated circuits (18.4% yoy) and NEVs (16.9% yoy), even as overall automobile output fell 5.7% yoy, whereas mobile phones posted the steepest decline (-26.9% yoy). In contrast, commodity-related output remained weak, with crude oil processing volume down 8.4% yoy, cement down 5.3% yoy and steel products down 3.8% yoy. External demand remained a key driver, with export delivery value rising 17.0% yoy (August: 11.1% yoy). Overall, 3Q26 IP growth of 5.1% yoy improved from 2Q26’s 4.7% yoy.
3Q26 Growth Edges Up To 4.5% yoy; September Data Mixed
- China’s 3Q26 real GDP growth edged up to 4.5% yoy (+0.2ppt qoq), slightly above consensus of 4.4% yoy, bringing 9M26 growth to 4.6% yoy. The secondary sector led the improvement, with quarterly IP growth rising to 5.1% yoy from 4.7% yoy, while the quarterly FAI contraction narrowed to 10.2% yoy from 13.1% yoy.
- September data was mixed. Retail sales growth rebounded to 1.1% yoy (+0.7ppt mom), above consensus of 0.5% yoy, and industrial production growth rose to 5.5% yoy (+0.3ppt mom). However, FAI fell 7.2% ytd yoy as property FAI ytd deepened to -20.6% yoy, worse than expected. The unemployment rate improved to 5.2%.
- With 9M26 growth at 4.6% yoy and a low 4Q25 base for comparison, we raise our 2026 real GDP forecast to 4.5% yoy from 4.2% yoy. The changes are supported by stronger-than-expected contribution from external demand.
What’s New
- China’s 3Q26 real GDP growth edged up to 4.5% yoy, up from 2Q26’s 4.3% yoy but below 3Q25’s 4.8% yoy, bringing 9M26 growth to 4.6% yoy. On a qoq basis, GDP grew 1.2% in 3Q26, above Bloomberg’s consensus estimate of 1.0% and up from 0.9% in 2Q26. By industry, the tertiary sector posted 5.2% yoy (+0.1ppt qoq) growth, while the secondary sector led the improvement by growing 3.4% yoy (+0.4ppt qoq) and the primary sector rose 3.6% yoy (-0.1ppt qoq). Quarterly IP growth improved to 5.1% yoy (+0.4ppt qoq) and quarterly retail sales growth to 0.7% yoy (+0.5ppt qoq), while the quarterly FAI contraction narrowed to 10.2% yoy (+2.9ppt qoq). Quarterly retail sales growth also picked up to 0.7% yoy (+0.5ppt qoq) from 2Q26’s 0.2% yoy, but remained well below 1Q26’s 2.4% yoy. With consumption growth still below 1% yoy against IP growth of 5.1% yoy, the recovery remains led by production rather than consumption.
- Industrial production growth rose to 5.5% yoy in September (+0.3ppt mom), in line with Bloomberg’s consensus estimate of 5.5% yoy. In September, 31 of 41 major industries maintained yoy growth in output value (vs 29 in August). High-tech manufacturing continued to stand out (15.3% yoy, -1.4ppt mom), led by industrial robots (18.9% yoy), integrated circuits (18.4% yoy) and NEVs (16.9% yoy), even as overall automobile output fell 5.7% yoy, whereas mobile phones posted the steepest decline (-26.9% yoy). In contrast, commodity-related output remained weak, with crude oil processing volume down 8.4% yoy, cement down 5.3% yoy and steel products down 3.8% yoy. External demand remained a key driver, with export delivery value rising 17.0% yoy (August: 11.1% yoy). Overall, 3Q26 IP growth of 5.1% yoy improved from 2Q26’s 4.7% yoy.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


