

Analyst
Analyst
October Data Broadly Missed Expectations
- Industrial production growth slowed to 4.8% yoy in October (-0.7ppt mom), below Bloomberg’s consensus estimate of 5.3% yoy. FAI ytd growth fell further to -8.1% yoy (-0.9ppt mom), well below Bloomberg’s consensus estimate of -7.0% yoy, dragged by property FAI ytd (-21.6% yoy, -1.0ppt mom).
- Retail sales growth eased to 0.4% yoy (-0.7ppt mom), below Bloomberg’s consensus estimate of 0.8% yoy, reversing from September’s rebound. The surveyed unemployment rate improved to 5.1% (-0.1ppt mom), below consensus estimate of 5.2%.
- October’s data was generally below expectations and market negative. Looking ahead, we do not expect any large-scale stimulus measures before year-end, with policy expected to be focused on implementing existing measures. We believe that the December Central Economic Work Conference will provide the next window for additional demand-side support.
What’s New
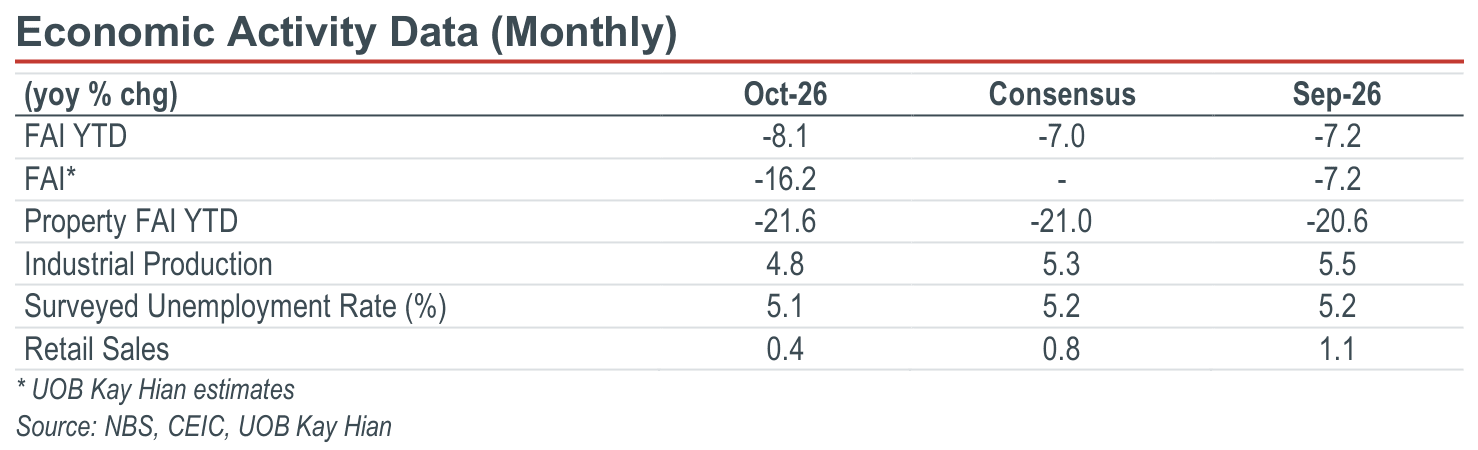
- Industrial production growth slowed to 4.8% yoy in October (-0.7ppt mom), below Bloomberg’s consensus estimate of 5.3% yoy. In October, 28 of 41 major industries maintained yoy growth in output value (vs 31 in September). High-tech manufacturing continued to stand out (17.6% yoy, +2.3ppt mom), led by industrial robots (26.0% yoy), integrated circuits (21.9% yoy) and NEVs (17.1% yoy), even as overall automobile output fell 7.7% yoy and mobile phones remained among the steepest declines (-26.9% yoy). Commodity-related output remained weak, with crude oil processing volume down 8.1% yoy, steel products down 5.1% yoy and cement down 1.3% yoy. External demand remained the key driver, with export delivery value rising 18.6% yoy (September: 17.0% yoy). With export deliveries accelerating while headline growth slowed, the miss appears to reflect weaker domestic-facing production.
- October’s retail sales growth eased to 0.4% yoy (-0.7ppt mom), below Bloomberg’s consensus estimate of 0.8% yoy, reversing from September’s rebound and matching August’s reading. By consumption type, catering revenue grew 0.7% yoy (-1.4ppt mom), while retail sales of goods rose 0.3% yoy (-0.7ppt mom). September’s main drivers lost momentum, with communication equipment slowing to 6.5% yoy (-24.6ppt mom) and tobacco and alcohol to 2.5% yoy (-11.3ppt mom). Gold, silver and jewellery (-28.7% yoy, -19.1ppt mom), automobiles (-21.4% yoy, -0.2ppt mom) and building and decoration materials (-11.2% yoy, -2.0ppt mom) remained the key drags.
- FAI ytd growth fell further to -8.1% yoy in October (-0.9ppt mom), well below Bloomberg’s consensus estimate of -7.0% yoy. Property FAI ytd deepened to -21.6% yoy (-1.0ppt mom), worse than consensus estimate of -21.0% yoy and hitting fresh multi-year lows, while residential property sales ytd fell 14.1% yoy (-0.4ppt mom). The weakness remained broader than property: infrastructure FAI contracted 5.1% yoy ytd (-0.9ppt mom) and manufacturing FAI contracted 2.9% yoy ytd (-0.8ppt mom), while private investment fell 11.4% yoy ytd (-1.0ppt mom). Our estimated single-month FAI contraction widened sharply to -16.2% yoy in October from -7.2% yoy in September, reversing four consecutive months of narrowing.
October Data Broadly Missed Expectations
- Industrial production growth slowed to 4.8% yoy in October (-0.7ppt mom), below Bloomberg’s consensus estimate of 5.3% yoy. FAI ytd growth fell further to -8.1% yoy (-0.9ppt mom), well below Bloomberg’s consensus estimate of -7.0% yoy, dragged by property FAI ytd (-21.6% yoy, -1.0ppt mom).
- Retail sales growth eased to 0.4% yoy (-0.7ppt mom), below Bloomberg’s consensus estimate of 0.8% yoy, reversing from September’s rebound. The surveyed unemployment rate improved to 5.1% (-0.1ppt mom), below consensus estimate of 5.2%.
- October’s data was generally below expectations and market negative. Looking ahead, we do not expect any large-scale stimulus measures before year-end, with policy expected to be focused on implementing existing measures. We believe that the December Central Economic Work Conference will provide the next window for additional demand-side support.
What’s New
- Industrial production growth slowed to 4.8% yoy in October (-0.7ppt mom), below Bloomberg’s consensus estimate of 5.3% yoy. In October, 28 of 41 major industries maintained yoy growth in output value (vs 31 in September). High-tech manufacturing continued to stand out (17.6% yoy, +2.3ppt mom), led by industrial robots (26.0% yoy), integrated circuits (21.9% yoy) and NEVs (17.1% yoy), even as overall automobile output fell 7.7% yoy and mobile phones remained among the steepest declines (-26.9% yoy). Commodity-related output remained weak, with crude oil processing volume down 8.1% yoy, steel products down 5.1% yoy and cement down 1.3% yoy. External demand remained the key driver, with export delivery value rising 18.6% yoy (September: 17.0% yoy). With export deliveries accelerating while headline growth slowed, the miss appears to reflect weaker domestic-facing production.
- October’s retail sales growth eased to 0.4% yoy (-0.7ppt mom), below Bloomberg’s consensus estimate of 0.8% yoy, reversing from September’s rebound and matching August’s reading. By consumption type, catering revenue grew 0.7% yoy (-1.4ppt mom), while retail sales of goods rose 0.3% yoy (-0.7ppt mom). September’s main drivers lost momentum, with communication equipment slowing to 6.5% yoy (-24.6ppt mom) and tobacco and alcohol to 2.5% yoy (-11.3ppt mom). Gold, silver and jewellery (-28.7% yoy, -19.1ppt mom), automobiles (-21.4% yoy, -0.2ppt mom) and building and decoration materials (-11.2% yoy, -2.0ppt mom) remained the key drags.
- FAI ytd growth fell further to -8.1% yoy in October (-0.9ppt mom), well below Bloomberg’s consensus estimate of -7.0% yoy. Property FAI ytd deepened to -21.6% yoy (-1.0ppt mom), worse than consensus estimate of -21.0% yoy and hitting fresh multi-year lows, while residential property sales ytd fell 14.1% yoy (-0.4ppt mom). The weakness remained broader than property: infrastructure FAI contracted 5.1% yoy ytd (-0.9ppt mom) and manufacturing FAI contracted 2.9% yoy ytd (-0.8ppt mom), while private investment fell 11.4% yoy ytd (-1.0ppt mom). Our estimated single-month FAI contraction widened sharply to -16.2% yoy in October from -7.2% yoy in September, reversing four consecutive months of narrowing.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


