

Analyst
Analyst
M1 Rebounds, But Credit Demand Remains Weak
- Oct 26’s M1 growth rebounded to 4.4% yoy (+1.2ppt mom), above consensus of 3.5% yoy, while M2 growth eased slightly to 7.1% yoy (-0.1ppt mom), pointing to firmer transactional demand for money.
- New bank loans contracted by Rmb0.10t, missing consensus of Rmb0.08t, dragged by household loans (-Rmb0.43t) and bills financing (-Rmb0.31t), though corporate medium- to long-term loans held up at Rmb0.16t (+Rmb0.13t yoy).
- New TSF of Rmb1.14t missed consensus of Rmb1.45t, but government bond issuance lifted outstanding TSF growth to 7.2% yoy (+0.1ppt mom), while outstanding bank loans growth slipped further to 4.7% yoy (-0.1ppt mom). Overall, October’s data is market neutral.
Our View
- M2 growth eased by 0.1ppt to 7.1% yoy in Oct 26, slightly below Bloomberg’s consensus forecast of 7.2% yoy. This extends the deceleration to a fifth consecutive month and marks the slowest pace since Mar 25. In contrast, M1 money supply growth rebounded to 4.4% yoy from 3.2% yoy in September, well above market expectations of 3.5% yoy and the highest since May 26. The rebound was partly supported by a lower base. However, the beat against consensus points to firmer transactional demand for money, with the gap between M2 and M1 growth narrowing to 2.7ppt from 4.0ppt as funds moved from time deposits into demand deposits. M0 growth edged up to 10.7% yoy (+0.1ppt mom).
- Banks recorded a net loan repayment of Rmb0.10t in Oct 26, reversing from September’s Rmb1.08t increase and missing Bloomberg’s consensus estimate of Rmb0.08t, as well as the Rmb0.22t recorded in Oct 25. This is the third monthly contraction this year. New household loans fell to -Rmb0.43t (-Rmb0.43t mom), with long-term borrowing down Rmb0.16t despite the mortgage interest subsidy on new first-home loans that took effect on 1 October. New corporate & government loans slowed to Rmb0.19t (-Rmb0.95t mom), as bills financing contracted by Rmb0.31t against an increase of Rmb0.50t a year ago. Medium- to long-term corporate loans held up at Rmb0.16t, above Oct 25’s Rmb0.03t.
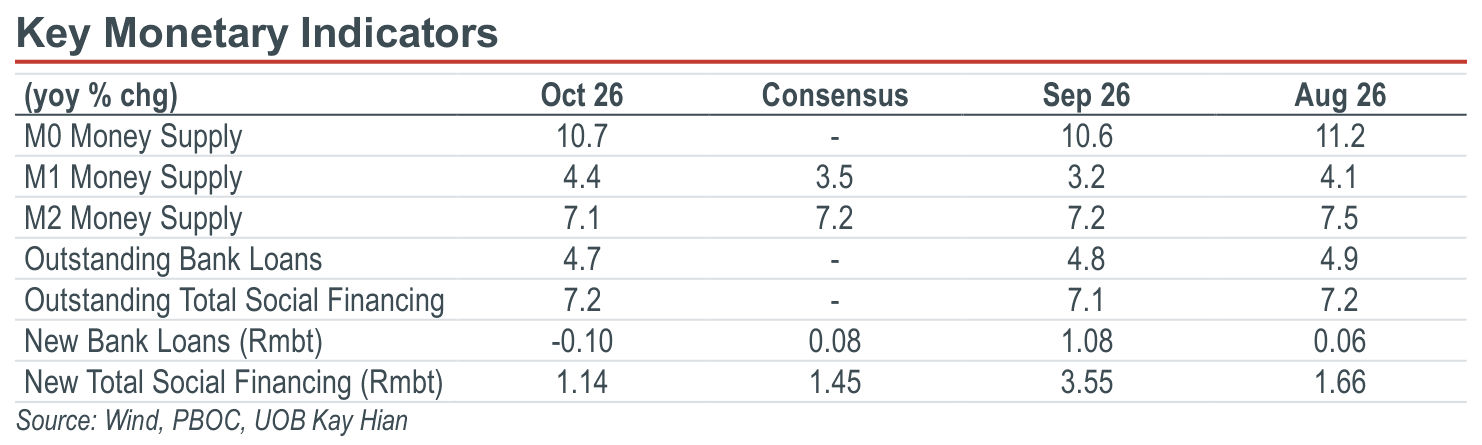
- Oct 26’s new TSF fell to Rmb1.14t from Sep 26’s Rmb3.55t, missing Bloomberg’s consensus of Rmb1.45t but above Oct 25’s Rmb0.82t. New government bond issuance of Rmb1.18t (-Rmb0.35t mom) exceeded the entire TSF increase and was more than double Oct 25’s Rmb0.49t, lifting its growth to 14.4% yoy (+0.7ppt mom). This offset renminbi loans within TSF of -Rmb0.58t. Corporate bond growth picked up to 9.6% yoy (+0.3ppt mom), and entrusted loans growth rose to 1.7% yoy (+0.2ppt mom), consistent with recent NDRC’s efforts to improve financing for FAI projects. The contraction in bank acceptances narrowed to -4.4% yoy (+4.4ppt mom), while trust loans growth turned negative at -0.6% yoy (-1.3ppt mom).
M1 Rebounds, But Credit Demand Remains Weak
- Oct 26’s M1 growth rebounded to 4.4% yoy (+1.2ppt mom), above consensus of 3.5% yoy, while M2 growth eased slightly to 7.1% yoy (-0.1ppt mom), pointing to firmer transactional demand for money.
- New bank loans contracted by Rmb0.10t, missing consensus of Rmb0.08t, dragged by household loans (-Rmb0.43t) and bills financing (-Rmb0.31t), though corporate medium- to long-term loans held up at Rmb0.16t (+Rmb0.13t yoy).
- New TSF of Rmb1.14t missed consensus of Rmb1.45t, but government bond issuance lifted outstanding TSF growth to 7.2% yoy (+0.1ppt mom), while outstanding bank loans growth slipped further to 4.7% yoy (-0.1ppt mom). Overall, October’s data is market neutral.
Our View
- M2 growth eased by 0.1ppt to 7.1% yoy in Oct 26, slightly below Bloomberg’s consensus forecast of 7.2% yoy. This extends the deceleration to a fifth consecutive month and marks the slowest pace since Mar 25. In contrast, M1 money supply growth rebounded to 4.4% yoy from 3.2% yoy in September, well above market expectations of 3.5% yoy and the highest since May 26. The rebound was partly supported by a lower base. However, the beat against consensus points to firmer transactional demand for money, with the gap between M2 and M1 growth narrowing to 2.7ppt from 4.0ppt as funds moved from time deposits into demand deposits. M0 growth edged up to 10.7% yoy (+0.1ppt mom).
- Banks recorded a net loan repayment of Rmb0.10t in Oct 26, reversing from September’s Rmb1.08t increase and missing Bloomberg’s consensus estimate of Rmb0.08t, as well as the Rmb0.22t recorded in Oct 25. This is the third monthly contraction this year. New household loans fell to -Rmb0.43t (-Rmb0.43t mom), with long-term borrowing down Rmb0.16t despite the mortgage interest subsidy on new first-home loans that took effect on 1 October. New corporate & government loans slowed to Rmb0.19t (-Rmb0.95t mom), as bills financing contracted by Rmb0.31t against an increase of Rmb0.50t a year ago. Medium- to long-term corporate loans held up at Rmb0.16t, above Oct 25’s Rmb0.03t.
- Oct 26’s new TSF fell to Rmb1.14t from Sep 26’s Rmb3.55t, missing Bloomberg’s consensus of Rmb1.45t but above Oct 25’s Rmb0.82t. New government bond issuance of Rmb1.18t (-Rmb0.35t mom) exceeded the entire TSF increase and was more than double Oct 25’s Rmb0.49t, lifting its growth to 14.4% yoy (+0.7ppt mom). This offset renminbi loans within TSF of -Rmb0.58t. Corporate bond growth picked up to 9.6% yoy (+0.3ppt mom), and entrusted loans growth rose to 1.7% yoy (+0.2ppt mom), consistent with recent NDRC’s efforts to improve financing for FAI projects. The contraction in bank acceptances narrowed to -4.4% yoy (+4.4ppt mom), while trust loans growth turned negative at -0.6% yoy (-1.3ppt mom).
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


