
Company Coverage
Yadea Group Holdings (1585 HK): 1H26: Net Profit Misses On Sales Volume, Set To Recover From 2H26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$10.30
HK$16.00
+55.3%
HK$18.00
Analyst
Highlights
1H26 net profit missed estimates at Rmb1.2b (-27% yoy), with the misses in sales volume and margins offsetting the beat in ASP.
Sales volume is set to recover from 2H26, driven by strong order flows, market share gain amid accelerating industry consolidation, new product debuts, and overseas expansion.
ASP and margins will be underpinned by premiumisation and globalisation of sales mix.
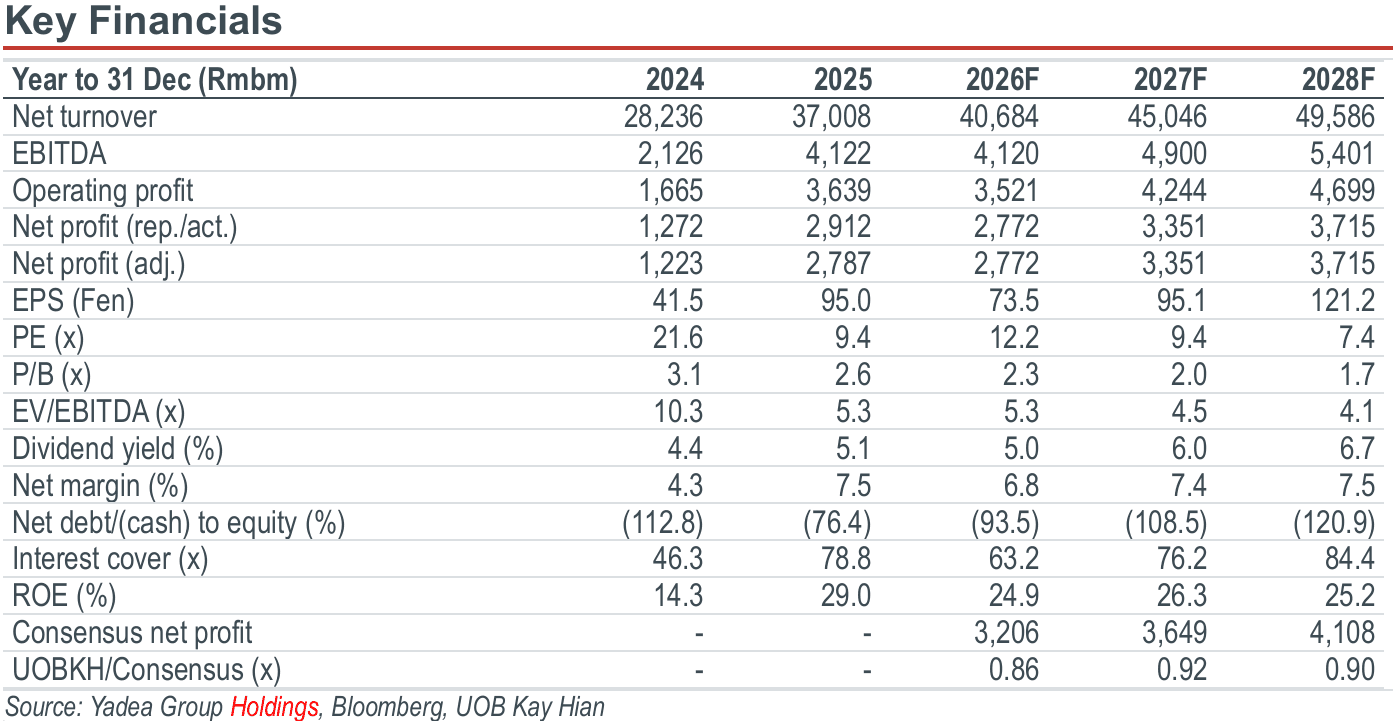
Cut our 2026-28 net profit forecasts by 14%/9%/10% to Rmb2,768m/Rmb3,340m/Rmb3,696m respectively, based on lower sales volume and higher ASP. Maintain BUY and cut target price from HK$18.00 to HK$16.00.
Analysis
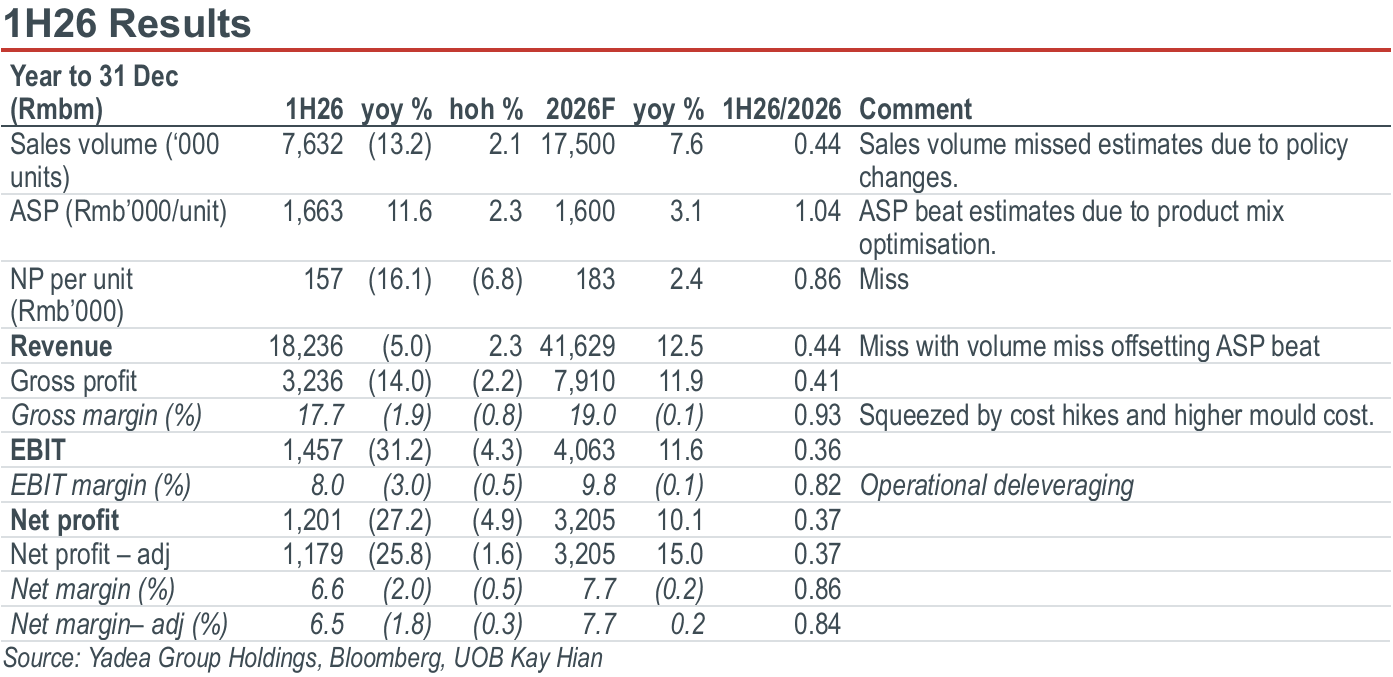
1H26 net profit missed estimates at Rmb1.2b (-27.2% yoy), due to lower than-expected sales volume and margins.
Revenue dropped 5% yoy to Rmb18.24b in 1H26 on disappointing sales volume of 7.63m units (-13.2% yoy) and upbeat ASP of Rmb1,663 (+11.6% yoy). The sales drop was due to the implementation of the new national standard on 1 Dec 25 and the cancellation of state’s trade-in subsidies for two-wheeled electric vehicles (2WEVs) on 1 Jan 26, which weighed on end-demand, as well as the destocking of 0.8m units in 1H25, which raised the comparison base. The ASP hike was due to product mix optimisation. The share of the pricier electric scooters (ASP: Rmb1,845) in total sales volume rose 21.5ppt yoy to 45.7% in 1H26.
Highlights
1H26 net profit missed estimates at Rmb1.2b (-27% yoy), with the misses in sales volume and margins offsetting the beat in ASP.
Sales volume is set to recover from 2H26, driven by strong order flows, market share gain amid accelerating industry consolidation, new product debuts, and overseas expansion.
ASP and margins will be underpinned by premiumisation and globalisation of sales mix.
Cut our 2026-28 net profit forecasts by 14%/9%/10% to Rmb2,768m/Rmb3,340m/Rmb3,696m respectively, based on lower sales volume and higher ASP. Maintain BUY and cut target price from HK$18.00 to HK$16.00.
Analysis
1H26 net profit missed estimates at Rmb1.2b (-27.2% yoy), due to lower than-expected sales volume and margins.
Revenue dropped 5% yoy to Rmb18.24b in 1H26 on disappointing sales volume of 7.63m units (-13.2% yoy) and upbeat ASP of Rmb1,663 (+11.6% yoy). The sales drop was due to the implementation of the new national standard on 1 Dec 25 and the cancellation of state’s trade-in subsidies for two-wheeled electric vehicles (2WEVs) on 1 Jan 26, which weighed on end-demand, as well as the destocking of 0.8m units in 1H25, which raised the comparison base. The ASP hike was due to product mix optimisation. The share of the pricier electric scooters (ASP: Rmb1,845) in total sales volume rose 21.5ppt yoy to 45.7% in 1H26.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$10.30
HK$16.00
+55.3%
HK$18.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

8 Oct 2026
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

29 Sept 2026