
Company Coverage
Q Technology Group (1478 HK): 1H26: Margin Pressure And Elevated R&D Weigh On Earnings; Automotive Remains The Clearest Growth Driver
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$6.18
HK$6.70
+8.4%
HK$9.10
Analyst
Analyst
Highlights
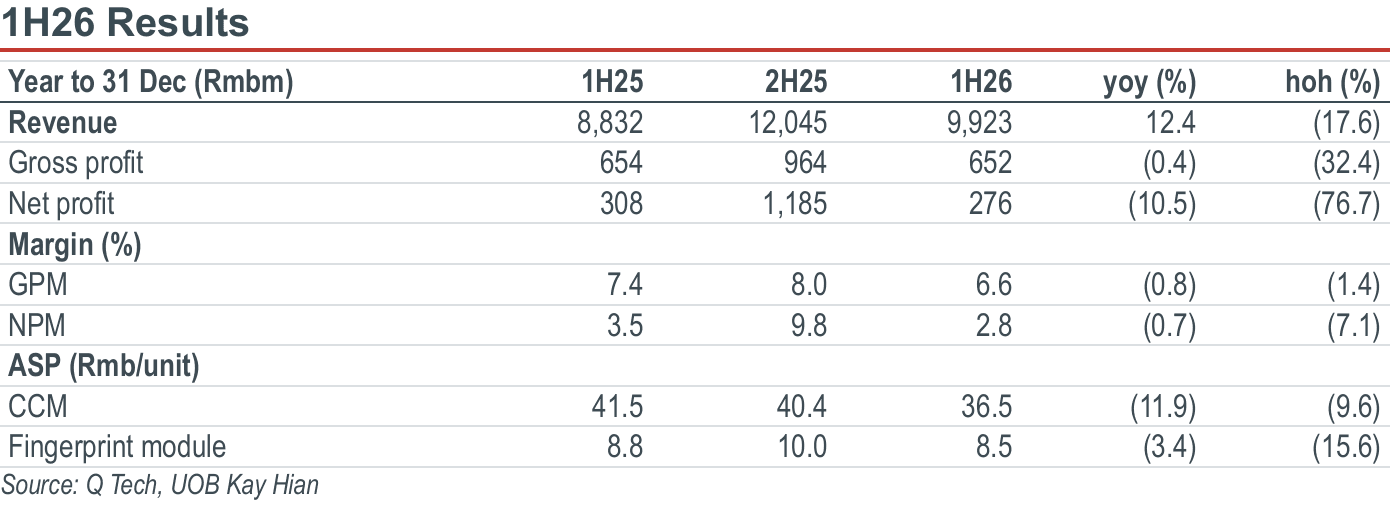
Revenue rose 12.4% yoy to Rmb9.9b, but net profit fell 10.5% yoy to Rmb276m as gross margin contracted 0.8ppt yoy to 6.6% and R&D expenses increased 24.2% yoy.
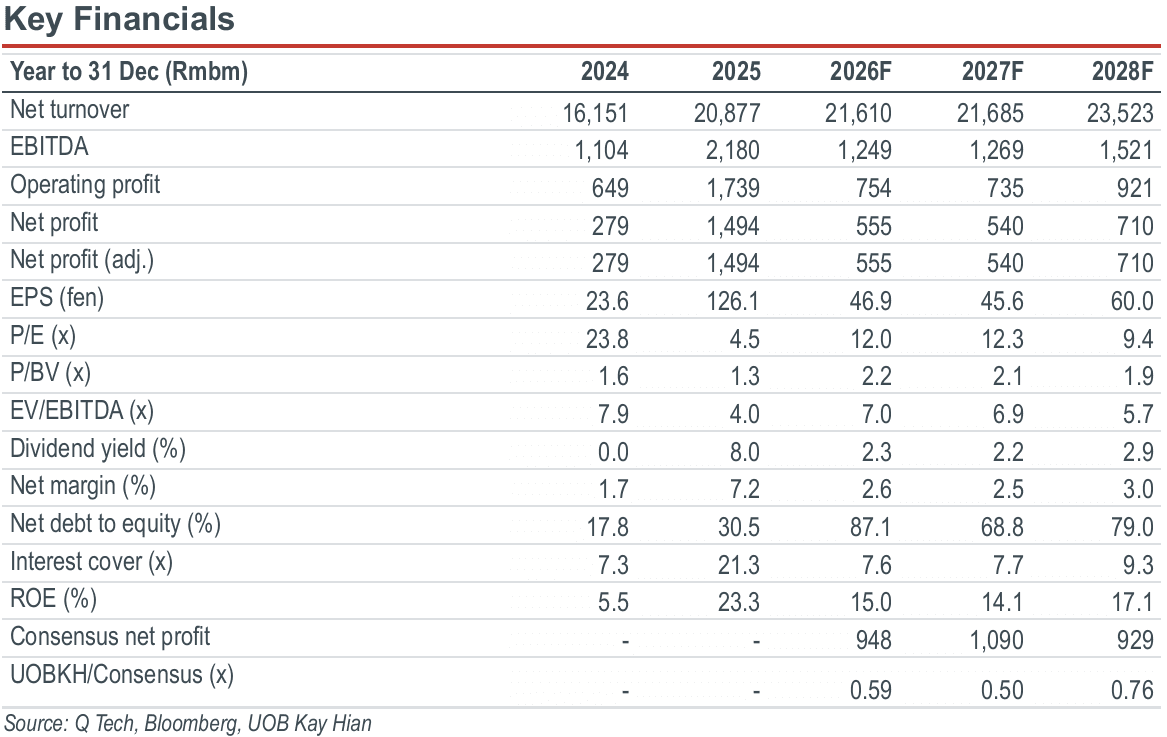
Management highlighted smart driving, AI glasses, robotics and optical interconnect as key future growth drivers, with smart driving and AI glasses likely to remain the most visible near-term opportunities. Maintain HOLD. Target price: HK$6.70.
Analysis
Bottom line was weighed down by margin compression and elevated opex. Revenue grew 12.4% yoy but declined 17.6% hoh to Rmb9.9b, broadly in line with consensus expectation. Gross margin contracted 0.8ppt yoy and 1.4ppt hoh to 6.6%, around 1ppt below consensus, primarily due to an unfavourable product mix shift, lower contribution from higher-end camera modules and ASP pressure in the mobile camera business. R&D expenses rose 24.2% yoy to Rmb346.7m, driven by increased investment in emerging businesses. As a result, net profit declined to Rmb276.0m, down 10.5% yoy and 76.7% hoh, missing consensus estimate by 14.8%.
Highlights
Revenue rose 12.4% yoy to Rmb9.9b, but net profit fell 10.5% yoy to Rmb276m as gross margin contracted 0.8ppt yoy to 6.6% and R&D expenses increased 24.2% yoy.
Management highlighted smart driving, AI glasses, robotics and optical interconnect as key future growth drivers, with smart driving and AI glasses likely to remain the most visible near-term opportunities. Maintain HOLD. Target price: HK$6.70.
Analysis
Bottom line was weighed down by margin compression and elevated opex. Revenue grew 12.4% yoy but declined 17.6% hoh to Rmb9.9b, broadly in line with consensus expectation. Gross margin contracted 0.8ppt yoy and 1.4ppt hoh to 6.6%, around 1ppt below consensus, primarily due to an unfavourable product mix shift, lower contribution from higher-end camera modules and ASP pressure in the mobile camera business. R&D expenses rose 24.2% yoy to Rmb346.7m, driven by increased investment in emerging businesses. As a result, net profit declined to Rmb276.0m, down 10.5% yoy and 76.7% hoh, missing consensus estimate by 14.8%.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$6.18
HK$6.70
+8.4%
HK$9.10
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Sept 2026
Sunny Optical (2382 HK): NDR Takeaways: 2026 Guidance Reiterated With Pan-IoT And AR Glasses Driving Growth

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

29 Sept 2026
