
Company Coverage
Li Ning (2331 HK): 1H26: Net Profit Better Than Feared; Lowered Revenue And Net Margin Guidance
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$14.25
HK$21.80
+53.0%
HK$23.30
Analyst
Analyst
Highlights
Li Ning’s 1H26 net profit was better than feared. Looking ahead, with the challenging consumption environment, management lowers the full-year revenue growth guidance to low single-digit from high single-digit.
In addition, with the stepped up A&P expenses in 2H26, primarily driven by Stephen Curry’s partnership, net margin expectation is lowered to mid- to high single-digit range from the previously high single-digit range.
Maintain BUY, cut target price by 6% to HK$21.80.
Analysis
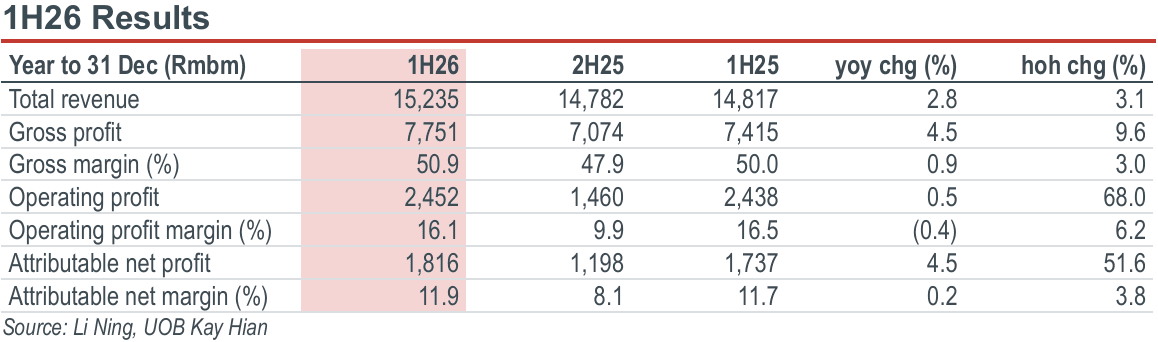
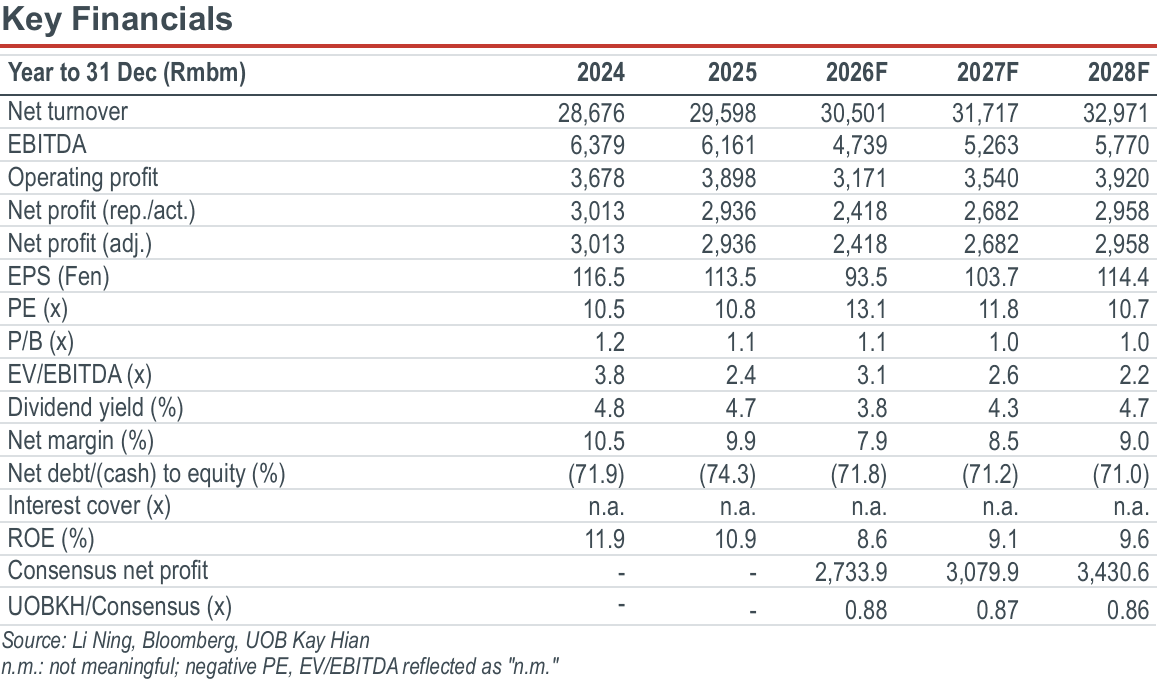
1H26 net profit better than feared. Li Ning reported 1H26 revenue of Rmb15,235m (+3% yoy; +3% hoh). Gross margin was 50.9% (+0.9ppt yoy, +3.0ppt hoh), as cost optimisation in the wholesale and e-commerce channels more than offset deeper discounts in the direct retail channel. Operating profit was Rmb2,452m (+1% yoy, +68% hoh), with an operating margin at 16.1% (-0.4ppt yoy, +6.2ppt hoh). The yoy decline in operating margin was primarily due to higher advertising and promotion expenses (A&P ratio at 11.2%, +2.2ppt yoy), given that the company continued to focus on Olympic and national team partnerships, while deepening professional sports areas. Net profit was Rmb1,816m (+5% yoy, +52% hoh), 5% above VA consensus, with a net margin at 11.9% (+0.2ppt yoy, +3.8ppt hoh), thanks to lower income taxes (effective tax rate lowered to 25.8% from 33.3% in 1H25). Net operating cash inflow was Rmb954m, down 60% yoy, primarily due to rising A&P expenses, including prepayment for Stephen Curry’s partnership, and lower government subsidies. The company declared an interim dividend of Rmb35.12 cents per share, implying a payout ratio of 50% (vs 50% in 1H25).
Highlights
Li Ning’s 1H26 net profit was better than feared. Looking ahead, with the challenging consumption environment, management lowers the full-year revenue growth guidance to low single-digit from high single-digit.
In addition, with the stepped up A&P expenses in 2H26, primarily driven by Stephen Curry’s partnership, net margin expectation is lowered to mid- to high single-digit range from the previously high single-digit range.
Maintain BUY, cut target price by 6% to HK$21.80.
Analysis
1H26 net profit better than feared. Li Ning reported 1H26 revenue of Rmb15,235m (+3% yoy; +3% hoh). Gross margin was 50.9% (+0.9ppt yoy, +3.0ppt hoh), as cost optimisation in the wholesale and e-commerce channels more than offset deeper discounts in the direct retail channel. Operating profit was Rmb2,452m (+1% yoy, +68% hoh), with an operating margin at 16.1% (-0.4ppt yoy, +6.2ppt hoh). The yoy decline in operating margin was primarily due to higher advertising and promotion expenses (A&P ratio at 11.2%, +2.2ppt yoy), given that the company continued to focus on Olympic and national team partnerships, while deepening professional sports areas. Net profit was Rmb1,816m (+5% yoy, +52% hoh), 5% above VA consensus, with a net margin at 11.9% (+0.2ppt yoy, +3.8ppt hoh), thanks to lower income taxes (effective tax rate lowered to 25.8% from 33.3% in 1H25). Net operating cash inflow was Rmb954m, down 60% yoy, primarily due to rising A&P expenses, including prepayment for Stephen Curry’s partnership, and lower government subsidies. The company declared an interim dividend of Rmb35.12 cents per share, implying a payout ratio of 50% (vs 50% in 1H25).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$14.25
HK$21.80
+53.0%
HK$23.30
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

29 Sept 2026
Sunny Optical (2382 HK): NDR Takeaways: 2026 Guidance Reiterated With Pan-IoT And AR Glasses Driving Growth

7 Oct 2026
