

Periodic/Sector reports
Banking: 3Q26 Results Preview: Credit Costs Expected To Decline QOQ
OVERWEIGHT (Maintained)
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
- We expect the sector to report a net profit of Bt64b, -10% yoy, +0.4% qoq.
- Expect an extension of “Thai Help Thai Plus 60/10” and the launch of Thai Travel Thai Plus.
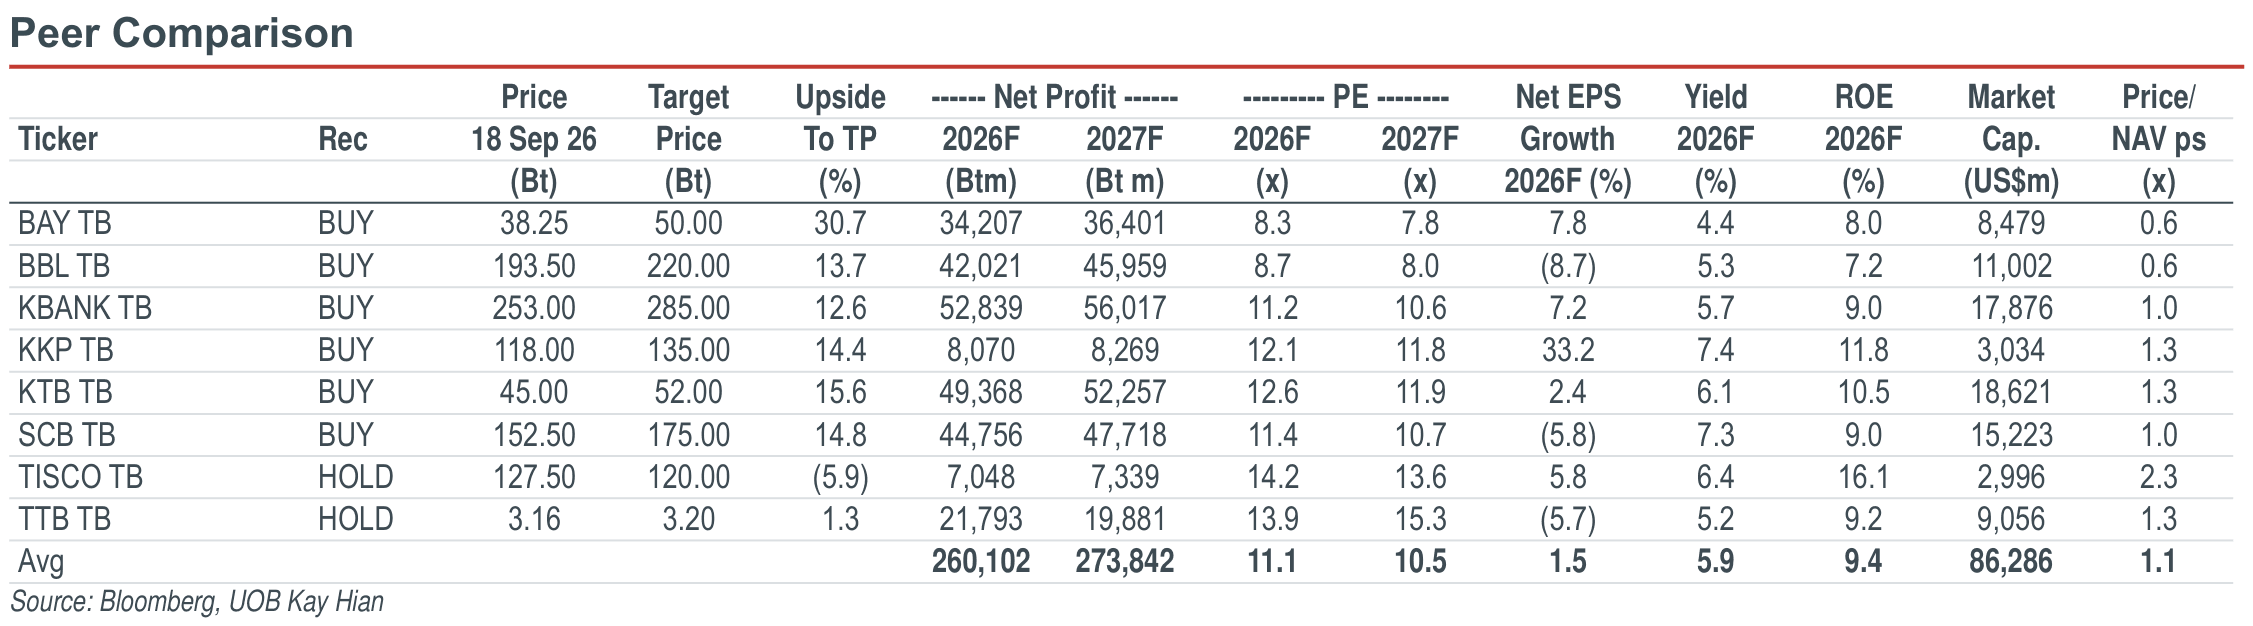
- Maintain OVERWEIGHT on the sector. Top picks: KBANK and KTB.
Analysis
- Expect 3Q26 earnings to drop yoy and qoq. We expect banks under our coverage to report an aggregated net profit of around Bt64b in 3Q26, down 10% yoy but up 0.4% qoq. Excluding provisioning, we expect the banking sector’s pre-provision operating profit to decline 10% yoy and 3% qoq.
- Forecast a flat qoq loan growth in 3Q26. We project that the banking sector’s loan portfolio will be flat qoq but increase 3% yoy in 3Q26. Overall, we expect banks to remain cautious in lending and focus on corporate loans. Meanwhile, we forecast TISCO Financial Group (TISCO) continuing to expand its new car hire-purchase loan portfolio, and expect Bank of Ayudhya (BAY) to continue to grow its ASEAN loan portfolio.
- Expect an extension of Thai Help Thai Plus 60/10 for two months and the launch of Thai Travel Thai Plus. After its launch in Jun 26, the Thai Help Thai Plus 60/40 programme will be terminated at the end of Sep 26. However, the Cabinet is set to review a proposed two-month extension of the co-payment scheme, with some changes to the conditions and extending the programme through Nov 26. According to local news, this programme helps to spur domestic spending. Moreover, the Street expects the government to launch the Thai Travel Thai Plus programme, which will take effect from Apr 27. This programme is expected to offer 1m entitlements countrywide, with a maximum of five entitlements per person. The government will subsidise Bt1,500 per night for major cities and Bt2,000 per night for less-visited areas. We expect this move regarding Thai Help Thai Plus 60/40 to boost the domestic economy in 4Q26 and expect Thai Travel Thai Plus to have a positive impact on the Thai economy and help the low season tourism during mid-27.
- Expect credit costs to decrease yoy and qoq in 3Q26. We project that the banking sector’s credit costs will drop 29bp yoy and 12bp qoq to 131bp in 3Q26. Many banks set special provisions in 1Q26 to cushion against the impact of Middle East tensions. However, the actual earnings results in 1H26 did not present any concern about the Middle East conflict. Meanwhile, banks have also stated that the impact from the Middle East conflict was less than expected. Therefore, we expect to see a reduction in credit costs in 2H26 and are optimistic about the credit cost outlook and asset quality for the sector. We foresee the NPL ratio stabilising qoq at 3.1% in 3Q26.
Highlights
- We expect the sector to report a net profit of Bt64b, -10% yoy, +0.4% qoq.
- Expect an extension of “Thai Help Thai Plus 60/10” and the launch of Thai Travel Thai Plus.
- Maintain OVERWEIGHT on the sector. Top picks: KBANK and KTB.
Analysis
- Expect 3Q26 earnings to drop yoy and qoq. We expect banks under our coverage to report an aggregated net profit of around Bt64b in 3Q26, down 10% yoy but up 0.4% qoq. Excluding provisioning, we expect the banking sector’s pre-provision operating profit to decline 10% yoy and 3% qoq.
- Forecast a flat qoq loan growth in 3Q26. We project that the banking sector’s loan portfolio will be flat qoq but increase 3% yoy in 3Q26. Overall, we expect banks to remain cautious in lending and focus on corporate loans. Meanwhile, we forecast TISCO Financial Group (TISCO) continuing to expand its new car hire-purchase loan portfolio, and expect Bank of Ayudhya (BAY) to continue to grow its ASEAN loan portfolio.
- Expect an extension of Thai Help Thai Plus 60/10 for two months and the launch of Thai Travel Thai Plus. After its launch in Jun 26, the Thai Help Thai Plus 60/40 programme will be terminated at the end of Sep 26. However, the Cabinet is set to review a proposed two-month extension of the co-payment scheme, with some changes to the conditions and extending the programme through Nov 26. According to local news, this programme helps to spur domestic spending. Moreover, the Street expects the government to launch the Thai Travel Thai Plus programme, which will take effect from Apr 27. This programme is expected to offer 1m entitlements countrywide, with a maximum of five entitlements per person. The government will subsidise Bt1,500 per night for major cities and Bt2,000 per night for less-visited areas. We expect this move regarding Thai Help Thai Plus 60/40 to boost the domestic economy in 4Q26 and expect Thai Travel Thai Plus to have a positive impact on the Thai economy and help the low season tourism during mid-27.
- Expect credit costs to decrease yoy and qoq in 3Q26. We project that the banking sector’s credit costs will drop 29bp yoy and 12bp qoq to 131bp in 3Q26. Many banks set special provisions in 1Q26 to cushion against the impact of Middle East tensions. However, the actual earnings results in 1H26 did not present any concern about the Middle East conflict. Meanwhile, banks have also stated that the impact from the Middle East conflict was less than expected. Therefore, we expect to see a reduction in credit costs in 2H26 and are optimistic about the credit cost outlook and asset quality for the sector. We foresee the NPL ratio stabilising qoq at 3.1% in 3Q26.
OVERWEIGHT (Maintained)
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


