

Periodic/Sector reports
Automobile: Weekly: Lithium Carbonate Price Drop Reconfirms Our Preference For OEMs; Bottom-fishing Opportunity Emerges For CATL
Highlights
- Lithium carbonate fell more than 20% during September to Rmb124,020/tonne, cutting revenue at Ganfeng and Tinci.
- Geely received more than 43,900 Cruiser 700 pre-orders in an hour, and four September launches are now priced.
- BYD, CATL and Pony AI showed electric trucks at the IAA Hannover, opening a second export front.
- CATL dropped 10.0% to Rmb304.30, a one-year low; we see the switching fear as overdone.
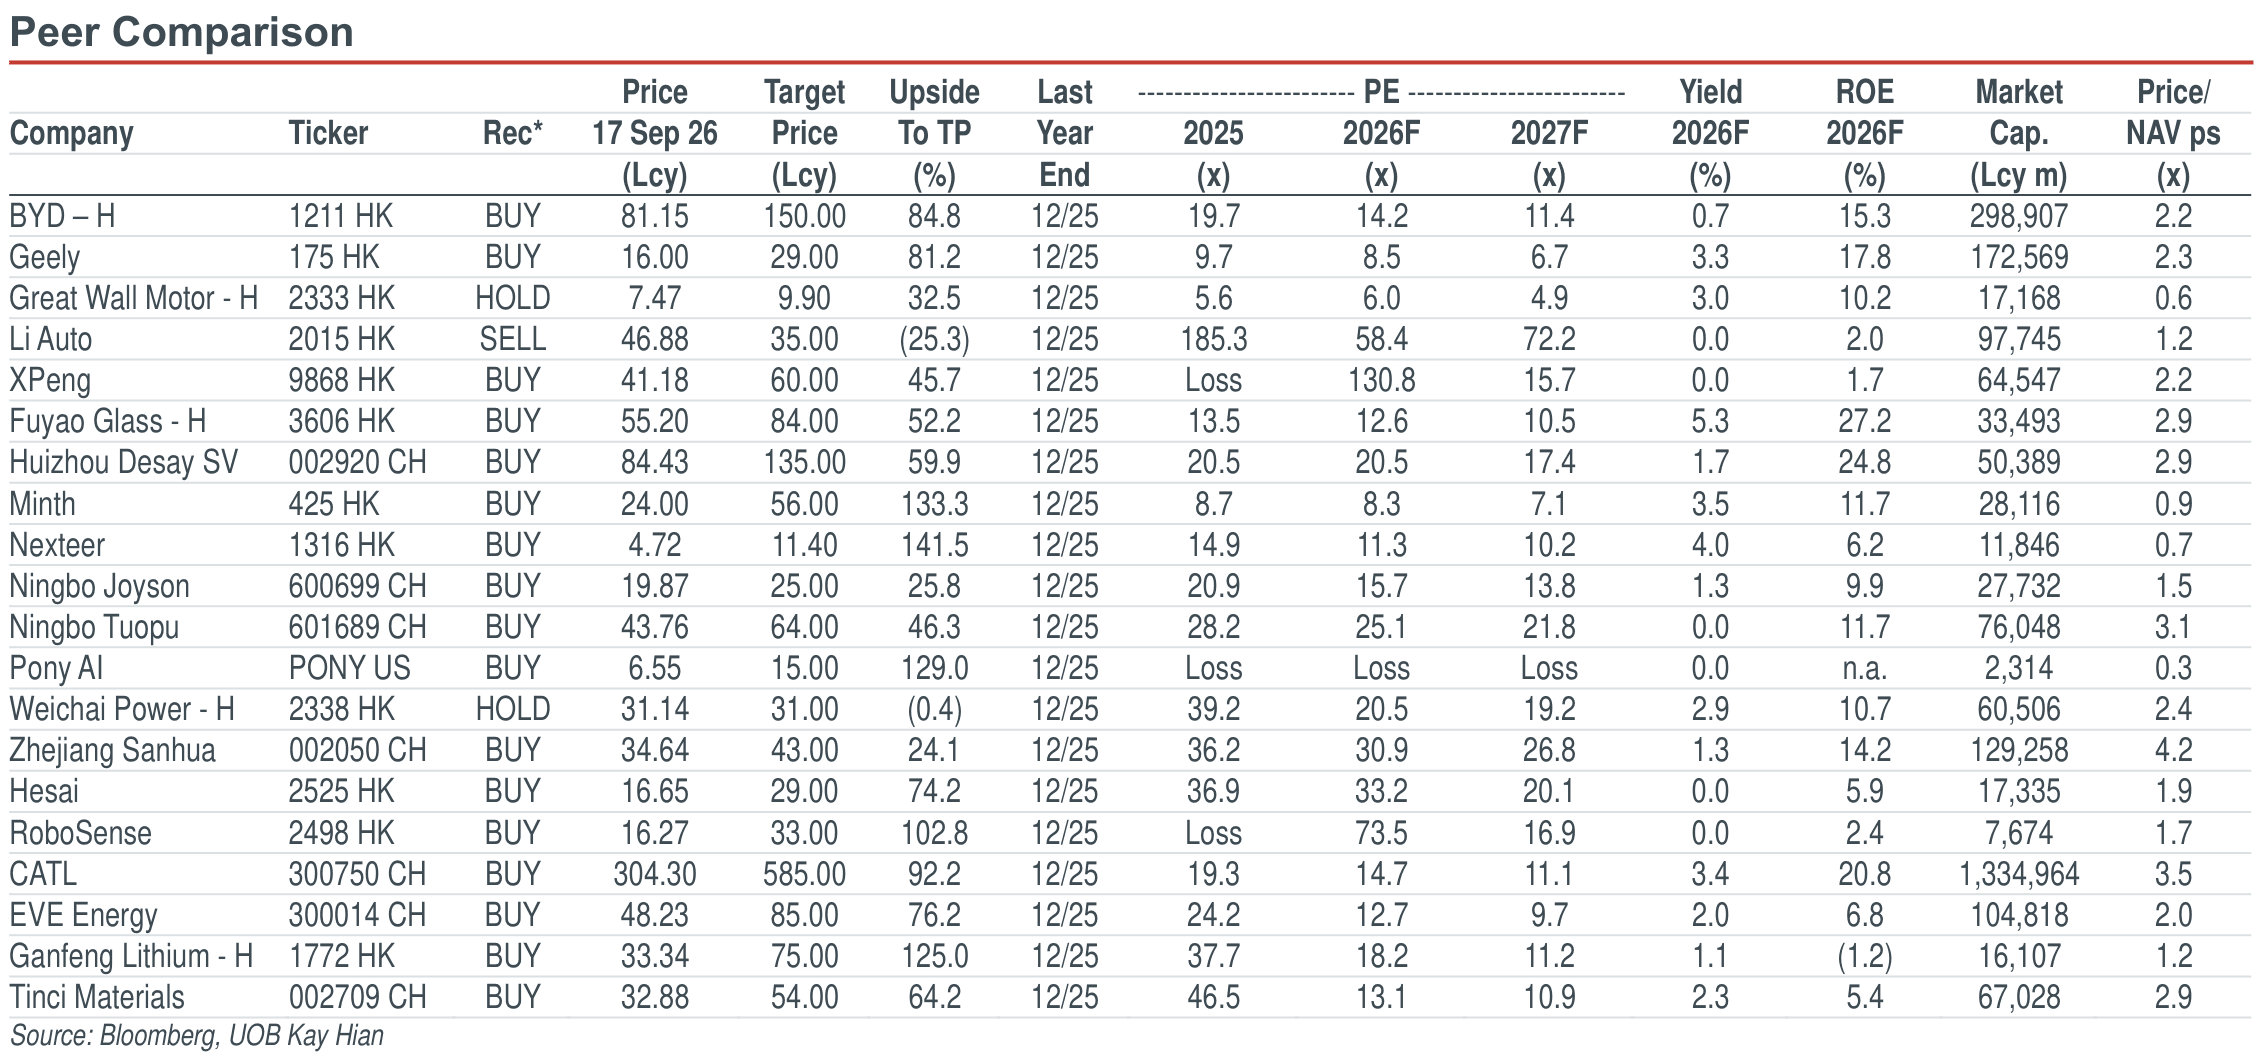
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely, CATL, and Minth. Top SELL: Li Auto.
Analysis
- Battery: Lithium gave back the year's gain while CATL hit a one-year low.
- The most-active Jan 27 futures contract (2701) fell to as low as Rmb124,020/tonne on 16 Sep 26, down more than 20% in September, on reports that the leading cell makers have trimmed production schedules and on Shanghai Metals Market’s (SMM) switch to a broader inventory methodology that raised reported weekly stocks from roughly 70,000 tonnes to 169,300 tonnes in one adjustment, and it has pulled the listed lithium miners down with it. Even after that retreat, battery-grade lithium carbonate spot is still quoted at Rmb128,850-133,200/tonne, leaving the 2701 contract at a Rmb6,380-7,900/tonne discount to physical material. CATL's price-cost linkage passes lithium swings through to the battery price, and the 2% battery consumption tax levied from 1 Sep 26, rising to 4% in Sep 27, falls on the buyer, so neither hit unit profit: we hold CATL's 2026-28 net profit per GWh at Rmb93.6m, Rmb95.6m and Rmb97.8m respectively. The drop in lithium carbonate prices benefit OEMs at the expense of Ganfeng and Tinci. In the 2Q26 results note, we already cut Ganfeng's 2027-28 ASP assumptions to Rmb142,000 per tonne (ex-VAT) and its target price to HK$75.00. The Rmb124,020 per tonne (including 13% VAT) is below our full-year assumption, and the spot-futures gap means the contract is discounting a weaker balance than the physical market has so far confirmed.
- The most-active Jan 27 futures contract (2701) fell to as low as Rmb124,020/tonne on 16 Sep 26, down more than 20% in September, on reports that the leading cell makers have trimmed production schedules and on Shanghai Metals Market’s (SMM) switch to a broader inventory methodology that raised reported weekly stocks from roughly 70,000 tonnes to 169,300 tonnes in one adjustment, and it has pulled the listed lithium miners down with it. Even after that retreat, battery-grade lithium carbonate spot is still quoted at Rmb128,850-133,200/tonne, leaving the 2701 contract at a Rmb6,380-7,900/tonne discount to physical material. CATL's price-cost linkage passes lithium swings through to the battery price, and the 2% battery consumption tax levied from 1 Sep 26, rising to 4% in Sep 27, falls on the buyer, so neither hit unit profit: we hold CATL's 2026-28 net profit per GWh at Rmb93.6m, Rmb95.6m and Rmb97.8m respectively. The drop in lithium carbonate prices benefit OEMs at the expense of Ganfeng and Tinci. In the 2Q26 results note, we already cut Ganfeng's 2027-28 ASP assumptions to Rmb142,000 per tonne (ex-VAT) and its target price to HK$75.00. The Rmb124,020 per tonne (including 13% VAT) is below our full-year assumption, and the spot-futures gap means the contract is discounting a weaker balance than the physical market has so far confirmed.
Highlights
- Lithium carbonate fell more than 20% during September to Rmb124,020/tonne, cutting revenue at Ganfeng and Tinci.
- Geely received more than 43,900 Cruiser 700 pre-orders in an hour, and four September launches are now priced.
- BYD, CATL and Pony AI showed electric trucks at the IAA Hannover, opening a second export front.
- CATL dropped 10.0% to Rmb304.30, a one-year low; we see the switching fear as overdone.
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely, CATL, and Minth. Top SELL: Li Auto.
Analysis
- Battery: Lithium gave back the year's gain while CATL hit a one-year low.
- The most-active Jan 27 futures contract (2701) fell to as low as Rmb124,020/tonne on 16 Sep 26, down more than 20% in September, on reports that the leading cell makers have trimmed production schedules and on Shanghai Metals Market’s (SMM) switch to a broader inventory methodology that raised reported weekly stocks from roughly 70,000 tonnes to 169,300 tonnes in one adjustment, and it has pulled the listed lithium miners down with it. Even after that retreat, battery-grade lithium carbonate spot is still quoted at Rmb128,850-133,200/tonne, leaving the 2701 contract at a Rmb6,380-7,900/tonne discount to physical material. CATL's price-cost linkage passes lithium swings through to the battery price, and the 2% battery consumption tax levied from 1 Sep 26, rising to 4% in Sep 27, falls on the buyer, so neither hit unit profit: we hold CATL's 2026-28 net profit per GWh at Rmb93.6m, Rmb95.6m and Rmb97.8m respectively. The drop in lithium carbonate prices benefit OEMs at the expense of Ganfeng and Tinci. In the 2Q26 results note, we already cut Ganfeng's 2027-28 ASP assumptions to Rmb142,000 per tonne (ex-VAT) and its target price to HK$75.00. The Rmb124,020 per tonne (including 13% VAT) is below our full-year assumption, and the spot-futures gap means the contract is discounting a weaker balance than the physical market has so far confirmed.
- The most-active Jan 27 futures contract (2701) fell to as low as Rmb124,020/tonne on 16 Sep 26, down more than 20% in September, on reports that the leading cell makers have trimmed production schedules and on Shanghai Metals Market’s (SMM) switch to a broader inventory methodology that raised reported weekly stocks from roughly 70,000 tonnes to 169,300 tonnes in one adjustment, and it has pulled the listed lithium miners down with it. Even after that retreat, battery-grade lithium carbonate spot is still quoted at Rmb128,850-133,200/tonne, leaving the 2701 contract at a Rmb6,380-7,900/tonne discount to physical material. CATL's price-cost linkage passes lithium swings through to the battery price, and the 2% battery consumption tax levied from 1 Sep 26, rising to 4% in Sep 27, falls on the buyer, so neither hit unit profit: we hold CATL's 2026-28 net profit per GWh at Rmb93.6m, Rmb95.6m and Rmb97.8m respectively. The drop in lithium carbonate prices benefit OEMs at the expense of Ganfeng and Tinci. In the 2Q26 results note, we already cut Ganfeng's 2027-28 ASP assumptions to Rmb142,000 per tonne (ex-VAT) and its target price to HK$75.00. The Rmb124,020 per tonne (including 13% VAT) is below our full-year assumption, and the spot-futures gap means the contract is discounting a weaker balance than the physical market has so far confirmed.
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

11 Sept 2026
Automobile: Weekly: 60-Day Payment Policy Reinforced; September’s New Model Launch Calendar Busier Than That Of Chengdu Auto Show

4 Sept 2026
Automobile - Weekly: 2Q26 Results Review And 2H26 Outlook

8 Sept 2026
China Property: Shanghai Shifts Housing Supply From New Build To Renewal; National Land Supply Keeps Shrinking
Our latest research

18 Sept 2026
Consumer: China Consumer: Assessing The Impacts Of El Niño

17 Sept 2026
China Healthcare - Bi-Weekly: Strengthening Innovation To Sustain Growth

17 Sept 2026