

Periodic/Sector reports
Banking: Benefitting From Higher For Longer Bond Yields And Interest Rates
MARKET WEIGHT (Upgraded)
Analyst
Highlights
- MAS expects core inflation to remain elevated till 1H27 and has increased the rate of appreciation of the S$NEER policy band. Money supply M2 has slowed to a growth of 2.7% yoy in Jul 26, reflecting MAS’ tightening bias. Assuming the current pace of rise at 5bp/month is maintained, we estimate three-month compounded SORA would reach 1.4% by end-26.
- OCBC was more sensitive to rate hikes with NIM improving 20bp for every 100bp increase in 3M SORA during the last interest rate cycle (up-cycle: 2022-23 and down-cycle: 2024-25), compared with a smaller 15bp for DBS. We raise 2027 earnings forecasts for DBS by 5.7% and OCBC by 4.7% due to NIM expansion of 11bp and 12bp respectively.
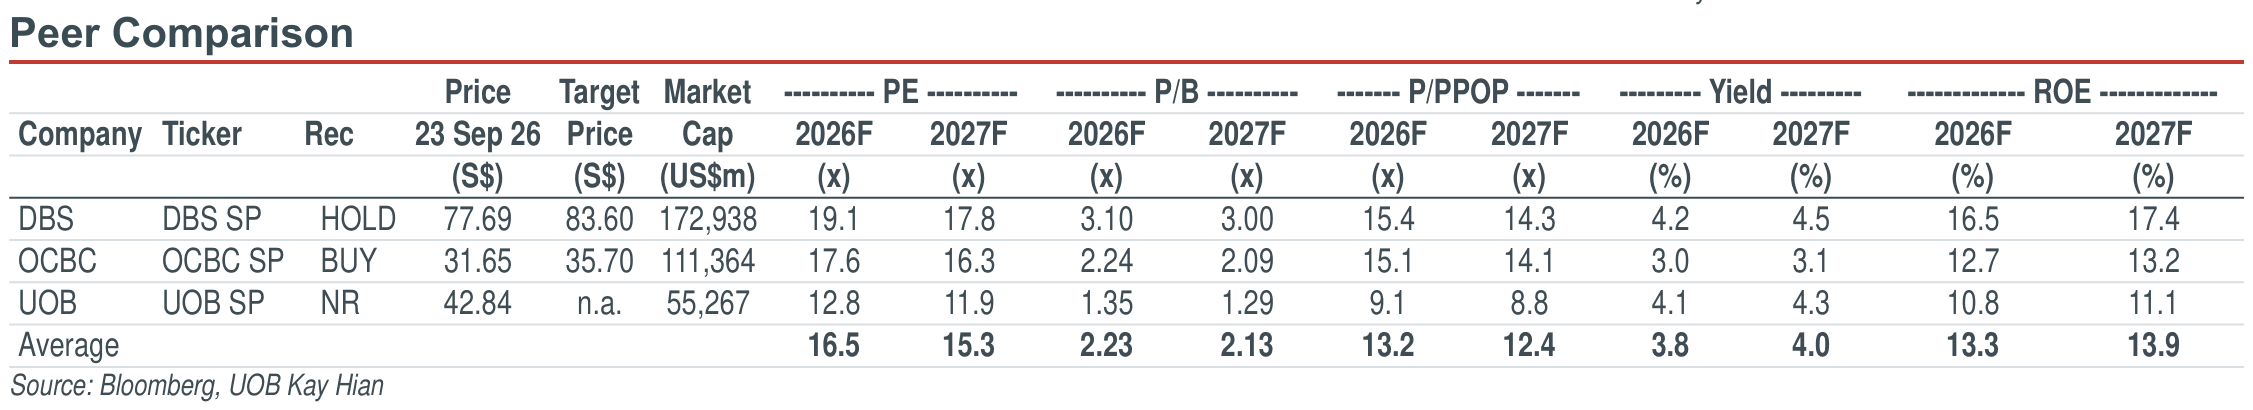
- Upgrade to MARKET WEIGHT. We upgrade OCBC to BUY (Target: S$35.70) for its diversified growth from wealth management (63% of its fee income), trading income and insurance. We also upgrade DBS to HOLD (Target: S$83.60) but its valuation is stretched with 2027F P/B at 3.0x.
Analysis
- MAS switches focus to fighting elevated inflation. The Monetary Authority of Singapore (MAS) increased the rate of appreciation of the SGD Nominal Effective Exchange Rate (S$NEER) policy band slightly in Jul 26, despite having already done so in Apr 26. It expects imported costs to rise in the upcoming quarters. Higher fuel and electronic input costs will lift prices for upstream and intermediate items, such as construction materials, capital equipment and food commodities. Adverse weather conditions are expected to drive up food prices. MAS core Inflation is forecast to step up and remain elevated into 1H27.
- The Fed has finally acted. Fed chairman Kevin Warsh sees the US economy firing on all cylinders with robust hiring, business capital investment and private sector earnings. The labour market is literally at full employment, but inflation has been above the target of 2% for more than five years. Thus, the FOMC hiked the Fed Funds Rate by 25bp to 3.75% on 16 Sep 26 to ensure inflationary pressures do not broaden and to facilitate a timely return to price stability. This is the first hike under the helm of the new chairman after a pause for two consecutive FOMC meetings. Based on the dot plot as of Sep 26, the median projected path for the Fed Funds Rate is 4.1% by end-26, indicating one more hike of 25bp, either during October or December.
- Situation in the Middle East remains dicey. The Houthi rebels have seized Mokha, Dhubab, Perim Island and Hanish islands, which strengthened their grip on the Bab el-Mandeb Strait, a critical chokepoint for maritime traffic traversing through Suez Canal and the Red Sea. These gains could expose tankers to greater risk of attack, raise freight and insurance costs, and disrupt deliveries to Asian customers, particularly as restrictions at Hormuz have increased Saudi Arabia’s dependence on its Red Sea export route. The potential disruption could constrain Saudi’s export volume, delay deliveries and put upward pressure on global crude oil prices.
Highlights
- MAS expects core inflation to remain elevated till 1H27 and has increased the rate of appreciation of the S$NEER policy band. Money supply M2 has slowed to a growth of 2.7% yoy in Jul 26, reflecting MAS’ tightening bias. Assuming the current pace of rise at 5bp/month is maintained, we estimate three-month compounded SORA would reach 1.4% by end-26.
- OCBC was more sensitive to rate hikes with NIM improving 20bp for every 100bp increase in 3M SORA during the last interest rate cycle (up-cycle: 2022-23 and down-cycle: 2024-25), compared with a smaller 15bp for DBS. We raise 2027 earnings forecasts for DBS by 5.7% and OCBC by 4.7% due to NIM expansion of 11bp and 12bp respectively.
- Upgrade to MARKET WEIGHT. We upgrade OCBC to BUY (Target: S$35.70) for its diversified growth from wealth management (63% of its fee income), trading income and insurance. We also upgrade DBS to HOLD (Target: S$83.60) but its valuation is stretched with 2027F P/B at 3.0x.
Analysis
- MAS switches focus to fighting elevated inflation. The Monetary Authority of Singapore (MAS) increased the rate of appreciation of the SGD Nominal Effective Exchange Rate (S$NEER) policy band slightly in Jul 26, despite having already done so in Apr 26. It expects imported costs to rise in the upcoming quarters. Higher fuel and electronic input costs will lift prices for upstream and intermediate items, such as construction materials, capital equipment and food commodities. Adverse weather conditions are expected to drive up food prices. MAS core Inflation is forecast to step up and remain elevated into 1H27.
- The Fed has finally acted. Fed chairman Kevin Warsh sees the US economy firing on all cylinders with robust hiring, business capital investment and private sector earnings. The labour market is literally at full employment, but inflation has been above the target of 2% for more than five years. Thus, the FOMC hiked the Fed Funds Rate by 25bp to 3.75% on 16 Sep 26 to ensure inflationary pressures do not broaden and to facilitate a timely return to price stability. This is the first hike under the helm of the new chairman after a pause for two consecutive FOMC meetings. Based on the dot plot as of Sep 26, the median projected path for the Fed Funds Rate is 4.1% by end-26, indicating one more hike of 25bp, either during October or December.
- Situation in the Middle East remains dicey. The Houthi rebels have seized Mokha, Dhubab, Perim Island and Hanish islands, which strengthened their grip on the Bab el-Mandeb Strait, a critical chokepoint for maritime traffic traversing through Suez Canal and the Red Sea. These gains could expose tankers to greater risk of attack, raise freight and insurance costs, and disrupt deliveries to Asian customers, particularly as restrictions at Hormuz have increased Saudi Arabia’s dependence on its Red Sea export route. The potential disruption could constrain Saudi’s export volume, delay deliveries and put upward pressure on global crude oil prices.
MARKET WEIGHT (Upgraded)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Our latest research

24 Sept 2026
China Property: Faster Mortgage Contraction Raises The Odds Of A National Rate Subsidy; Maintain UNDERWEIGHT

23 Sept 2026
