

Company Coverage
WHA Corporation (WHA TB): Stronger Land Sales And Transfers In 2H26; DCs Remain The Key To 3–5 Year Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Bt4.78
Bt6.10
27.61%
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
- The tone during WHA’s session at our Asian Gems Conference was neutral with no major changes to its overall outlook.
- Resilient DC demand provides an additional long-term growth opportunity as regulations become clearer.
- Maintain BUY with an unchanged target price of Bt6.10.
Analysis
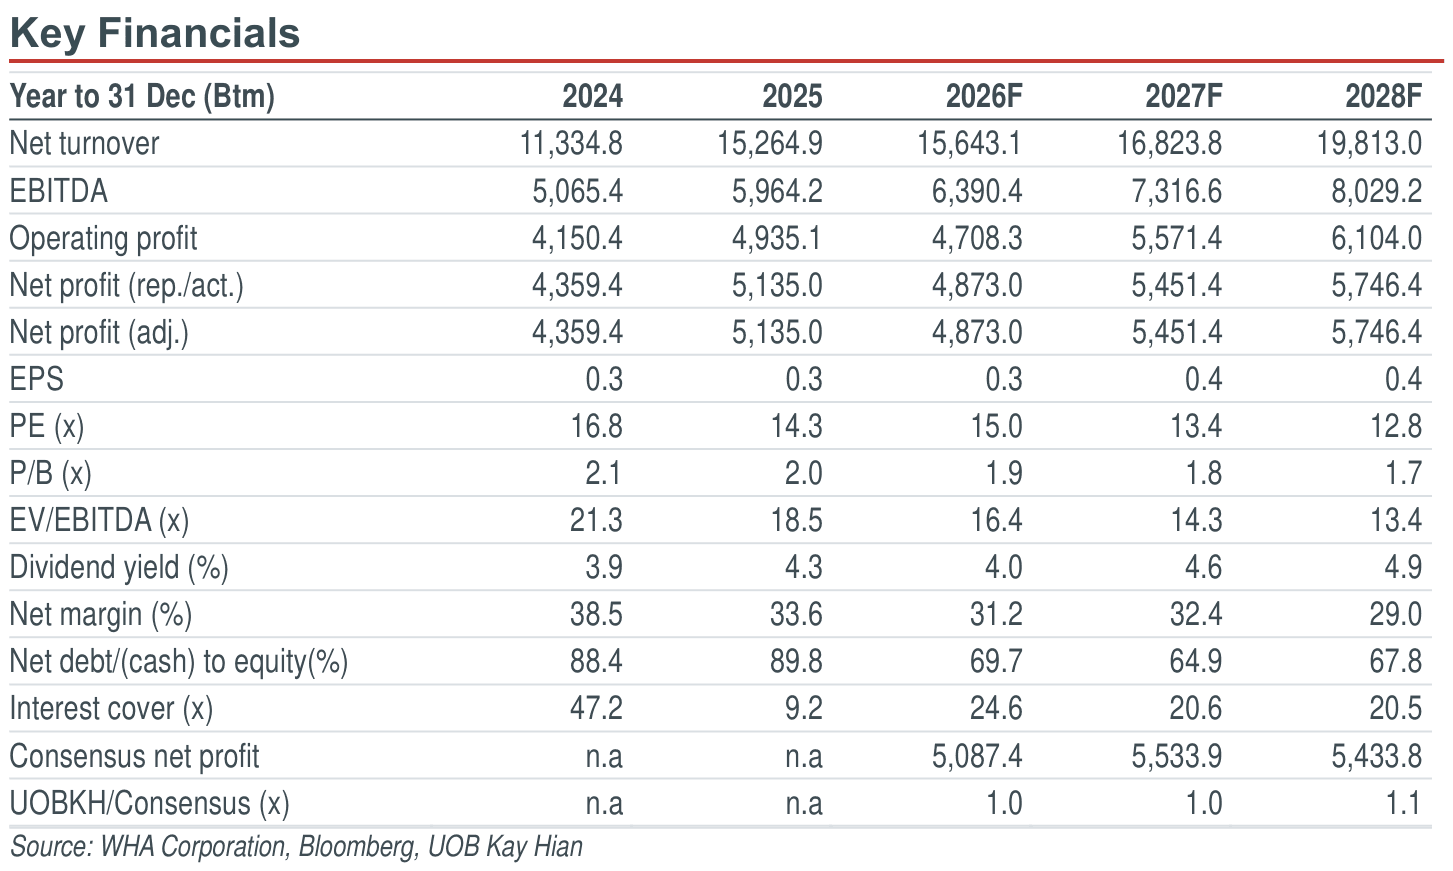
- No changes to overall outlook. We attended WHA Corporation’s (WHA) session at our Asian Gems Conference. The tone was neutral, with no major changes to its overall outlook. Management remained confident in achieving its 2026 land-sales target and highlighted data centres (DC), semiconductors and advanced electronics as key longer-term growth opportunities.
- Land sales to accelerate in 4Q26, with land transfers concentrated in 2H26. Management remains confident in achieving its 2,500-rai land-sales target for 2026, with 1,199 rai already sold in 1H26. Management expects 4Q26’s land sales to exceed that of 3Q26, supported by several deals under negotiation. In terms of transfers, 505 rai was completed in 1H26, but management expects a stronger 2H26 as more than 1,400 rai of backlog is scheduled for transfer. We see this as supportive of a meaningful pickup in industrial estate earnings in 2H26, particularly toward year-end.
- DCs remain intact with regulations being the key to near-term outlook. Management has not seen customers putting DC deals on hold, although some are taking a wait-and-see approach ahead of new regulations that are expected to be announced within the next 4-6 weeks. Management believes the regulations should be neutral/positive for WHA, particularly if stricter zoning, safety and environmental requirements encourage DC projects to locate in industrial estates. WHA is also exploring a dedicated DC industrial park, where centralised water, power and other infrastructure could create economies of scale. We see this as a potential new growth opportunity if DC regulations become more supportive of industrial estate locations. Beyond DCs, management sees semiconductors as the next structural growth opportunity, while demand from automotive, consumer products and electrical appliances should continue to grow.
Highlights
- The tone during WHA’s session at our Asian Gems Conference was neutral with no major changes to its overall outlook.
- Resilient DC demand provides an additional long-term growth opportunity as regulations become clearer.
- Maintain BUY with an unchanged target price of Bt6.10.
Analysis
- No changes to overall outlook. We attended WHA Corporation’s (WHA) session at our Asian Gems Conference. The tone was neutral, with no major changes to its overall outlook. Management remained confident in achieving its 2026 land-sales target and highlighted data centres (DC), semiconductors and advanced electronics as key longer-term growth opportunities.
- Land sales to accelerate in 4Q26, with land transfers concentrated in 2H26. Management remains confident in achieving its 2,500-rai land-sales target for 2026, with 1,199 rai already sold in 1H26. Management expects 4Q26’s land sales to exceed that of 3Q26, supported by several deals under negotiation. In terms of transfers, 505 rai was completed in 1H26, but management expects a stronger 2H26 as more than 1,400 rai of backlog is scheduled for transfer. We see this as supportive of a meaningful pickup in industrial estate earnings in 2H26, particularly toward year-end.
- DCs remain intact with regulations being the key to near-term outlook. Management has not seen customers putting DC deals on hold, although some are taking a wait-and-see approach ahead of new regulations that are expected to be announced within the next 4-6 weeks. Management believes the regulations should be neutral/positive for WHA, particularly if stricter zoning, safety and environmental requirements encourage DC projects to locate in industrial estates. WHA is also exploring a dedicated DC industrial park, where centralised water, power and other infrastructure could create economies of scale. We see this as a potential new growth opportunity if DC regulations become more supportive of industrial estate locations. Beyond DCs, management sees semiconductors as the next structural growth opportunity, while demand from automotive, consumer products and electrical appliances should continue to grow.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt4.78
Bt6.10
27.61%
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

