

Company Coverage
NAURA Technology Group (002371 CH): Broadening Equipment Coverage Amid Memory-driven Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Rmb668.15
Rmb930.00
39.2%
Analyst
Analyst
Highlights
- Strong memory demand and NAURA’s established presence at CXMT and YMTC should support a stronger 2027 as robust 2026 orders convert into revenue.
- Localisation remains a multi-year structural growth driver, with advanced logic offering the longest runway given its relatively low 20-30% domestic-equipment penetration.
- Broader FEOL and advanced-packaging portfolios should expand NAURA’s addressable market beyond its current coverage of about 65% of fab capex.
- Maintain BUY with a target price of Rmb930.00.
Analysis
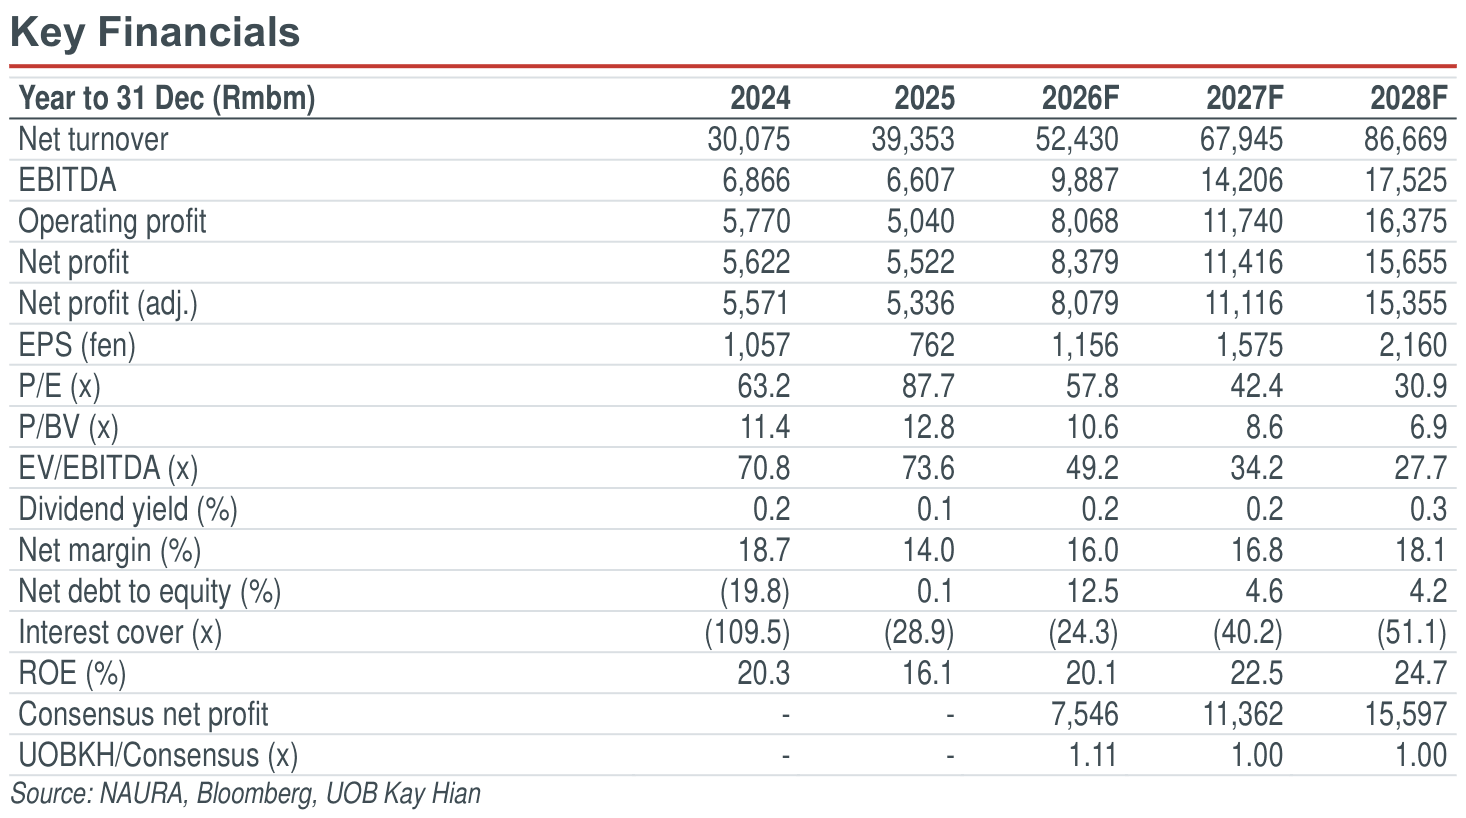
- 2027 financial performance should be more fruitful than 2026’s. NAURA Technology Group’s (NAURA) orders grew 40-50% yoy in 1H26, and management remains optimistic on full-year orders, with memory orders potentially more than doubling and advanced-logic orders growing approximately 30-40% in 2026. Given a one-year order-to-revenue conversion cycle, much of the orders should be recognised as revenue in 2027. Management expects memory order growth to continue outpacing advanced logic in 2027, positioning NAURA to benefit from its established presence at domestic memory manufacturers CXMT and YMTC, where it accounts for more than 50% and approximately one-third of domestically sourced equipment purchases, respectively.
- Localisation provides a multi-year structural growth driver, with advanced logic offering the longest runway. Management expects more than 50% of semiconductor equipment used in China to be domestically supplied by 2030, vs an estimated industry-wide localisation rate of about 30% currently. Localisation remains lowest in advanced logic at 20-30%, compared with 30-40% for mature nodes and about 50% for memory, partly because domestic advanced-logic processes and yields remain immature. Fabs therefore continue to prioritise imported equipment where available and generally adopt domestic alternatives only when imports are restricted. However, wider adoption could be supported by improvements in domestic equipment, with management claiming that NAURA’s same-generation tools at DUV-accessible nodes offer comparable performance and uptime at a lower cost.
Highlights
- Strong memory demand and NAURA’s established presence at CXMT and YMTC should support a stronger 2027 as robust 2026 orders convert into revenue.
- Localisation remains a multi-year structural growth driver, with advanced logic offering the longest runway given its relatively low 20-30% domestic-equipment penetration.
- Broader FEOL and advanced-packaging portfolios should expand NAURA’s addressable market beyond its current coverage of about 65% of fab capex.
- Maintain BUY with a target price of Rmb930.00.
Analysis
- 2027 financial performance should be more fruitful than 2026’s. NAURA Technology Group’s (NAURA) orders grew 40-50% yoy in 1H26, and management remains optimistic on full-year orders, with memory orders potentially more than doubling and advanced-logic orders growing approximately 30-40% in 2026. Given a one-year order-to-revenue conversion cycle, much of the orders should be recognised as revenue in 2027. Management expects memory order growth to continue outpacing advanced logic in 2027, positioning NAURA to benefit from its established presence at domestic memory manufacturers CXMT and YMTC, where it accounts for more than 50% and approximately one-third of domestically sourced equipment purchases, respectively.
- Localisation provides a multi-year structural growth driver, with advanced logic offering the longest runway. Management expects more than 50% of semiconductor equipment used in China to be domestically supplied by 2030, vs an estimated industry-wide localisation rate of about 30% currently. Localisation remains lowest in advanced logic at 20-30%, compared with 30-40% for mature nodes and about 50% for memory, partly because domestic advanced-logic processes and yields remain immature. Fabs therefore continue to prioritise imported equipment where available and generally adopt domestic alternatives only when imports are restricted. However, wider adoption could be supported by improvements in domestic equipment, with management claiming that NAURA’s same-generation tools at DUV-accessible nodes offer comparable performance and uptime at a lower cost.
BUY (Maintained)
Current price:
Target price:
Upside:
Rmb668.15
Rmb930.00
39.2%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Sept 2026
The United Laboratories International (3933 HK): 1H26: Miss on Licence Lapse; Growth To Resume In 2H26

31 Aug 2026
Miniso (MNSO US/9896 HK): 1H26: Revenue Slightly Exceeds Guidance But Profit Misses; Expect Operating Profit To Decline By A High Single Digit In 2026

28 Aug 2026
Inner Mongolia Yili Industrial Group (600887 CH): 2Q26: Revenue Misses But Operating Margin Expansion Better Than Expected; Reiterates Mid-Single-Digit Revenue Growth Target
Our latest research

24 Sept 2026
Hangzhou Hikvision Digital Technology (002415 CH): From Memory-driven Recovery to AIoT-led Volume Growth
24 Sept 2026
TA: Nongfu Spring (9633 HK) / Huishang Bank (3698 HK)
23 Sept 2026