

Company Coverage
Hangzhou Hikvision Digital Technology (002415 CH): From Memory-driven Recovery to AIoT-led Volume Growth
NOT RATED
Current price:
Target price:
Upside:
Rmb33.11
n.a.
n.a.
Analyst
Analyst
Highlights
- Memory inflation and effective cost pass-through have offset declining shipment volumes, supporting core-business growth and lifting gross margin in the near term.
- As memory inflation subsides, growth should shift from pricing to volume, supported by improving AIoT economics, broader adoption and a potential equipment replacement cycle from 2028.
- Hikvision’s competitive moat is built on its operating ecosystem, where customer relationships, industry data and product deployment drive continuous innovation.
Analysis
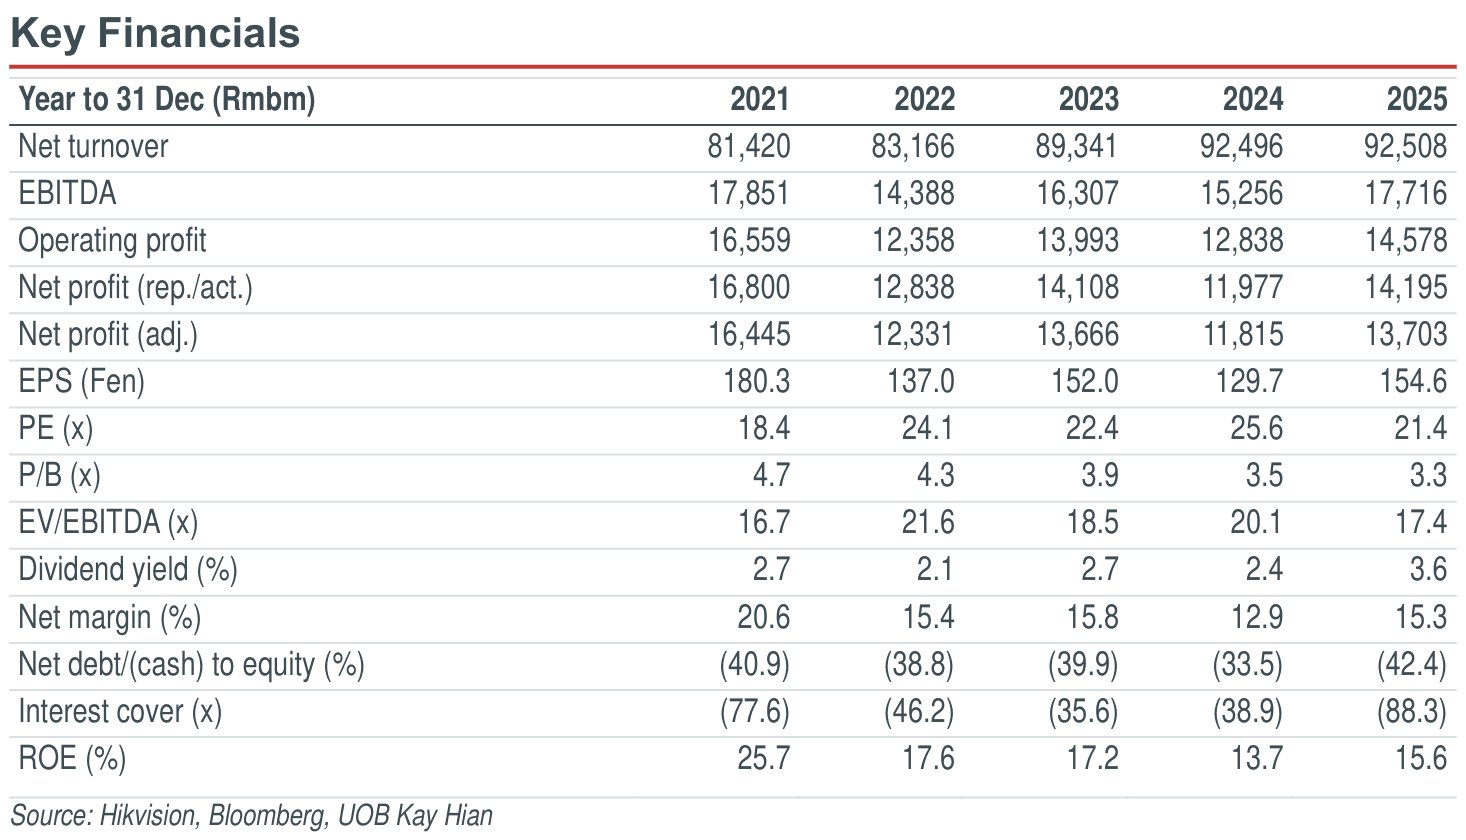
- Core business has returned to growth, while effective cost pass-through is driving an earnings recovery. Hangzhou Hikvision Digital Technology’s (Hikvision) domestic core business grew 5% yoy in 1H26 after four consecutive years of weak performance, which management deems as evidence that the business has passed its trough. Meanwhile, AI-driven DRAM shortages have allowed Hikvision to raise ASPs faster than memory costs, offsetting declining shipment volumes and lifting gross margin to a record 50% in 1H26. Management expects memory tightness to persist through 2027 and targets 2026 revenue of above Rmb100b and record-high profit.
- Growth should gradually transition from pricing-led to volume-led. As memory supply normalises, ASPs should ease and weigh on gross margin, although management expects gross margin to remain within a normalised range of 45-47%. Lower memory costs and more capable edge chips could make AI-enabled sensing products more attractive to customers, supporting broader adoption and higher shipment volumes. Management also believes an equipment replacement cycle could emerge around 2028 as ageing surveillance products reach end-of-life, providing an additional volume driver when the current pricing tailwind fades.
- Capital returns remain attractive. Management intends to maintain a dividend payout ratio above 70% and believes this level can be sustained for some time. Since listing in 2009, Hikvision has returned Rmb84.5b to shareholders, comprising Rmb80.4b in cash dividends and Rmb4.1b in share buybacks.
Highlights
- Memory inflation and effective cost pass-through have offset declining shipment volumes, supporting core-business growth and lifting gross margin in the near term.
- As memory inflation subsides, growth should shift from pricing to volume, supported by improving AIoT economics, broader adoption and a potential equipment replacement cycle from 2028.
- Hikvision’s competitive moat is built on its operating ecosystem, where customer relationships, industry data and product deployment drive continuous innovation.
Analysis
- Core business has returned to growth, while effective cost pass-through is driving an earnings recovery. Hangzhou Hikvision Digital Technology’s (Hikvision) domestic core business grew 5% yoy in 1H26 after four consecutive years of weak performance, which management deems as evidence that the business has passed its trough. Meanwhile, AI-driven DRAM shortages have allowed Hikvision to raise ASPs faster than memory costs, offsetting declining shipment volumes and lifting gross margin to a record 50% in 1H26. Management expects memory tightness to persist through 2027 and targets 2026 revenue of above Rmb100b and record-high profit.
- Growth should gradually transition from pricing-led to volume-led. As memory supply normalises, ASPs should ease and weigh on gross margin, although management expects gross margin to remain within a normalised range of 45-47%. Lower memory costs and more capable edge chips could make AI-enabled sensing products more attractive to customers, supporting broader adoption and higher shipment volumes. Management also believes an equipment replacement cycle could emerge around 2028 as ageing surveillance products reach end-of-life, providing an additional volume driver when the current pricing tailwind fades.
- Capital returns remain attractive. Management intends to maintain a dividend payout ratio above 70% and believes this level can be sustained for some time. Since listing in 2009, Hikvision has returned Rmb84.5b to shareholders, comprising Rmb80.4b in cash dividends and Rmb4.1b in share buybacks.
NOT RATED
Current price:
Target price:
Upside:
Rmb33.11
n.a.
n.a.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

1 Sept 2026
Medlive Technology Co (2192 HK): 1H26: Softer Top-line Growth On Compliance Reset; Core Earnings Remain Resilient

1 Sept 2026
Inovance Technology (300124 CH): 2Q26: Results In Line, Recovery To Sustain Through 2027

28 Aug 2026
