

Company Coverage
Tisco Financial Group (TISCO TB) - 3Q26 Results Preview: Expect Credit Costs To Continue To Decline
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt125.00
Bt120.00
-4.0%
Analyst
Highlights
- We expect TISCO to report a net profit of Bt1.78b, up 3% yoy and 1% qoq.
- The bank guided that the current management overlay should be adequate.
- Maintain HOLD with an unchanged target price of Bt120.00.
Analysis
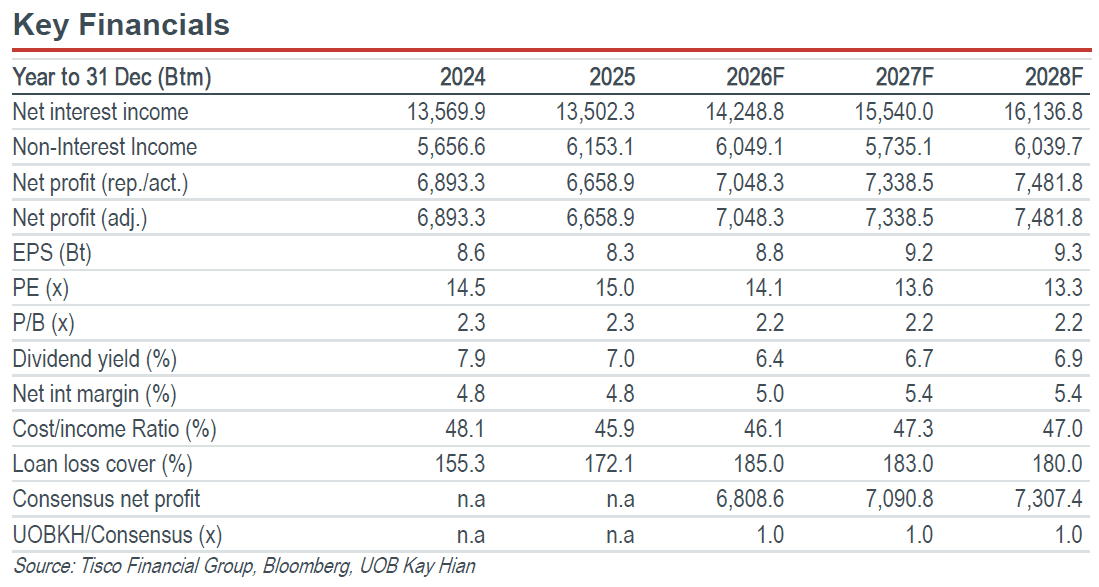
- Expect 3Q26 net profit to increase yoy and qoq. We expect Tisco Financial Group (TISCO) to report a 3Q26 net profit of Bt1.78b, up 3% yoy and 1% qoq. Excluding provisioning, pre-provision operating profit is expected to decrease 11% yoy and 3% qoq.
- Loan portfolio grew both yoy and mom in Aug 26. According to the recent monthly loan report published on 11 Sep 26, TISCO reported a loan portfolio of Bt229b in Aug 26, up 0.6% yoy and 0.3% mom. Overall, the loan portfolio grew 0.3% ytd (as of end-Aug 26). TISCO will report its next monthly loan portfolio figure in mid-Oct 26.
- Expect loans to expand yoy in 3Q26… We expect TISCO’s loan portfolio to grow 2% yoy and flat qoq to around Bt235b in 3Q26. We expect the loan portfolio to grow 1.5% in 2026, compared with the bank’s loan growth target of 0-5%. The bank guided that it would focus on expanding loan portfolio in the retail segment, especially hire-purchase new cars.
- …and credit costs to decline qoq in the same quarter. TISCO reported credit costs of 113bp in 1H26, including special provisioning in 1Q26. Meanwhile, the bank has set a 2026 credit cost target of 100-110bp. Therefore, we expect to see a reduction in credit costs in 2H26. We foresee a continuous reduction in credit costs quarter by quarter toward the end of 2026. As a result, we expect 3Q26 credit costs to decrease by 20bp qoq to 74bp, while our 2026 forecast of 91bp stands below the company's targeted range of 100-110bp. We are positive on TISCO's asset quality outlook.
- Current management overlay should be adequate. Management guided that, in the absence of new negative surprises, the existing management overlay should be sufficient to absorb potential deterioration in loan portfolio quality. Management guided that the bank maintains a prudent credit policy due to the volatile situation. The current coverage ratio is adequate for buffering against uncertainties.
Highlights
- We expect TISCO to report a net profit of Bt1.78b, up 3% yoy and 1% qoq.
- The bank guided that the current management overlay should be adequate.
- Maintain HOLD with an unchanged target price of Bt120.00.
Analysis
- Expect 3Q26 net profit to increase yoy and qoq. We expect Tisco Financial Group (TISCO) to report a 3Q26 net profit of Bt1.78b, up 3% yoy and 1% qoq. Excluding provisioning, pre-provision operating profit is expected to decrease 11% yoy and 3% qoq.
- Loan portfolio grew both yoy and mom in Aug 26. According to the recent monthly loan report published on 11 Sep 26, TISCO reported a loan portfolio of Bt229b in Aug 26, up 0.6% yoy and 0.3% mom. Overall, the loan portfolio grew 0.3% ytd (as of end-Aug 26). TISCO will report its next monthly loan portfolio figure in mid-Oct 26.
- Expect loans to expand yoy in 3Q26… We expect TISCO’s loan portfolio to grow 2% yoy and flat qoq to around Bt235b in 3Q26. We expect the loan portfolio to grow 1.5% in 2026, compared with the bank’s loan growth target of 0-5%. The bank guided that it would focus on expanding loan portfolio in the retail segment, especially hire-purchase new cars.
- …and credit costs to decline qoq in the same quarter. TISCO reported credit costs of 113bp in 1H26, including special provisioning in 1Q26. Meanwhile, the bank has set a 2026 credit cost target of 100-110bp. Therefore, we expect to see a reduction in credit costs in 2H26. We foresee a continuous reduction in credit costs quarter by quarter toward the end of 2026. As a result, we expect 3Q26 credit costs to decrease by 20bp qoq to 74bp, while our 2026 forecast of 91bp stands below the company's targeted range of 100-110bp. We are positive on TISCO's asset quality outlook.
- Current management overlay should be adequate. Management guided that, in the absence of new negative surprises, the existing management overlay should be sufficient to absorb potential deterioration in loan portfolio quality. Management guided that the bank maintains a prudent credit policy due to the volatile situation. The current coverage ratio is adequate for buffering against uncertainties.
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt125.00
Bt120.00
-4.0%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
