

Company Coverage
Krungthai Card (KTC TB) - 3Q26 Results Preview: Expect Loans To Grow yoy And qoq
BUY (Maintained)
Current price:
Target price:
Upside:
Bt37.00
Bt50.00
+35.1%
Analyst
Highlights
- We expect 3Q26 net profit to come in at Bt2.1b, up 9% yoy but down 5% qoq.
- Credit costs are expected to rise qoq in 3Q26.
- Maintain BUY with a target price of Bt50.00.
Analysis
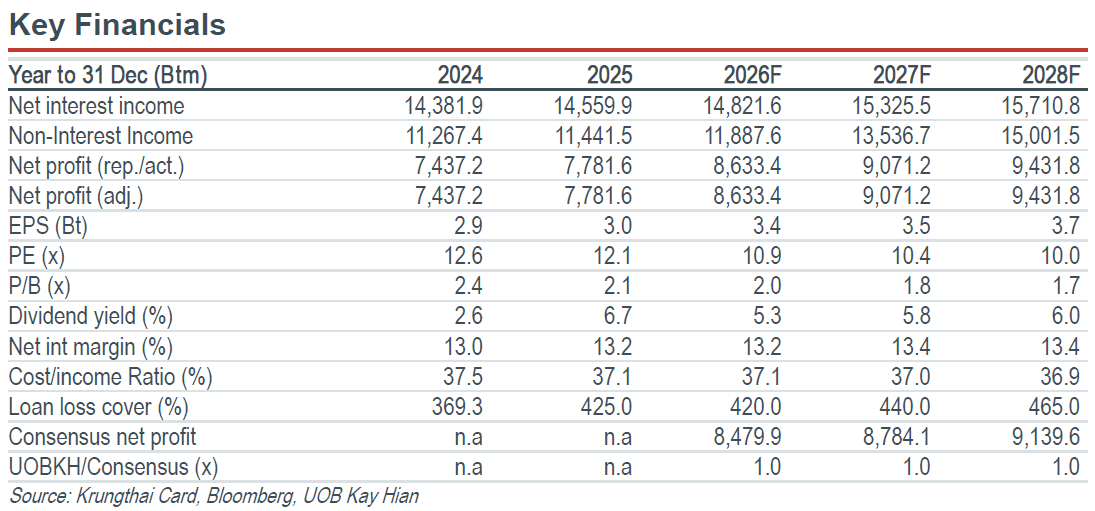
- Expect 3Q26 earnings to rise yoy. We expect Krungthai Card (KTC) to report a 3Q26 net profit of Bt2.1b, up 9% yoy but down 5% qoq. We expect pre-provision operating income to rise by 4% yoy and 1% qoq.
- Strong growth in industry’s credit card loans outstanding. As of Jul 26, the industry’s credit card loans outstanding had decreased by 6% from Dec 25. This reduction was due to the high base from the seasonal peak in Dec 25. However, the industry’s credit card loan outstanding increased by 1% yoy to Bt480b in Jul 26. We expect an improvement in both credit card spending and loan outstanding for KTC in 2H26.
- Anticipate loan portfolio expansion in 3Q26. We expect KTC’s loan portfolio to grow by 2% yoy and 1% qoq in 3Q26, in line with our forecast of a 2% yoy growth for 2026. KTC has a loan growth target of 1-2% in 2026. Management admits that the quality of potential clients remains a concern, but the company is also screening and being prudent in lending in order to maintain a good-quality loan portfolio. We believe KTC will maintain its asset quality despite facing more challenges, as it has in the past.
- Forecast credit costs to rise qoq in 3Q26. We expect KTC to report a 69bp qoq increase in credit costs to 559bp in 3Q26 as we believe the company will increase provision expenses to cushion against future uncertainties. We project a slight 1bp yoy decrease in credit costs to 5.33% in 2026. Management believes that the credit cost should be 5.0-5.3% for 2026, based on the current situation. However, the company has not changed its original credit cost target of 5.5% for 2026.
- An acquisition will enhance debt collection. KTC announced the acquisition of ordinary shares of Win Performance Company Limited (WIN), representing 100% of total shares issued of WIN amounting to Bt295m. As a result, WIN will become a subsidiary of KTC. WIN operates a debt collection business, including related legal services and support services. KTC expects this acquisition to support the strategic plan for managing costs and generating revenue through strategic cooperation with WIN. We are positive on this acquisition, as KTC has consistently highlighted the strength of its debt-collection partner, which is WIN. KTC has reported impressive debt collection in the past and does not sell written-off receivables.
Highlights
- We expect 3Q26 net profit to come in at Bt2.1b, up 9% yoy but down 5% qoq.
- Credit costs are expected to rise qoq in 3Q26.
- Maintain BUY with a target price of Bt50.00.
Analysis
- Expect 3Q26 earnings to rise yoy. We expect Krungthai Card (KTC) to report a 3Q26 net profit of Bt2.1b, up 9% yoy but down 5% qoq. We expect pre-provision operating income to rise by 4% yoy and 1% qoq.
- Strong growth in industry’s credit card loans outstanding. As of Jul 26, the industry’s credit card loans outstanding had decreased by 6% from Dec 25. This reduction was due to the high base from the seasonal peak in Dec 25. However, the industry’s credit card loan outstanding increased by 1% yoy to Bt480b in Jul 26. We expect an improvement in both credit card spending and loan outstanding for KTC in 2H26.
- Anticipate loan portfolio expansion in 3Q26. We expect KTC’s loan portfolio to grow by 2% yoy and 1% qoq in 3Q26, in line with our forecast of a 2% yoy growth for 2026. KTC has a loan growth target of 1-2% in 2026. Management admits that the quality of potential clients remains a concern, but the company is also screening and being prudent in lending in order to maintain a good-quality loan portfolio. We believe KTC will maintain its asset quality despite facing more challenges, as it has in the past.
- Forecast credit costs to rise qoq in 3Q26. We expect KTC to report a 69bp qoq increase in credit costs to 559bp in 3Q26 as we believe the company will increase provision expenses to cushion against future uncertainties. We project a slight 1bp yoy decrease in credit costs to 5.33% in 2026. Management believes that the credit cost should be 5.0-5.3% for 2026, based on the current situation. However, the company has not changed its original credit cost target of 5.5% for 2026.
- An acquisition will enhance debt collection. KTC announced the acquisition of ordinary shares of Win Performance Company Limited (WIN), representing 100% of total shares issued of WIN amounting to Bt295m. As a result, WIN will become a subsidiary of KTC. WIN operates a debt collection business, including related legal services and support services. KTC expects this acquisition to support the strategic plan for managing costs and generating revenue through strategic cooperation with WIN. We are positive on this acquisition, as KTC has consistently highlighted the strength of its debt-collection partner, which is WIN. KTC has reported impressive debt collection in the past and does not sell written-off receivables.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt37.00
Bt50.00
+35.1%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

