

Company Coverage
Aeon Thana Sinsap (Thailand) (AEONTS TB): 2QFY27 Results Preview: Earnings To Drop qoq Due To Increase In Credit Costs
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt95.50
Bt120.00
25.7%
Bt125.00
Analyst
Highlights
- AEONTS will announce its 2QFY27 earnings results on 7 Oct 26.
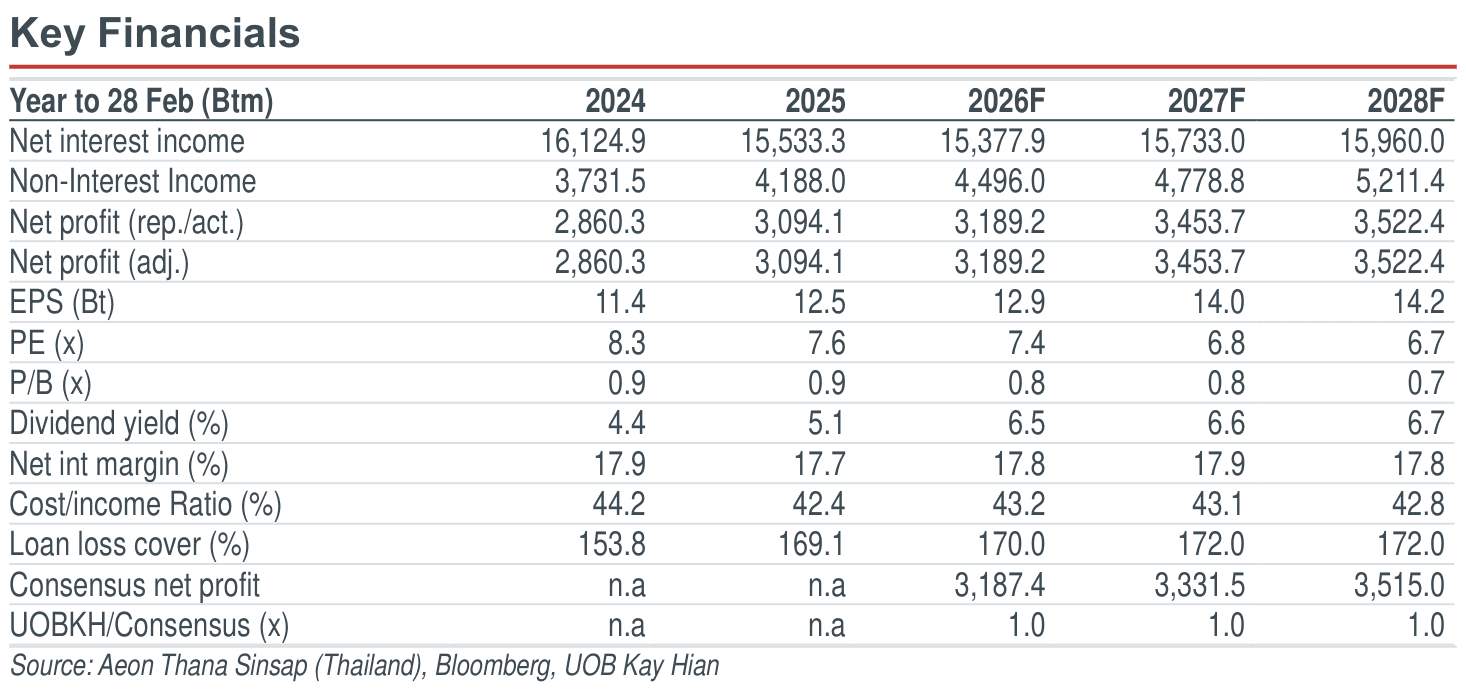
- We expect a 2QFY27 net profit of Bt695m (-12% yoy, -12% qoq).
- Maintain BUY with a lower target price of Bt120.00 (previous: Bt125.00)
Analysis
- Expect 2QFY27 earnings to decrease yoy and qoq. We expect Aeon Thana Sinsap (Thailand) (AEONTS) to report a 2QFY27 net profit of Bt695m, down 12% yoy and 12% qoq. The qoq drop in earnings will be due to the increase in credit cost; however, the company will benefit from the gain on sale of written-off receivables. We foresee the company’s pre-provision operating profit increasing 0.5% yoy and 11% qoq in 2QFY27.
- Expect gains from sale of written-off receivables to be reported in 2QFY27 earnings. AEONTS has reported the gain from the sale of its written-off receivables of Bt193m in 4QFY26. AEONTS has stated that the sale of written-off receivables will occur twice a year; hence, we expect it to take place in 2QFY27. Based on our check with the company, we believe that the gain from the sale of its written-off receivables in 2QFY27 should not exceed Bt150m.
- Hire-purchase in Cambodia may affect AEONTS' asset quality. There are asset quality concerns over hire-purchase (HP) loans in Cambodia. Hence, we should see higher provisioning for this segment. According to our check with the company, we expect there to be a one-time cost for accounting recognition in 2QFY27. The company guided that the HP asset quality problem in Cambodia should be resolved within the next two quarters. However, Cambodian subsidiaries currently continue to be reported under consolidation, although AEONTS has waived its pre-emptive rights to subscribe for newly issued shares of AEON Specialized Bank (Cambodia), resulting in a decrease in its shareholding from 50% to 43.01%.
- Expect credit costs to increase qoq in 2QFY27. We expect AEONTS’ credit cost to increase from 745bp in 1QFY27 to 953bp in 2QFY27. We foresee an increase in NPL ratio from 5.6% in 1QFY27 to 5.7% in 2QFY27 with a 1.4% qoq loan contraction. According to AEONTS, the Thai Help Thai Plus 60/40 only has a small positive impact on the company as the monthly repayment of credit cards and personal loans is quite high at Bt30,000-40,000, compared with the monthly benefit from this measure of only around Bt1,000.
Highlights
- AEONTS will announce its 2QFY27 earnings results on 7 Oct 26.
- We expect a 2QFY27 net profit of Bt695m (-12% yoy, -12% qoq).
- Maintain BUY with a lower target price of Bt120.00 (previous: Bt125.00)
Analysis
- Expect 2QFY27 earnings to decrease yoy and qoq. We expect Aeon Thana Sinsap (Thailand) (AEONTS) to report a 2QFY27 net profit of Bt695m, down 12% yoy and 12% qoq. The qoq drop in earnings will be due to the increase in credit cost; however, the company will benefit from the gain on sale of written-off receivables. We foresee the company’s pre-provision operating profit increasing 0.5% yoy and 11% qoq in 2QFY27.
- Expect gains from sale of written-off receivables to be reported in 2QFY27 earnings. AEONTS has reported the gain from the sale of its written-off receivables of Bt193m in 4QFY26. AEONTS has stated that the sale of written-off receivables will occur twice a year; hence, we expect it to take place in 2QFY27. Based on our check with the company, we believe that the gain from the sale of its written-off receivables in 2QFY27 should not exceed Bt150m.
- Hire-purchase in Cambodia may affect AEONTS' asset quality. There are asset quality concerns over hire-purchase (HP) loans in Cambodia. Hence, we should see higher provisioning for this segment. According to our check with the company, we expect there to be a one-time cost for accounting recognition in 2QFY27. The company guided that the HP asset quality problem in Cambodia should be resolved within the next two quarters. However, Cambodian subsidiaries currently continue to be reported under consolidation, although AEONTS has waived its pre-emptive rights to subscribe for newly issued shares of AEON Specialized Bank (Cambodia), resulting in a decrease in its shareholding from 50% to 43.01%.
- Expect credit costs to increase qoq in 2QFY27. We expect AEONTS’ credit cost to increase from 745bp in 1QFY27 to 953bp in 2QFY27. We foresee an increase in NPL ratio from 5.6% in 1QFY27 to 5.7% in 2QFY27 with a 1.4% qoq loan contraction. According to AEONTS, the Thai Help Thai Plus 60/40 only has a small positive impact on the company as the monthly repayment of credit cards and personal loans is quite high at Bt30,000-40,000, compared with the monthly benefit from this measure of only around Bt1,000.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt95.50
Bt120.00
25.7%
Bt125.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

