

Company Coverage
Wilmar International (WIL SP): Integrated Business Model To Navigate The Challenging Operating Environment
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$3.65
S$3.80
4.1%
S$3.50
Analyst
Highlights
- Wilmar remains cautiously optimistic despite a challenging environment. While the plantation segment may benefit from stronger palm oil and sugar prices, elevated commodity prices could pressure margins across downstream consumer and tropical oils businesses.
- With limited pricing flexibility, Wilmar is prioritising cost efficiency, expanding its value offerings, and leveraging its experienced hedging strategies to navigate commodity price volatility.
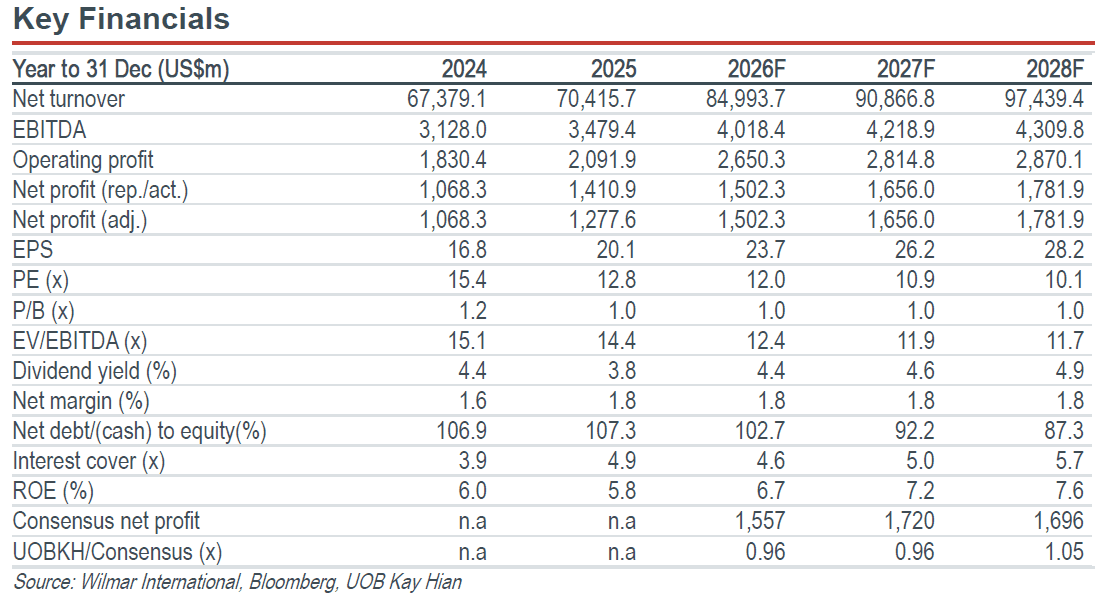
- Maintain HOLD with a higher target price of S$3.80.
Analysis
- Cautiously optimistic outlook amid commodity volatility. Wilmar International (Wilmar) expressed confidence in the group’s integrated business model to navigate the challenging operating environment amid the volatility in commodity prices. While the plantation segment could benefit from higher palm product prices amid El Niño, the group’s earnings remain largely dependent on consumer products and tropical oils, where elevated commodity prices could pressure their input costs.
- Soybean crushing volume remains healthy, but margins likely to soften. China’s soybean crushing activities continued to be supported by sustained robust feed demand from the hog industry. In its Sep 26 report, the United States Department of Agriculture raised its forecast for China’s oilseed crush to 144m tonnes (+0.7m tonnes) in 2026/27, mainly driven by higher soybean crushing. However, rising global soybean oil prices continue to exert pressure on local crushing margins, and Wilmar expects crushing margins to soften in 2H26, although they should remain positive. Its procurement and hedging strategies should provide some cushion against high vegoils prices.
- El Niño impact likely to emerge in 2027. While the group initially guided for an improvement in FFB production in 2H26, the current production rate may suggest some recalibration in its initial target. This follows weaker production in August and September, reversing the positive momentum recorded in June and July. That said, we believe 4Q26 production could be the main swing factor, given the recent shift in production cycle towards year-end, while the group’s reduced fertiliser application could translate into lower operating costs. Wilmar’s estates in Kalimantan have experienced drier conditions in recent months, although management expects the impact of El Niño on FFB production to be felt only next year. Plantation profitability will therefore hinge on whether higher CPO prices can offset lower production.
Highlights
- Wilmar remains cautiously optimistic despite a challenging environment. While the plantation segment may benefit from stronger palm oil and sugar prices, elevated commodity prices could pressure margins across downstream consumer and tropical oils businesses.
- With limited pricing flexibility, Wilmar is prioritising cost efficiency, expanding its value offerings, and leveraging its experienced hedging strategies to navigate commodity price volatility.
- Maintain HOLD with a higher target price of S$3.80.
Analysis
- Cautiously optimistic outlook amid commodity volatility. Wilmar International (Wilmar) expressed confidence in the group’s integrated business model to navigate the challenging operating environment amid the volatility in commodity prices. While the plantation segment could benefit from higher palm product prices amid El Niño, the group’s earnings remain largely dependent on consumer products and tropical oils, where elevated commodity prices could pressure their input costs.
- Soybean crushing volume remains healthy, but margins likely to soften. China’s soybean crushing activities continued to be supported by sustained robust feed demand from the hog industry. In its Sep 26 report, the United States Department of Agriculture raised its forecast for China’s oilseed crush to 144m tonnes (+0.7m tonnes) in 2026/27, mainly driven by higher soybean crushing. However, rising global soybean oil prices continue to exert pressure on local crushing margins, and Wilmar expects crushing margins to soften in 2H26, although they should remain positive. Its procurement and hedging strategies should provide some cushion against high vegoils prices.
- El Niño impact likely to emerge in 2027. While the group initially guided for an improvement in FFB production in 2H26, the current production rate may suggest some recalibration in its initial target. This follows weaker production in August and September, reversing the positive momentum recorded in June and July. That said, we believe 4Q26 production could be the main swing factor, given the recent shift in production cycle towards year-end, while the group’s reduced fertiliser application could translate into lower operating costs. Wilmar’s estates in Kalimantan have experienced drier conditions in recent months, although management expects the impact of El Niño on FFB production to be felt only next year. Plantation profitability will therefore hinge on whether higher CPO prices can offset lower production.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$3.65
S$3.80
4.1%
S$3.50
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

