

Company Coverage
Sunway Construction (SCGB MK): Retracement Offers Opportunities; Upgrade To BUY
BUY (Upgraded)
Current price:
Target price:
Upside:
RM7.57
RM8.44
11.5%
Analyst
Analyst
Highlights
- Suncon has achieved a record-high orderbook of RM10.5b. We remain confident that the group will achieve its orderbook replenishment of RM7b-9b in 2026.
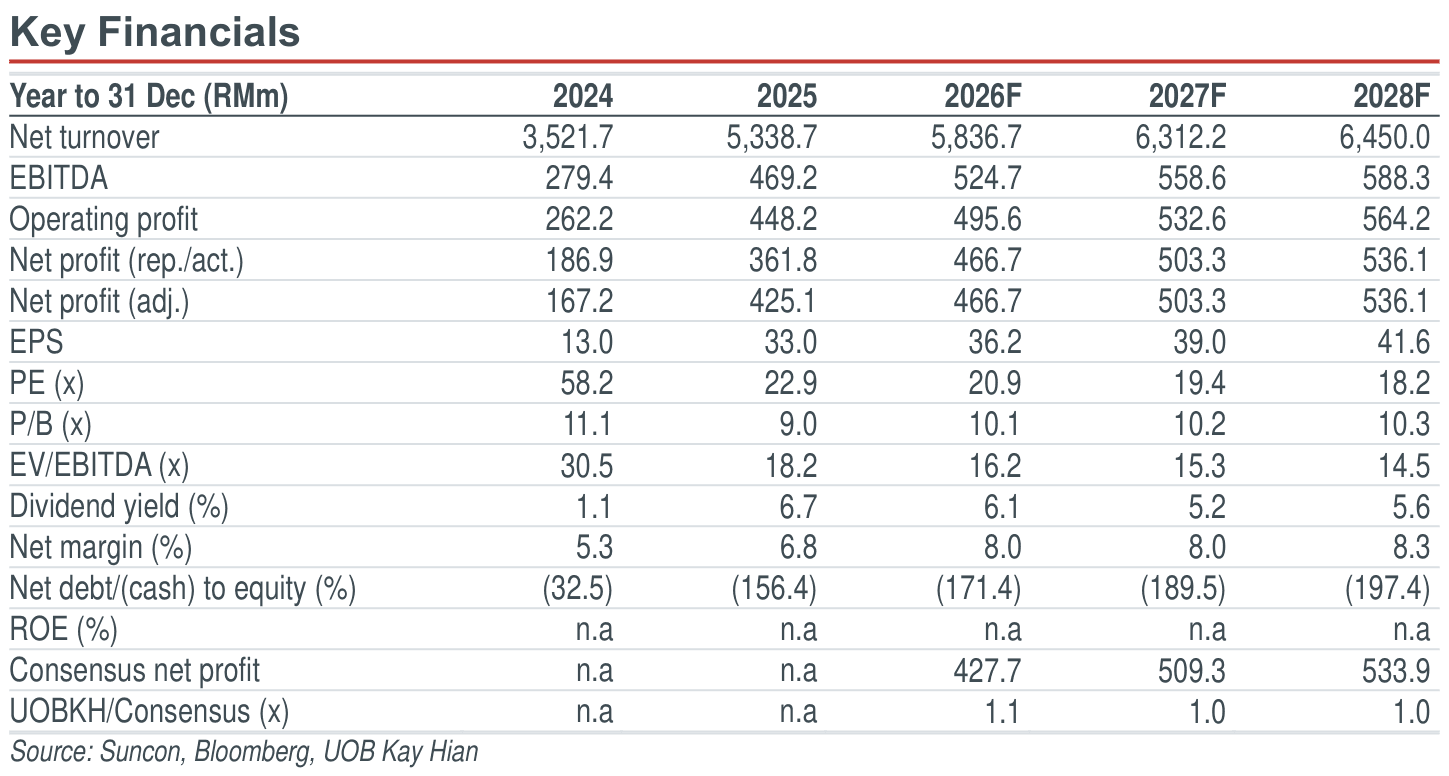
- Suncon’s implied dividend yield of 4.8-6.5% for 2026-27 (based on 100% dividend payout assumptions) remains appealing. Upgrade to BUY with an unchanged target price of RM8.44, which implies 22x 2027F PE.
Analysis
- Multi-year earnings growth remains intact; orderbook replenishment targets further revised upwards. Following the recent contracts wins, Sunway Construction (Suncon) has secured around RM6.9b in new jobs ytd. Management now targets to secure a RM7b-9b orderbook replenishment in 2026, raised from its initial target of RM6b. Suncon’s outstanding orderbook also stands tall at a record-high of RM10.5b (1.7x orderbook cover). We remain optimistic that the group’s RM7b-9b orderbook replenishment target in 2026 is highly attainable, well supported by data centre (DC)-related contracts.
- Resilient tenderbook pipeline with upsizing opportunities. With a healthy tenderbook of over RM14.2b, we are also optimistic that Suncon will be able to deliver earnings growth of 8-29% during 2026-28. The group is well positioned to clinch more contracts, with notable ones in the pipeline for 2H26-2027 including: a) multiple DC contracts (RM4b-6b); b) residential contracts for Rapid Transit System Transport Oriented Development (RTS TOD) at Bukit Chagar (RM350m-500m); c) internal project flows from parent company Sunway Berhad (potentially RM2b-3b); and d) various precast orders (~RM1b). Meanwhile, Suncon may also secure the MRT 3 civil packages (landbank acquisition completing in end-26) based on its past track records.
- Valuations appear palatable after recent share price correction. Suncon’s share price has retraced as much as 16% in 2H26 thus far, mainly reflecting: a) profit taking after the stellar share price rally of >50%, and b) the ongoing Middle East tensions. Meanwhile, the sharp withdrawal of foreign funds from Malaysian equities also hurts sentiment. In our opinion, Suncon’s current valuation poses palatable capital upside opportunities based on our forecasted earnings trajectories. Suncon is currently trading at 19x 2027F PE (five-year mean).
Highlights
- Suncon has achieved a record-high orderbook of RM10.5b. We remain confident that the group will achieve its orderbook replenishment of RM7b-9b in 2026.
- Suncon’s implied dividend yield of 4.8-6.5% for 2026-27 (based on 100% dividend payout assumptions) remains appealing. Upgrade to BUY with an unchanged target price of RM8.44, which implies 22x 2027F PE.
Analysis
- Multi-year earnings growth remains intact; orderbook replenishment targets further revised upwards. Following the recent contracts wins, Sunway Construction (Suncon) has secured around RM6.9b in new jobs ytd. Management now targets to secure a RM7b-9b orderbook replenishment in 2026, raised from its initial target of RM6b. Suncon’s outstanding orderbook also stands tall at a record-high of RM10.5b (1.7x orderbook cover). We remain optimistic that the group’s RM7b-9b orderbook replenishment target in 2026 is highly attainable, well supported by data centre (DC)-related contracts.
- Resilient tenderbook pipeline with upsizing opportunities. With a healthy tenderbook of over RM14.2b, we are also optimistic that Suncon will be able to deliver earnings growth of 8-29% during 2026-28. The group is well positioned to clinch more contracts, with notable ones in the pipeline for 2H26-2027 including: a) multiple DC contracts (RM4b-6b); b) residential contracts for Rapid Transit System Transport Oriented Development (RTS TOD) at Bukit Chagar (RM350m-500m); c) internal project flows from parent company Sunway Berhad (potentially RM2b-3b); and d) various precast orders (~RM1b). Meanwhile, Suncon may also secure the MRT 3 civil packages (landbank acquisition completing in end-26) based on its past track records.
- Valuations appear palatable after recent share price correction. Suncon’s share price has retraced as much as 16% in 2H26 thus far, mainly reflecting: a) profit taking after the stellar share price rally of >50%, and b) the ongoing Middle East tensions. Meanwhile, the sharp withdrawal of foreign funds from Malaysian equities also hurts sentiment. In our opinion, Suncon’s current valuation poses palatable capital upside opportunities based on our forecasted earnings trajectories. Suncon is currently trading at 19x 2027F PE (five-year mean).
BUY (Upgraded)
Current price:
Target price:
Upside:
RM7.57
RM8.44
11.5%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

