

Company Coverage
Fraser & Neave Holdings (FNH MK): Weathering The Perfect Storm
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM23.12
RM36.00
+55.7%
RM38.70
Analyst
Highlights
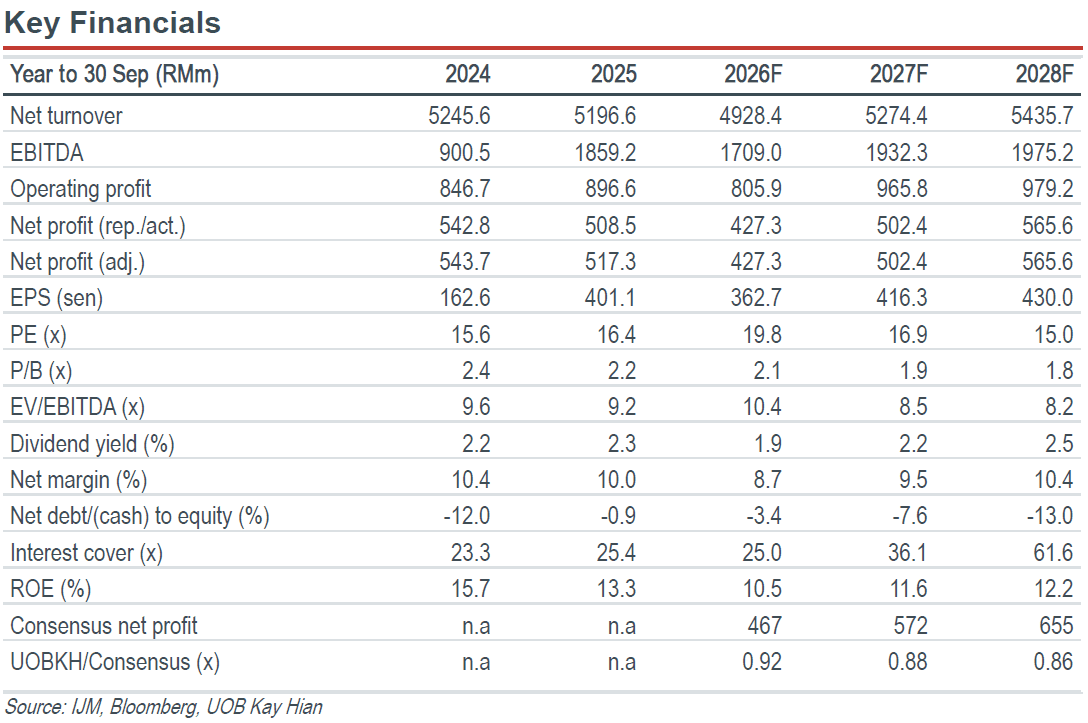
- Despite recently challenging times, F&N appears to have weathered the worst of its headwinds as earnings are set to improve going into FY27.
- AgriValley losses are set to narrow as F&N ramps up production, although contributions may be further out as short-term focus remains on the optimisation of its production vs expansion.
- Softness in Cambodia stemming from the border conflict is also set to improve as F&N scales up both its exports from Malaysia as well as the local manufacturing plant.
- Maintain BUY with a lower target price of RM36.00 as we shift dairy contribtutions slightly further out. Nonetheless, F&N’s current bargain valuations offer an attractive entry point.
Analysis
- Relief as perfect storm relents. While Fraser & Neave Holdings (F&N) continues to face challenging times, improving operational indices signal better times ahead. Losses from the dairy segment appear to have bottomed out and while Cambodia continues to be challenging following the Cambodia-Thailand border conflict, increasing exports from Malaysia and steady progress on the local manufacturing plant indicate that the worst of times may be behind them.
- Dairy yields improving… Yields for F&N’s dairy segment have improved to ~30 litres/cow/day (from ~25 litres in 3QFY26) as the group continues to develop its dairy farms. Currently, the stable of milking cows remains steady at over 3,000 with F&N’s target of 10,000 cows by 2029 remaining largely intact. The initial batch of milking cows have also begun yielding again, with production expected to improve in subsequent lactations (see overleaf table for details). We also note that market share for F&N’s ultra-high temperature (UHT) milk has improved from 1-2% previously to 5-6%. We understand that F&N’s focus for now remains on growing the UHT market vs competing aggressively for market share, and we expect F&N to eventually diversify into higher-value products (chilled milk, yoghurt, etc) once its UHT segment begins to deliver.
Highlights
- Despite recently challenging times, F&N appears to have weathered the worst of its headwinds as earnings are set to improve going into FY27.
- AgriValley losses are set to narrow as F&N ramps up production, although contributions may be further out as short-term focus remains on the optimisation of its production vs expansion.
- Softness in Cambodia stemming from the border conflict is also set to improve as F&N scales up both its exports from Malaysia as well as the local manufacturing plant.
- Maintain BUY with a lower target price of RM36.00 as we shift dairy contribtutions slightly further out. Nonetheless, F&N’s current bargain valuations offer an attractive entry point.
Analysis
- Relief as perfect storm relents. While Fraser & Neave Holdings (F&N) continues to face challenging times, improving operational indices signal better times ahead. Losses from the dairy segment appear to have bottomed out and while Cambodia continues to be challenging following the Cambodia-Thailand border conflict, increasing exports from Malaysia and steady progress on the local manufacturing plant indicate that the worst of times may be behind them.
- Dairy yields improving… Yields for F&N’s dairy segment have improved to ~30 litres/cow/day (from ~25 litres in 3QFY26) as the group continues to develop its dairy farms. Currently, the stable of milking cows remains steady at over 3,000 with F&N’s target of 10,000 cows by 2029 remaining largely intact. The initial batch of milking cows have also begun yielding again, with production expected to improve in subsequent lactations (see overleaf table for details). We also note that market share for F&N’s ultra-high temperature (UHT) milk has improved from 1-2% previously to 5-6%. We understand that F&N’s focus for now remains on growing the UHT market vs competing aggressively for market share, and we expect F&N to eventually diversify into higher-value products (chilled milk, yoghurt, etc) once its UHT segment begins to deliver.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM23.12
RM36.00
+55.7%
RM38.70
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

