

Company Coverage
Eco World Development (ECW MK): 3QFY26: In Line; Poised To Achieve Record Sales
BUY (Maintained)
Current price:
Target price:
Upside:
RM1.94
RM2.70
39.2%
Analyst
Highlights
- 3QFY26 results were in line. We expect ECW to post sequentially higher 4QFY26 earnings on the recognition of relatively high-margin DC land sales.
- ECW is well poised to surpass our full-year sales target of RM4.8b with the land sale to TERA DC, while the strong ytd sales momentum allows ECW to spread out its launches.
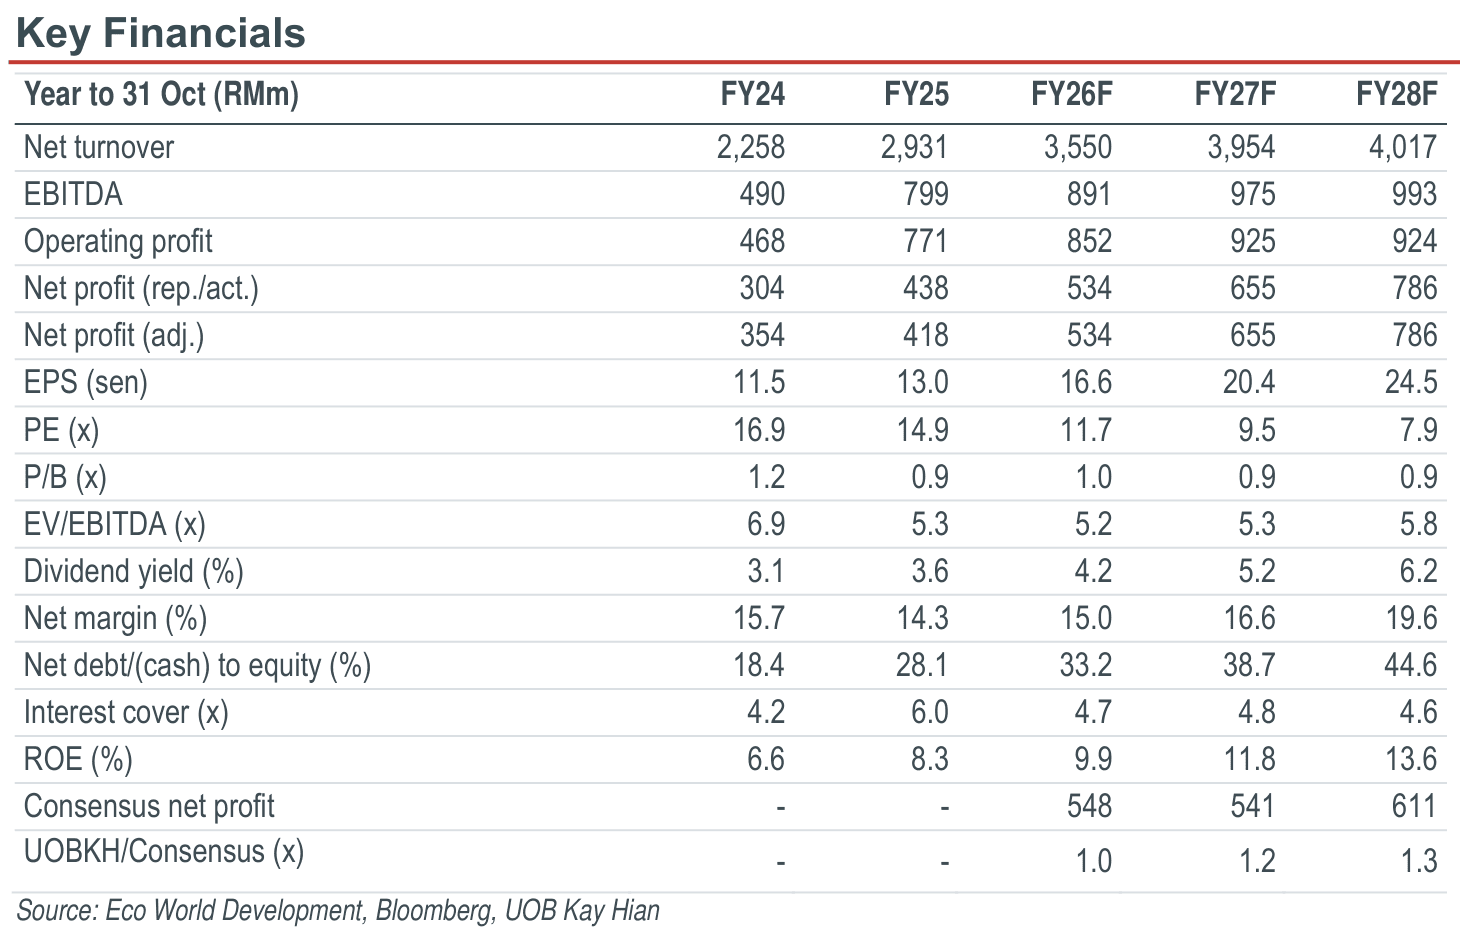
- Maintain BUY with a target price of RM2.70, implying an FY26F-27F PE of 13x-16x. At the current price, it offers a decent yield of more than 5%.
Analysis
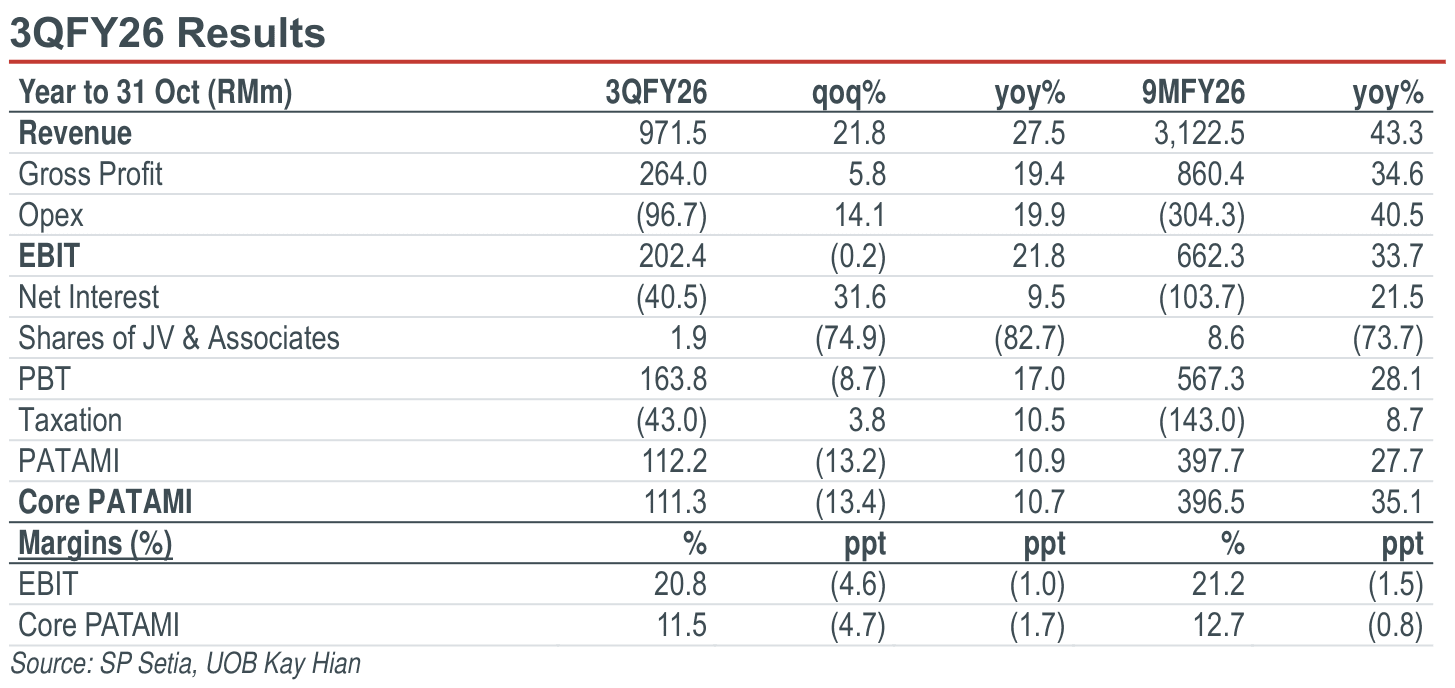
- In line. Eco World Development (ECW) reported a 3QFY26 core PATAMI of RM111m (-13.4% qoq; +10.7% yoy) on a revenue of RM972m (+21.8% qoq; +27.5% yoy). This brings 9MFY26 core PATAMI to RM397m, representing 74% and 73% of our and consensus full-year earnings estimates respectively, which we deem in line. Unbilled sales stood at RM5.0b (vs RM5.4b as of end-Apr 26). Net gearing remained flat at 0.21x (vs 0.22x as of end-Apr 26).
- ECW has declared a dividend of 2 sen for 3QFY26 (vs 2QFY26/3QFY25: 2 sen/2 sen).
Highlights
- 3QFY26 results were in line. We expect ECW to post sequentially higher 4QFY26 earnings on the recognition of relatively high-margin DC land sales.
- ECW is well poised to surpass our full-year sales target of RM4.8b with the land sale to TERA DC, while the strong ytd sales momentum allows ECW to spread out its launches.
- Maintain BUY with a target price of RM2.70, implying an FY26F-27F PE of 13x-16x. At the current price, it offers a decent yield of more than 5%.
Analysis
- In line. Eco World Development (ECW) reported a 3QFY26 core PATAMI of RM111m (-13.4% qoq; +10.7% yoy) on a revenue of RM972m (+21.8% qoq; +27.5% yoy). This brings 9MFY26 core PATAMI to RM397m, representing 74% and 73% of our and consensus full-year earnings estimates respectively, which we deem in line. Unbilled sales stood at RM5.0b (vs RM5.4b as of end-Apr 26). Net gearing remained flat at 0.21x (vs 0.22x as of end-Apr 26).
- ECW has declared a dividend of 2 sen for 3QFY26 (vs 2QFY26/3QFY25: 2 sen/2 sen).
BUY (Maintained)
Current price:
Target price:
Upside:
RM1.94
RM2.70
39.2%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

