

Company Coverage
Sawit Sumbermas Sarana (SSMS IJ): Strong 1H26 Profit, Momentum Guided To Carry Into Year-end
NOT RATED
Current price:
Target price:
Upside:
Rp1,040
n.a.
n.a.
Analyst
Analyst
Highlights
- Integrated producer, prime-age estate. SSMS runs a compact estate base in Central Kalimantan at an average age of 15.8 years, with one of the sector's highest yields and extraction rates.
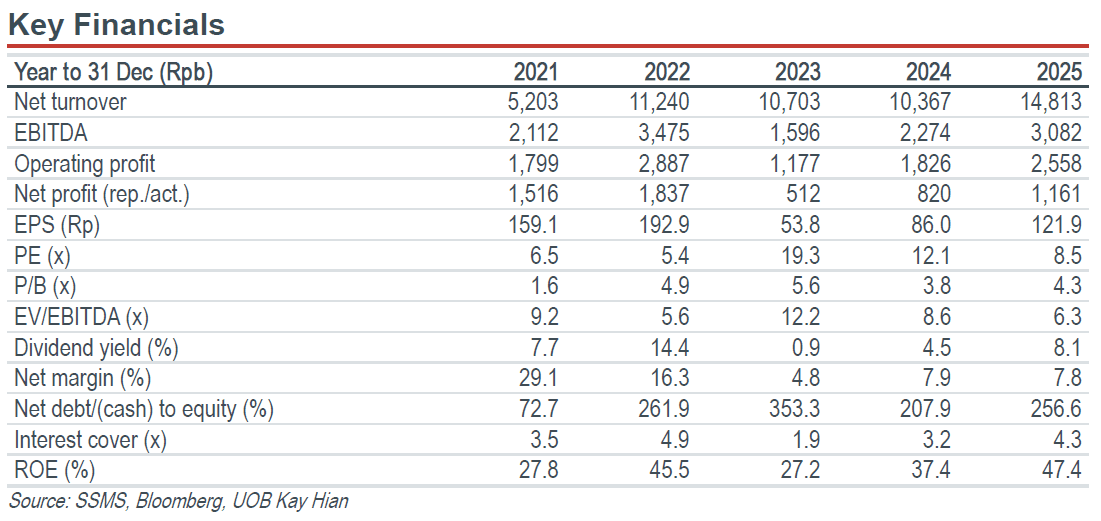
- Strong 1H26 profit, momentum into year end. 1H26 net profit reached Rp904b (+31% yoy) on higher FFB production of 25% yoy. Management guides 2H26 production to be 5-6% above 1H26, with further upside from higher CPO prices.
- Mid-single-digit PE with high potential dividend yield. The stock trades at an EV/ha of Rp198m, (~27% below TAPG) and at an undemanding 5.6x PE on annualised 1H26 profit. A payout in line with the 55-69% paid over the past two years would imply a 10.0-12.6% dividend yield.
Analysis
- An integrated palm oil producer in Central Kalimantan. Sawit Sumbermas Sarana (SSMS) has 94,963ha planted, with an average age of 15.8 years, in three adjacent blocks. These are within 1.0-3.5 hours of Pangkalan Bun and served by 10 mills (670 tonnes/hour capacity). This compact footprint keeps logistics efficient and supports solid productivity, with a blended FFB yield of 1.9 tonnes/ha/month (peer average at 1.5) and an oil extraction rate (OER) of 22.6% (peer average at 21.5%) in 1H26. SSMS moved downstream in Dec 23, acquiring 52.6% of refiner Citra Borneo Utama (CBUT) from its parent via a Rp3.5t loan conversion; this lifted its group stake to 78.2%. This gave it a 2,500 tonnes/day refinery and fractionation plant and a 600 tonnes/day kernel crushing plant, producing refined, bleached and deodorised palm oil (RBDPO), olein, stearin, palm fatty acid distillate (PFAD), crude palm kernel oil, palm kernel expeller and packaged cooking oil. In Nov 25, it bought 63.4% of Sawit Mandiri Lestari (SML) for Rp1.6t, adding 12,000ha of younger estates (~8.5 years).
- Strong 1H26 profit, led by upstream volume, with optimism towards year-end. SSMS delivered a strong 1H26 net profit of Rp904b (+31% yoy) on higher revenue of 36.5% yoy, with 2Q26 net profit of Rp586b (+84% qoq, +67% yoy). Beyond firm CPO prices, growth came from its own FFB production, which rose 25% yoy to 1m tonnes in 1H26 with support from the recently acquired estates from SML. It is also worth noting that group revenue to related parties fell from 36% in 1H25 to only 1% in 1H26, as SSMS sold less refined products into the group and more crude to third parties, most likely to capture the high CPO prices. Management stays constructive on 2H26, guiding production to be 5-6% above 1H26 on better fertiliser application earlier in the year, with further upside from prices as CPO futures sit near RM4,741/tonne (vs 1H26 average of RM4,329/tonne).
Highlights
- Integrated producer, prime-age estate. SSMS runs a compact estate base in Central Kalimantan at an average age of 15.8 years, with one of the sector's highest yields and extraction rates.
- Strong 1H26 profit, momentum into year end. 1H26 net profit reached Rp904b (+31% yoy) on higher FFB production of 25% yoy. Management guides 2H26 production to be 5-6% above 1H26, with further upside from higher CPO prices.
- Mid-single-digit PE with high potential dividend yield. The stock trades at an EV/ha of Rp198m, (~27% below TAPG) and at an undemanding 5.6x PE on annualised 1H26 profit. A payout in line with the 55-69% paid over the past two years would imply a 10.0-12.6% dividend yield.
Analysis
- An integrated palm oil producer in Central Kalimantan. Sawit Sumbermas Sarana (SSMS) has 94,963ha planted, with an average age of 15.8 years, in three adjacent blocks. These are within 1.0-3.5 hours of Pangkalan Bun and served by 10 mills (670 tonnes/hour capacity). This compact footprint keeps logistics efficient and supports solid productivity, with a blended FFB yield of 1.9 tonnes/ha/month (peer average at 1.5) and an oil extraction rate (OER) of 22.6% (peer average at 21.5%) in 1H26. SSMS moved downstream in Dec 23, acquiring 52.6% of refiner Citra Borneo Utama (CBUT) from its parent via a Rp3.5t loan conversion; this lifted its group stake to 78.2%. This gave it a 2,500 tonnes/day refinery and fractionation plant and a 600 tonnes/day kernel crushing plant, producing refined, bleached and deodorised palm oil (RBDPO), olein, stearin, palm fatty acid distillate (PFAD), crude palm kernel oil, palm kernel expeller and packaged cooking oil. In Nov 25, it bought 63.4% of Sawit Mandiri Lestari (SML) for Rp1.6t, adding 12,000ha of younger estates (~8.5 years).
- Strong 1H26 profit, led by upstream volume, with optimism towards year-end. SSMS delivered a strong 1H26 net profit of Rp904b (+31% yoy) on higher revenue of 36.5% yoy, with 2Q26 net profit of Rp586b (+84% qoq, +67% yoy). Beyond firm CPO prices, growth came from its own FFB production, which rose 25% yoy to 1m tonnes in 1H26 with support from the recently acquired estates from SML. It is also worth noting that group revenue to related parties fell from 36% in 1H25 to only 1% in 1H26, as SSMS sold less refined products into the group and more crude to third parties, most likely to capture the high CPO prices. Management stays constructive on 2H26, guiding production to be 5-6% above 1H26 on better fertiliser application earlier in the year, with further upside from prices as CPO futures sit near RM4,741/tonne (vs 1H26 average of RM4,329/tonne).
NOT RATED
Current price:
Target price:
Upside:
Rp1,040
n.a.
n.a.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

