

Company Coverage
Erajaya Swasembada (ERAA IJ): Continuous Successful Expansion
BUY (Maintained)
Current price:
Target price:
Upside:
Rp615
Rp800
+30.1%
Analyst
Analyst
Highlights
- Diversification continues. The higher-margin active lifestyle and accessories businesses now contribute 19% of revenue, up from 12% in 1H24.
- New retail formats gaining traction. Erablue and ERAL continued to outperform, with 7M26 SSSG of 15.9% and 7.7%, respectively.
- Share buyback resumes. ERAA plans a new Rp500b buyback, potentially repurchasing up to 5% of outstanding shares. Maintain BUY with a target price of Rp800.
Analysis
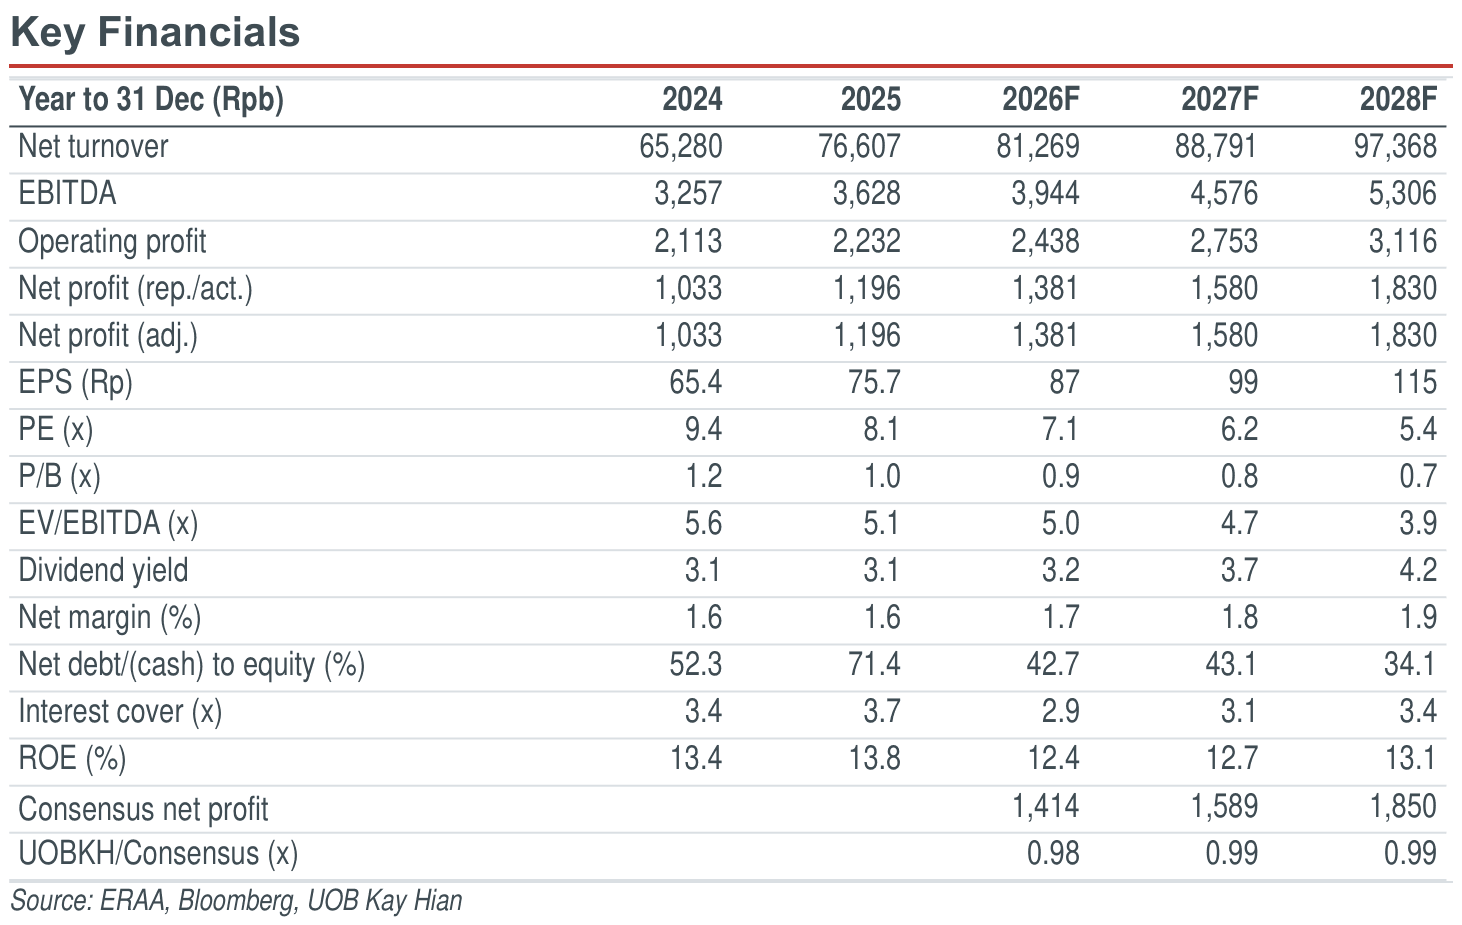
- Diversified retail play going beyond smartphones. Erajaya Swasembada (ERAA), a retail and distribution company, operates three main verticals — Erajaya Digital, Erajaya Active Lifestyle, and Erajaya Food & Nourishment — with more than 2,500 stores regionally, over 30 world-class brands, and 8.4m members. By product, 1H26 revenue contribution was 75.6% from cellular phones & tablets, 5.6% from computers & consumer electronics, 4.1% from active & lifestyle goods, and 14.7% from accessories & others. The company has 1,920 stores domestically and 240 internationally. Its active lifestyle arm, Sinar Eka Selaras (ERAL), listed in Aug 23 and posted 1H26 revenue of Rp3,685b (+41% yoy), contributing around 9% to ERAA's consolidated revenue.
- Expanding into higher-margin businesses. ERAA's higher-margin segments − active lifestyle and accessories − lifted their combined revenue contribution to 19% in 1H26 (vs 12%/17% in 1H24/1H25), improving the margin mix: active lifestyle and accessories carried a 20% gross profit margin in 1H26 vs just 9% for cellular phones & tablets and computers & consumer electronics. Active lifestyle (ERAL) spans a broad brand portfolio − including, to name a few, Garmin, Urban Republic, Asics, Anta, XPeng (EV), JD, and Levi's − with 256 stores as of 1H26 and plans to add 50-60 stores per year going forward, alongside a selective 5-6 new brands annually. The company also operates 90 food & nourishment stores, spanning brands such as Paris Baguette, Grand Lucky, Chagee, and Oriental Kopi, among others, and intends to keep diversifying with innovative, high growth potential brands.
Highlights
- Diversification continues. The higher-margin active lifestyle and accessories businesses now contribute 19% of revenue, up from 12% in 1H24.
- New retail formats gaining traction. Erablue and ERAL continued to outperform, with 7M26 SSSG of 15.9% and 7.7%, respectively.
- Share buyback resumes. ERAA plans a new Rp500b buyback, potentially repurchasing up to 5% of outstanding shares. Maintain BUY with a target price of Rp800.
Analysis
- Diversified retail play going beyond smartphones. Erajaya Swasembada (ERAA), a retail and distribution company, operates three main verticals — Erajaya Digital, Erajaya Active Lifestyle, and Erajaya Food & Nourishment — with more than 2,500 stores regionally, over 30 world-class brands, and 8.4m members. By product, 1H26 revenue contribution was 75.6% from cellular phones & tablets, 5.6% from computers & consumer electronics, 4.1% from active & lifestyle goods, and 14.7% from accessories & others. The company has 1,920 stores domestically and 240 internationally. Its active lifestyle arm, Sinar Eka Selaras (ERAL), listed in Aug 23 and posted 1H26 revenue of Rp3,685b (+41% yoy), contributing around 9% to ERAA's consolidated revenue.
- Expanding into higher-margin businesses. ERAA's higher-margin segments − active lifestyle and accessories − lifted their combined revenue contribution to 19% in 1H26 (vs 12%/17% in 1H24/1H25), improving the margin mix: active lifestyle and accessories carried a 20% gross profit margin in 1H26 vs just 9% for cellular phones & tablets and computers & consumer electronics. Active lifestyle (ERAL) spans a broad brand portfolio − including, to name a few, Garmin, Urban Republic, Asics, Anta, XPeng (EV), JD, and Levi's − with 256 stores as of 1H26 and plans to add 50-60 stores per year going forward, alongside a selective 5-6 new brands annually. The company also operates 90 food & nourishment stores, spanning brands such as Paris Baguette, Grand Lucky, Chagee, and Oriental Kopi, among others, and intends to keep diversifying with innovative, high growth potential brands.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp615
Rp800
+30.1%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

