

Company Coverage
Bank Central Asia (BBCA IJ): Repricing Is Lifting NIM; Loan Growth Remains Selective
BUY (Maintained)
Current price:
Target price:
Upside:
Rp6,225
Rp8,150
+30.9%
Analyst
Highlights
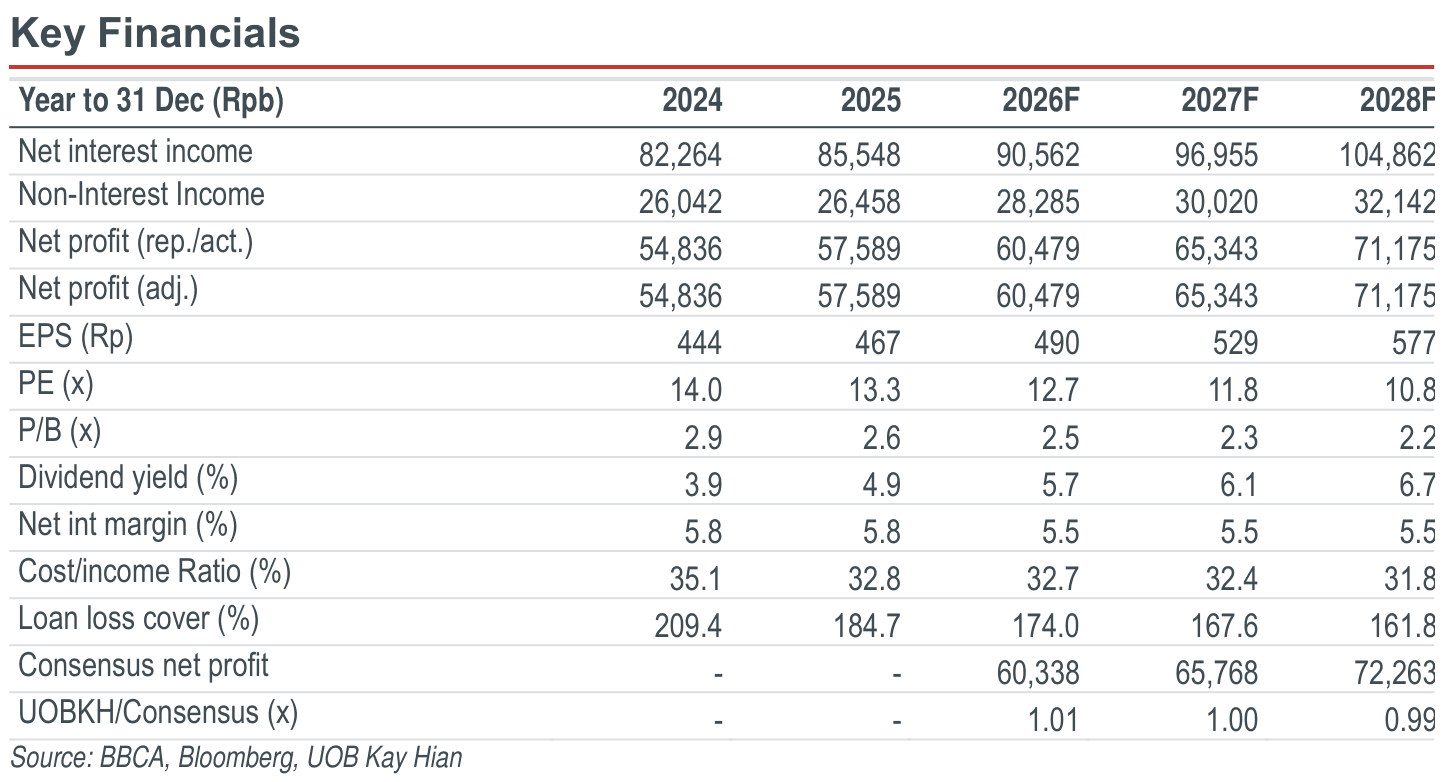
- NIM improved to 5.7% in August (from 5.3% in 1H26) as corporate loan yields rose to 7.4% from 6.7-6.8% in April; 2026 NIM guidance of 5.4-5.6% remains unchanged, though the upper end is dependent on rates.
- CASA at 85.5% of deposits and LDR at 81.0% give BBCA room to stay selective. The bank is repricing corporate loans on a borrower-by-borrower basis to protect CASA relationships, and holding the line on SME rates and consumer underwriting standards.
- Maintain BUY with an unchanged target price of Rp8,150. BBCA remains our preferred bank pick for its funding, liquidity and capital buffers, though further re-rating hinges on macro clarity and foreign flows returning.
Analysis
- Corporate repricing is lifting NIM, but management remains selective. Bank Central Asia’s (BBCA) corporate loan yield rose to 7.4% in August from 6.7–6.8% in April, helping monthly net interest margin (NIM) improve from 5.3% in 1H26 to 5.6% in July and 5.7% in August. Higher yields on maturing Bank Indonesia (BI) placements also contributed. Management remains confident in its 5.4-5.6% full-year NIM guidance, though the rate outlook makes the upper end uncertain. Its 50-100bp repricing objective covers eligible existing and new corporate loans, with each borrower assessed individually to protect current account and savings account (CASA) relationships. Management is also reluctant to raise SME rates further given the potential impact on asset quality.
Liquidity and digital capabilities support its selective growth. August bank-only deposits rose 8.3% yoy to Rp1,256.8t, led by current accounts (+14.7% yoy) and savings (+8.2% yoy), while time deposits fell 4.3% yoy. CASA accounted for 85.5% of deposits and loan-to-deposit (LDR) stood at 81.0%, giving Bank Central Asia (BBCA) room to wait for better lending opportunities. Management sees reliable digital transactions as central to retaining low-cost funds, and plans to expand its presence in corporate current accounts. Together with its strong capital and liquidity buffers, this provides flexibility if the macro environment weakens.
Highlights
- NIM improved to 5.7% in August (from 5.3% in 1H26) as corporate loan yields rose to 7.4% from 6.7-6.8% in April; 2026 NIM guidance of 5.4-5.6% remains unchanged, though the upper end is dependent on rates.
- CASA at 85.5% of deposits and LDR at 81.0% give BBCA room to stay selective. The bank is repricing corporate loans on a borrower-by-borrower basis to protect CASA relationships, and holding the line on SME rates and consumer underwriting standards.
- Maintain BUY with an unchanged target price of Rp8,150. BBCA remains our preferred bank pick for its funding, liquidity and capital buffers, though further re-rating hinges on macro clarity and foreign flows returning.
Analysis
- Corporate repricing is lifting NIM, but management remains selective. Bank Central Asia’s (BBCA) corporate loan yield rose to 7.4% in August from 6.7–6.8% in April, helping monthly net interest margin (NIM) improve from 5.3% in 1H26 to 5.6% in July and 5.7% in August. Higher yields on maturing Bank Indonesia (BI) placements also contributed. Management remains confident in its 5.4-5.6% full-year NIM guidance, though the rate outlook makes the upper end uncertain. Its 50-100bp repricing objective covers eligible existing and new corporate loans, with each borrower assessed individually to protect current account and savings account (CASA) relationships. Management is also reluctant to raise SME rates further given the potential impact on asset quality.
Liquidity and digital capabilities support its selective growth. August bank-only deposits rose 8.3% yoy to Rp1,256.8t, led by current accounts (+14.7% yoy) and savings (+8.2% yoy), while time deposits fell 4.3% yoy. CASA accounted for 85.5% of deposits and loan-to-deposit (LDR) stood at 81.0%, giving Bank Central Asia (BBCA) room to wait for better lending opportunities. Management sees reliable digital transactions as central to retaining low-cost funds, and plans to expand its presence in corporate current accounts. Together with its strong capital and liquidity buffers, this provides flexibility if the macro environment weakens.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp6,225
Rp8,150
+30.9%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

