

Company Coverage
AKR Corporindo (AKRA IJ): Stronger Earnings, Building JIIPE’s Next Phase
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,490
Rp1,600
+7.4%
Analyst
Highlights
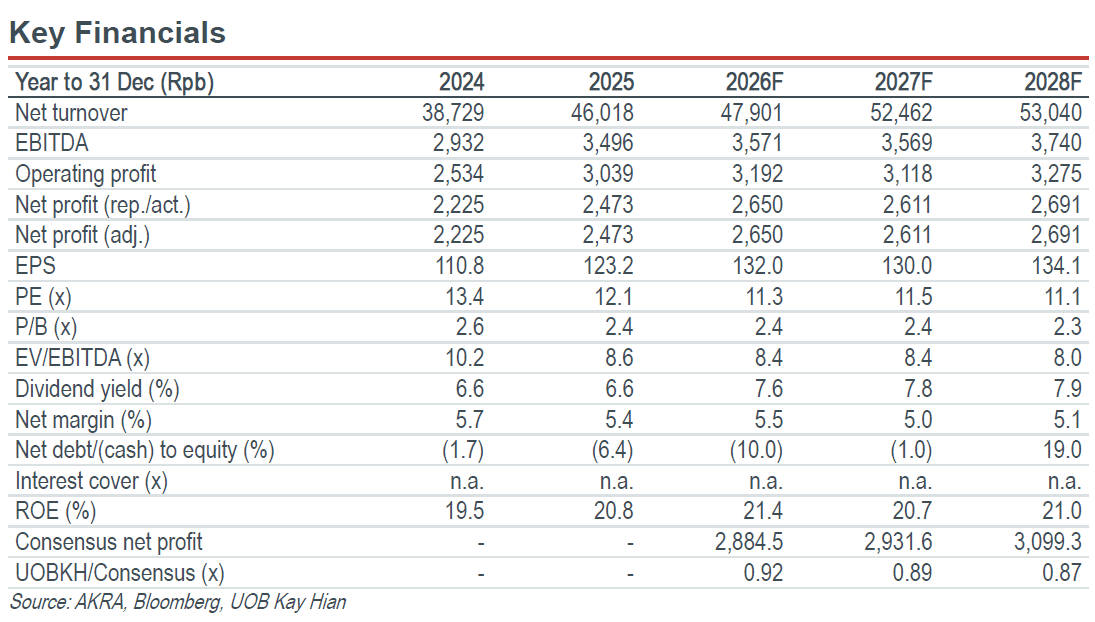
- Earnings momentum is ahead of our estimates. Management sees 2026 net profit potentially exceeding its upper limit net profit guidance of Rp2.9t, supported by strong trading and distribution, 100ha land sales and rising utilities income.
- JIIPE's land runway extends, shifting the focus to power. Around 600ha of industrial land remains, while 800ha of residential land could potentially be converted. As the tenant base expands and electricity demand rises, securing sufficient and reliable power supply is becoming increasingly important for JIIPE's next growth phase.
- Utilities are scaling as AKRA builds its energy infrastructure. Utilities revenue could reach Rp1t in 2026 and potentially Rp2t in 2027, while planned solar, gas and LNG infrastructure should support longer-term tenant growth and energy security. Maintain BUY with a Rp1,600 target price.
Analysis
- Earnings momentum ahead of our estimates. Our meeting with AKR Corporindo (AKRA) points to stronger 2026 earnings momentum, with management seeing potential for net profit to exceed the upper end of its Rp2.6t-2.9t guidance. The Rp2.9t upper end is 9% above our Rp2.65t forecast and broadly in line with consensus, implying further upside if earnings exceed guidance. The strong earnings are supported by: a) strong trading and distribution business momentum, b) 100ha of land sales (1H26: 58ha), and c) rising utilities income. Trading and distribution remain particularly well supported, with increases in mining quotas activities of some mining companies. As of 1H26, mining accounting for 70% of company's B2B petroleum exposure while supply security also remains a competitive advantage during periods of tighter petroleum availability.
- Land runway extends; power becomes increasingly important. Java Integrated Industrial and Ports Estate (JIIPE) has around 600ha of remaining industrial land, equivalent to around six years of supply at 100ha annual sales. Management also highlighted 800ha of residential land that could be converted into industrial use, providing additional runway if demand remains strong. With land availability less of an immediate constraint, securing sufficient and reliable power is becoming increasingly important as JIIPE's tenant base expands and electricity demand rises. JIIPE currently relies on PLN, with 500MW secured and potential capacity beyond 1GW.
Highlights
- Earnings momentum is ahead of our estimates. Management sees 2026 net profit potentially exceeding its upper limit net profit guidance of Rp2.9t, supported by strong trading and distribution, 100ha land sales and rising utilities income.
- JIIPE's land runway extends, shifting the focus to power. Around 600ha of industrial land remains, while 800ha of residential land could potentially be converted. As the tenant base expands and electricity demand rises, securing sufficient and reliable power supply is becoming increasingly important for JIIPE's next growth phase.
- Utilities are scaling as AKRA builds its energy infrastructure. Utilities revenue could reach Rp1t in 2026 and potentially Rp2t in 2027, while planned solar, gas and LNG infrastructure should support longer-term tenant growth and energy security. Maintain BUY with a Rp1,600 target price.
Analysis
- Earnings momentum ahead of our estimates. Our meeting with AKR Corporindo (AKRA) points to stronger 2026 earnings momentum, with management seeing potential for net profit to exceed the upper end of its Rp2.6t-2.9t guidance. The Rp2.9t upper end is 9% above our Rp2.65t forecast and broadly in line with consensus, implying further upside if earnings exceed guidance. The strong earnings are supported by: a) strong trading and distribution business momentum, b) 100ha of land sales (1H26: 58ha), and c) rising utilities income. Trading and distribution remain particularly well supported, with increases in mining quotas activities of some mining companies. As of 1H26, mining accounting for 70% of company's B2B petroleum exposure while supply security also remains a competitive advantage during periods of tighter petroleum availability.
- Land runway extends; power becomes increasingly important. Java Integrated Industrial and Ports Estate (JIIPE) has around 600ha of remaining industrial land, equivalent to around six years of supply at 100ha annual sales. Management also highlighted 800ha of residential land that could be converted into industrial use, providing additional runway if demand remains strong. With land availability less of an immediate constraint, securing sufficient and reliable power is becoming increasingly important as JIIPE's tenant base expands and electricity demand rises. JIIPE currently relies on PLN, with 500MW secured and potential capacity beyond 1GW.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,490
Rp1,600
+7.4%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
