
Initiation of coverage
Momenta Global (6880 HK): Data Flywheel Leader At A Profit Inflection Point
BUY (Initiation)
Current price:
Target price:
Upside:
HK$146.00
HK$270.00
+84.9%
Analyst
Highlights
- Initiate coverage on Momenta with BUY and a target price of HK$270.00.
- Momenta is the largest independent provider of driving-automation software globally, with 64.5% of vehicles sold with an independent urban navigationon-autopilot system as at 28 Feb 26, and a data flywheel of more than 1m vehicles returning about 630,000 clips a day.
- Cumulative nominations totalling 219 at mid-26 (of which 105 are already at SOP) underpin our revenue forecasts of Rmb4b/Rmb11.3b/Rmb21.6b for 2026/28/30 respectively, representing a 55% five-year CAGR.
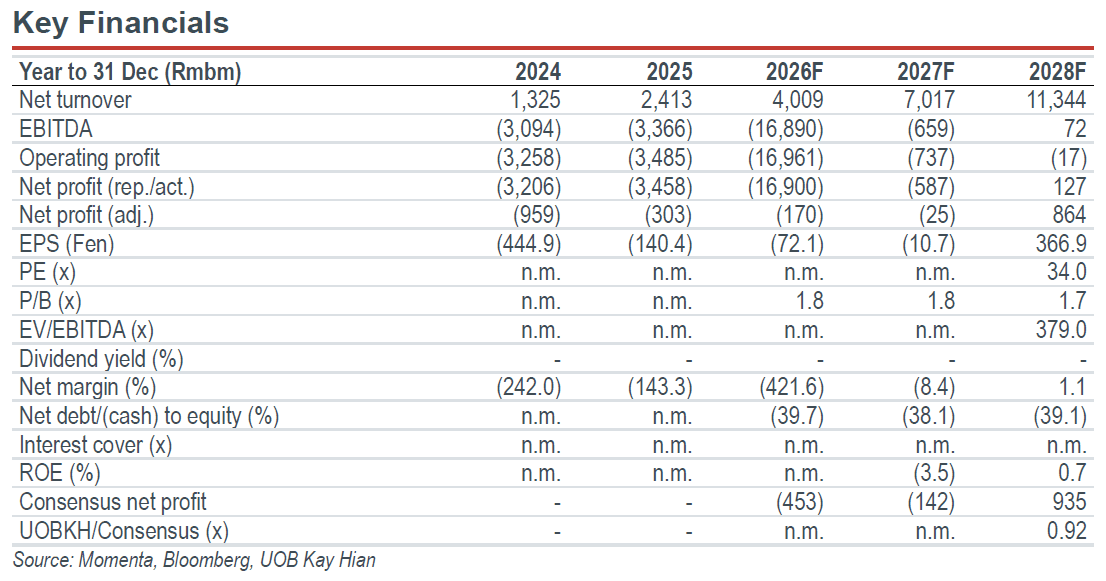
- The shift to licensing lifted blended gross margin from 17.5% in 2023 to 71.6% in 2025. We expect adjusted net loss to narrow to Rmb170m/Rmb25m in 2026/27 respectively, before turning profitable at Rmb864m in 2028 and growing to Rmb3.8b in 2030.
Analysis
- The number one independent player. Momenta Global (Momenta) held 65.4% of the 249 cumulative start-of-production (SOP) programmes and nominations among independent urban navigation-on-autopilot (NOA) providers globally as at 28 Feb 26, against 14.5% for Huawei, and serves 26 OEM customers, 13 of them international. Its fleet has accumulated 1,628m km of NOA driving data, about 1.8 times that of the next-largest independent provider, and returns about 630,000 clips a day.
- Customers are also shareholders. General Motors Company holds 8.58% of the enlarged share capital and Mercedes-Benz 6.13%, and each has nominated a non-executive director. Models run from the electric Mercedes-Benz CLA and BMW iX3 to Toyota’s bZ5 and BYD’s Denza range.
- Licensing drives margin expansion. Licensing revenue rose from 3.1% of total revenue in 2023 to 40.1% in 2025, and we expect it to reach 44.1%/50.4% by 2028/30 respectively. The number of installations could rise from 510,000 to 2.91m/6.85m in 2028/30 resp ectively (68% five-year CAGR), more than offsetting a 5% volume discount.
- Robotaxi and robovan services offer upside optionality. The L4 fleet could grow from 31 vehicles as at end-25 to 11,000/78,000 by end-27/30, contributing 2.1%/16.6% of 2027/30 revenue. Momenta is seeking the retail subscription model for urban NOA, which our forecasts have not factored in.
- Initiate coverage with a target price of HK$270.00, based on 10-year DCF (WACC: 15%/terminal growth: 3%). Our target price implies 7.7x 2027F PS.
- Risks: Customer concentration, data-flywheel erosion, ship/system-on-chip supply, GPU purchases, licensing fee deflation, robotaxi timing/regulation.
Highlights
- Initiate coverage on Momenta with BUY and a target price of HK$270.00.
- Momenta is the largest independent provider of driving-automation software globally, with 64.5% of vehicles sold with an independent urban navigationon-autopilot system as at 28 Feb 26, and a data flywheel of more than 1m vehicles returning about 630,000 clips a day.
- Cumulative nominations totalling 219 at mid-26 (of which 105 are already at SOP) underpin our revenue forecasts of Rmb4b/Rmb11.3b/Rmb21.6b for 2026/28/30 respectively, representing a 55% five-year CAGR.
- The shift to licensing lifted blended gross margin from 17.5% in 2023 to 71.6% in 2025. We expect adjusted net loss to narrow to Rmb170m/Rmb25m in 2026/27 respectively, before turning profitable at Rmb864m in 2028 and growing to Rmb3.8b in 2030.
Analysis
- The number one independent player. Momenta Global (Momenta) held 65.4% of the 249 cumulative start-of-production (SOP) programmes and nominations among independent urban navigation-on-autopilot (NOA) providers globally as at 28 Feb 26, against 14.5% for Huawei, and serves 26 OEM customers, 13 of them international. Its fleet has accumulated 1,628m km of NOA driving data, about 1.8 times that of the next-largest independent provider, and returns about 630,000 clips a day.
- Customers are also shareholders. General Motors Company holds 8.58% of the enlarged share capital and Mercedes-Benz 6.13%, and each has nominated a non-executive director. Models run from the electric Mercedes-Benz CLA and BMW iX3 to Toyota’s bZ5 and BYD’s Denza range.
- Licensing drives margin expansion. Licensing revenue rose from 3.1% of total revenue in 2023 to 40.1% in 2025, and we expect it to reach 44.1%/50.4% by 2028/30 respectively. The number of installations could rise from 510,000 to 2.91m/6.85m in 2028/30 resp ectively (68% five-year CAGR), more than offsetting a 5% volume discount.
- Robotaxi and robovan services offer upside optionality. The L4 fleet could grow from 31 vehicles as at end-25 to 11,000/78,000 by end-27/30, contributing 2.1%/16.6% of 2027/30 revenue. Momenta is seeking the retail subscription model for urban NOA, which our forecasts have not factored in.
- Initiate coverage with a target price of HK$270.00, based on 10-year DCF (WACC: 15%/terminal growth: 3%). Our target price implies 7.7x 2027F PS.
- Risks: Customer concentration, data-flywheel erosion, ship/system-on-chip supply, GPU purchases, licensing fee deflation, robotaxi timing/regulation.
BUY (Initiation)
Current price:
Target price:
Upside:
HK$146.00
HK$270.00
+84.9%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


