
Company Coverage
Weichai Power (2338 HK) - 3Q26: In Line; Power And Energy Remain The Growth Engines; Upgrade To BUY
BUY (Upgraded)
Current price:
Target price:
Upside:
HK$23.52
HK$31.00
+31.8%
Analyst
Highlights
- 3Q26 adjusted net profit rose 13.9% yoy to Rmb3,220m, in line. GAAP net profit fell 8.6% on Ballard fair value losses, credit provisions and forex loss.
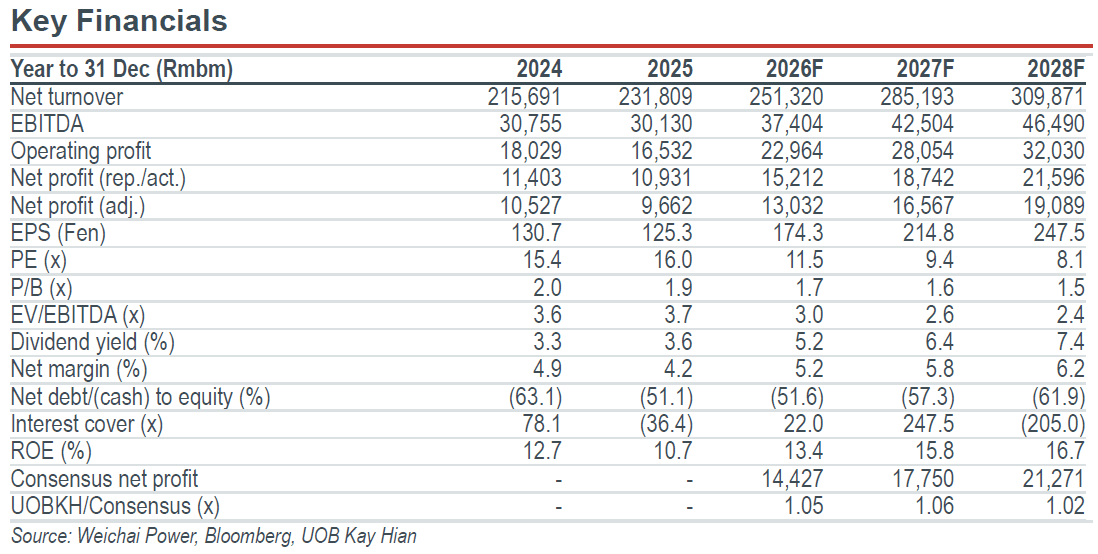
- Looking ahead, the power and energy segments will serve as the primary growth drivers of Weichai, contributing about 20% of group profit.
- Management is guiding for data centre diesel gensets of above 4,000 units in 2026 and above 6,000 in 2027.
- Upgrade from HOLD to BUY with an unchanged target price of HK$31.00 pegged to 12x 2027F PE.
Analysis
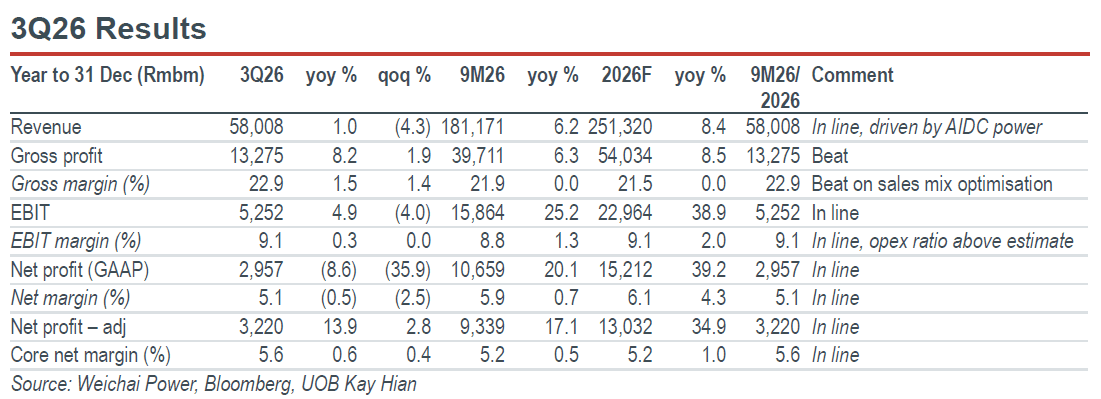
- 3Q26 results met expectations, with GAAP net profit of Rmb2,957m (-8.6% yoy/-35.9% qoq) and adjusted net profit of Rmb3,220m (+13.9% yoy/+2.8% qoq). The drop in GAAP net profit was due to: a) revenue slowdown (+1% yoy/-4% qoq); b) fair value loss of Rmb293m (+606% yoy) for Ballard Power Systems (Ballard) vs 2Q26 fair value gain of Rmb186m; c) credit provision of Rmb332m vs credit provision write-back of Rmb383m/Rmb108m in 3Q25/2Q26 respectively, and d) forex loss of Rmb200m vs 3Q25’s forex gain of >Rmb100m.
- Revenue edged up 1% yoy and dropped 4.3% qoq to Rmb58b in 3Q26, driven by large-bore engines.
- The sales volume of large-bore engines surged 60% yoy to 4,000 units in 3Q26, bringing 9M26 volume to >11,000 units (+40% yoy). Among them, sales volume of AI data centre (ADIC) power generation sets (gensets) grew from 500 units in 1Q26 to 800/1,300 units in 2Q26/3Q26 respectively.
Highlights
- 3Q26 adjusted net profit rose 13.9% yoy to Rmb3,220m, in line. GAAP net profit fell 8.6% on Ballard fair value losses, credit provisions and forex loss.
- Looking ahead, the power and energy segments will serve as the primary growth drivers of Weichai, contributing about 20% of group profit.
- Management is guiding for data centre diesel gensets of above 4,000 units in 2026 and above 6,000 in 2027.
- Upgrade from HOLD to BUY with an unchanged target price of HK$31.00 pegged to 12x 2027F PE.
Analysis
- 3Q26 results met expectations, with GAAP net profit of Rmb2,957m (-8.6% yoy/-35.9% qoq) and adjusted net profit of Rmb3,220m (+13.9% yoy/+2.8% qoq). The drop in GAAP net profit was due to: a) revenue slowdown (+1% yoy/-4% qoq); b) fair value loss of Rmb293m (+606% yoy) for Ballard Power Systems (Ballard) vs 2Q26 fair value gain of Rmb186m; c) credit provision of Rmb332m vs credit provision write-back of Rmb383m/Rmb108m in 3Q25/2Q26 respectively, and d) forex loss of Rmb200m vs 3Q25’s forex gain of >Rmb100m.
- Revenue edged up 1% yoy and dropped 4.3% qoq to Rmb58b in 3Q26, driven by large-bore engines.
- The sales volume of large-bore engines surged 60% yoy to 4,000 units in 3Q26, bringing 9M26 volume to >11,000 units (+40% yoy). Among them, sales volume of AI data centre (ADIC) power generation sets (gensets) grew from 500 units in 1Q26 to 800/1,300 units in 2Q26/3Q26 respectively.
BUY (Upgraded)
Current price:
Target price:
Upside:
HK$23.52
HK$31.00
+31.8%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


