
Company Coverage
Xiaomi Corp (1810 HK) - 3Q26 Preview: Weaker Consumer Demand To Weigh On Earnings
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$26.48
HK$25.90
-2.2%
HK$26.20
Analyst
Analyst
Highlights
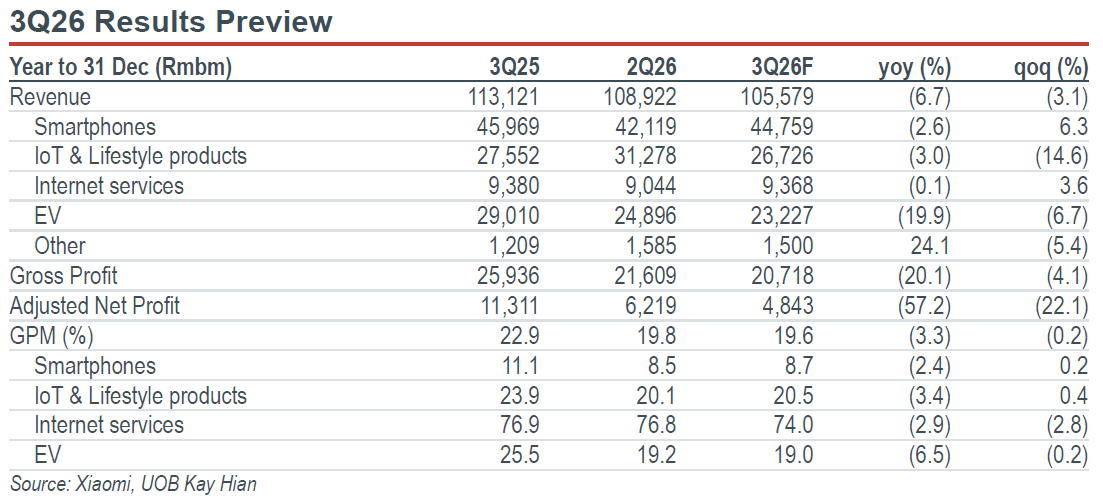
- We expect Xiaomi to register a 6.7% yoy and 3.1% qoq revenue decline in 3Q26. Gross margin should decline 3.3ppt yoy and 0.2ppt qoq to 19.6%, and adjusted net profit to fall 57.2% yoy and 22.1% qoq to Rmb4,843m.
- By segment, we expect smartphones to register resilient performance thanks to ASP hikes and mix improvements, while IoT and internet services are hit by weak spending and negative mix changes.
- Maintain HOLD with a lower target price of HK$25.90.
Analysis
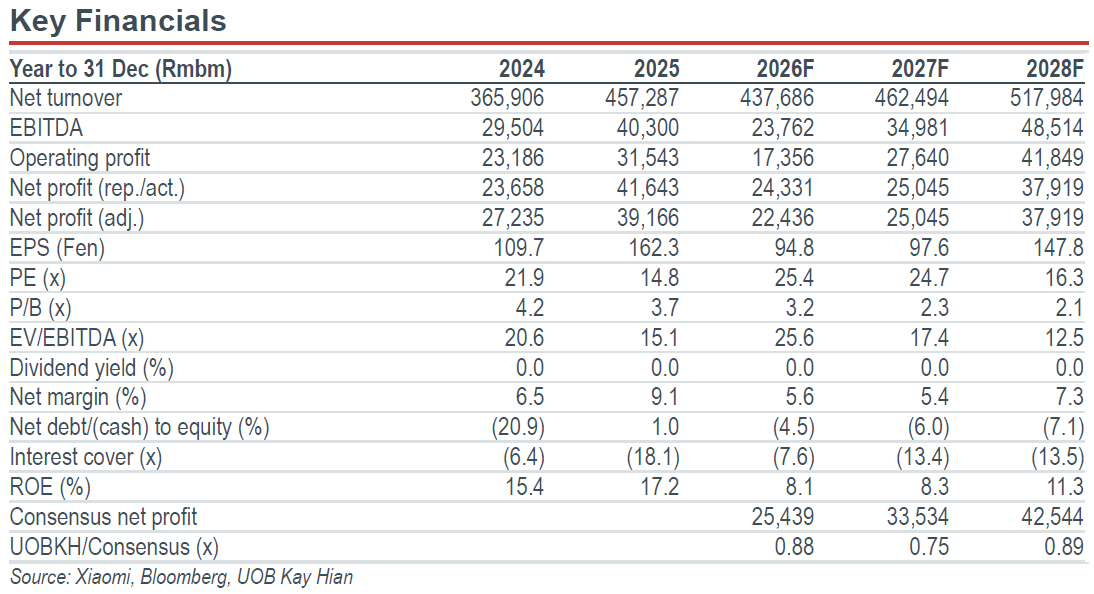
- 3Q26 results preview. We expect Xiaomi Corp’s (Xiaomi) 3Q26 revenue to decline 6.7% yoy and 3.1% qoq to Rmb106b, as weaker IoT and EV sales more than offset a stronger smartphone quarter. Blended gross margin is expected to decline 3.3ppt yoy and 0.2ppt qoq to 19.6%, and adjusted net profit is estimated to decline 57.2% yoy and 22.1% qoq to Rmb4,843m. Our 2026 adjusted net profit estimate is now 11.8% below Bloomberg consensus.
- Smartphone revenue rises sequentially on a higher ASP. According to Omdia, Xiaomi’s smartphone shipment declined 29% yoy and 2% qoq to 30.7m units amid memory cost inflation, though its global share rose 1.0ppt qoq to 12%. However, we estimated that ASP rose 38.9% yoy and 8.0% qoq to Rmb1,458 as Xiaomi continues to raise prices and shift toward premium models, lifting revenue 6.3% qoq to Rmb44.8b, though still down 2.6% yoy. Gross margins are expected to decline 2.4ppt yoy but improve 0.2ppt qoq to 8.7%, as the better mix and higher ASP offset part of the memory cost hikes.
Highlights
- We expect Xiaomi to register a 6.7% yoy and 3.1% qoq revenue decline in 3Q26. Gross margin should decline 3.3ppt yoy and 0.2ppt qoq to 19.6%, and adjusted net profit to fall 57.2% yoy and 22.1% qoq to Rmb4,843m.
- By segment, we expect smartphones to register resilient performance thanks to ASP hikes and mix improvements, while IoT and internet services are hit by weak spending and negative mix changes.
- Maintain HOLD with a lower target price of HK$25.90.
Analysis
- 3Q26 results preview. We expect Xiaomi Corp’s (Xiaomi) 3Q26 revenue to decline 6.7% yoy and 3.1% qoq to Rmb106b, as weaker IoT and EV sales more than offset a stronger smartphone quarter. Blended gross margin is expected to decline 3.3ppt yoy and 0.2ppt qoq to 19.6%, and adjusted net profit is estimated to decline 57.2% yoy and 22.1% qoq to Rmb4,843m. Our 2026 adjusted net profit estimate is now 11.8% below Bloomberg consensus.
- Smartphone revenue rises sequentially on a higher ASP. According to Omdia, Xiaomi’s smartphone shipment declined 29% yoy and 2% qoq to 30.7m units amid memory cost inflation, though its global share rose 1.0ppt qoq to 12%. However, we estimated that ASP rose 38.9% yoy and 8.0% qoq to Rmb1,458 as Xiaomi continues to raise prices and shift toward premium models, lifting revenue 6.3% qoq to Rmb44.8b, though still down 2.6% yoy. Gross margins are expected to decline 2.4ppt yoy but improve 0.2ppt qoq to 8.7%, as the better mix and higher ASP offset part of the memory cost hikes.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$26.48
HK$25.90
-2.2%
HK$26.20
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


