
Company Coverage
WuXi Biologics (Cayman) (2269 HK): 1H26: Exceeds Expectations; Robust Demand Fuels Accelerated Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$52.20
HK$67.80
+29.9%
HK$45.00
Analyst
Analyst
Highlights
WuXi Bio’s 1H26 revenue rose 18.4% yoy to Rmb11.79b, ahead of its 13 17% full-year growth guidance, and adjusted net profit attributable to shareholders jumped 38.4% yoy to Rmb3.31b, beating market estimates.
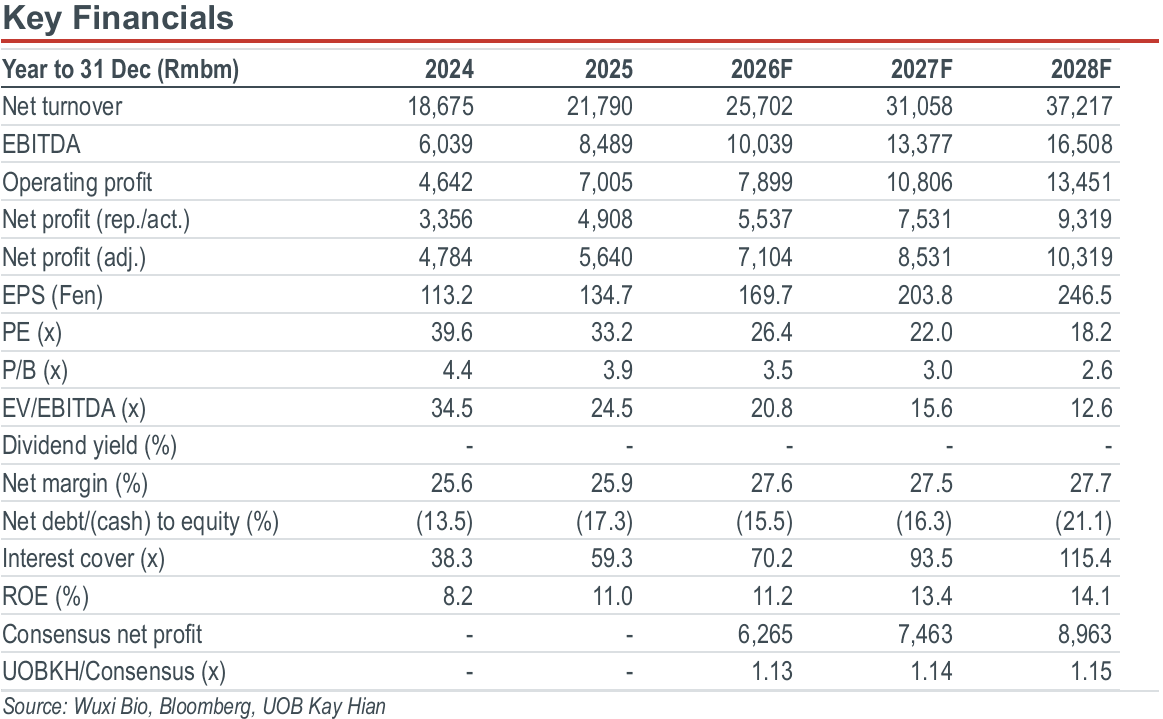
On the back of the robust growth in backlog and expanding production capacity, the company has raised its 2026 revenue growth to 15-18% yoy, and expects total revenue to accelerate to 20% CAGR for the next three years.
Maintain BUY and raise target price to HK$67.80, reflecting its stronger-than expected growth momentum.
Analysis
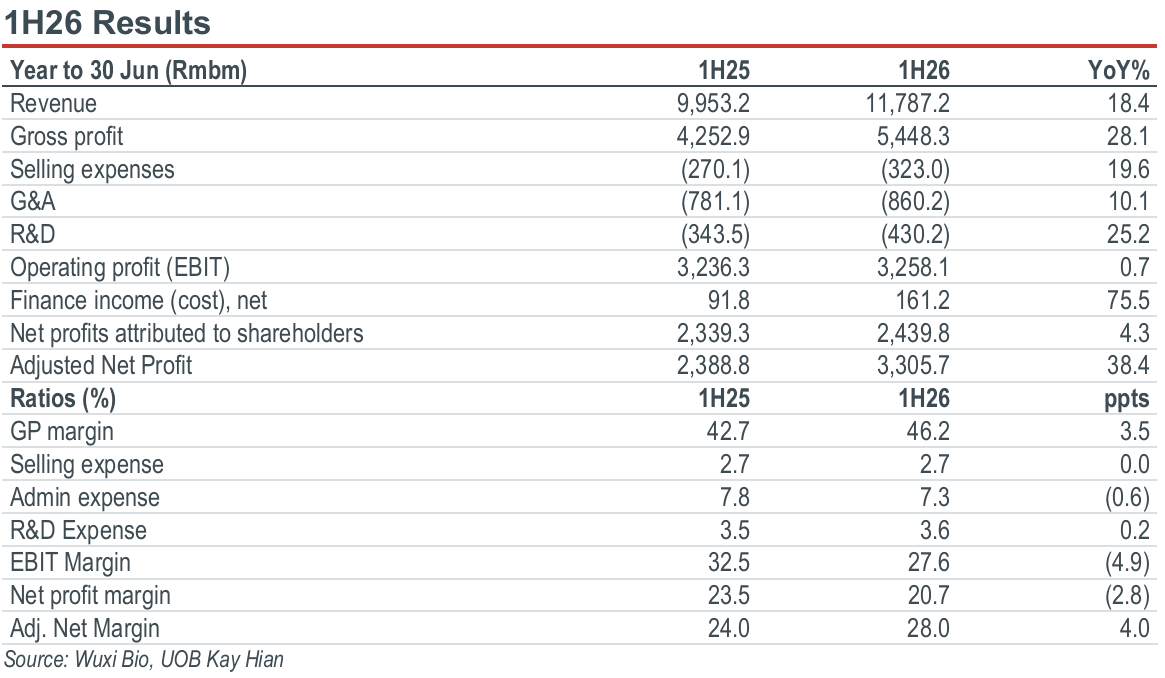
1H26 results above expectations. WuXi Biologics (Cayman)’s (WuXi Bio) 1H26 revenue rose 18.4% yoy to Rmb11.79b and gross profit increased 28.1% yoy to Rmb5.45b. Adjusted net profit attributable to shareholders rose 38.4% yoy to Rmb3.31b, lifting adjusted net margin by 4.0ppt yoy to 28.0%.
Highlights
WuXi Bio’s 1H26 revenue rose 18.4% yoy to Rmb11.79b, ahead of its 13 17% full-year growth guidance, and adjusted net profit attributable to shareholders jumped 38.4% yoy to Rmb3.31b, beating market estimates.
On the back of the robust growth in backlog and expanding production capacity, the company has raised its 2026 revenue growth to 15-18% yoy, and expects total revenue to accelerate to 20% CAGR for the next three years.
Maintain BUY and raise target price to HK$67.80, reflecting its stronger-than expected growth momentum.
Analysis
1H26 results above expectations. WuXi Biologics (Cayman)’s (WuXi Bio) 1H26 revenue rose 18.4% yoy to Rmb11.79b and gross profit increased 28.1% yoy to Rmb5.45b. Adjusted net profit attributable to shareholders rose 38.4% yoy to Rmb3.31b, lifting adjusted net margin by 4.0ppt yoy to 28.0%.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$52.20
HK$67.80
+29.9%
HK$45.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

8 Oct 2026
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales

29 Sept 2026