Company Coverage
Tsingtao Brewery (168 HK): 2Q26: Net Profit In Line; Sales Volume Down 7% With Flat ASP
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$42.86
HK$62.40
+45.6%
HK$66.70
Analyst
Analyst
Highlights
- Tsingtao Brewery’s 2Q26 earnings were in line with consensus estimates.
- In 2Q26, beer sales volume was 23.0m hl (-7% yoy). By brand, sales volume of the Tsingtao brand/secondary brand was 13.3m hl/9.7m hl (-1%/-14% yoy), respectively. By category, sales volume of mid-range to high-end/other products was 10.0m hl/13.0m hl (+2%/-13% yoy), respectively.
- Product mix continued to improve yoy, with mid-range to high-end products accounting for 44% of 2Q26 sales volume (vs 40% in 2Q25). However, ASP remained largely flat yoy. Maintain BUY, cut target price by 6% to HK$62.40.
Analysis
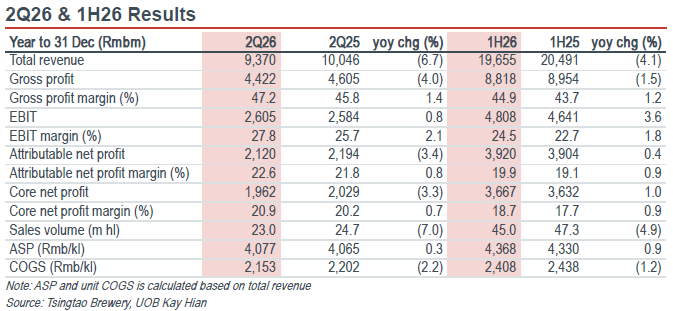
- 2Q26 net profit in line. Tsingtao Brewery reported 1H26 revenue of Rmb19,655m (-4% yoy). Gross margin was 44.9% (+1.2ppt yoy). EBIT
totalled Rmb4,808m (+4% yoy), and EBIT margin was 24.5% (+1.8ppt yoy). Net profit was Rmb3,920m (flat yoy), in line with VA consensus. Net margin was 19.9% (+0.9ppt yoy).
- This implies that in 2Q26, revenue was Rmb9,370m (-7% yoy). Gross margin was 47.2% (+1.4ppt yoy), supported by a 2% yoy decline in unit COGS. EBIT was Rmb2,605m (+1% yoy), and EBIT margin was 27.8% (+2.1ppt yoy), driven by: a) gross margin expansion; and b) a 0.9ppt decline in selling expenses, partially offset by a 0.2ppt increase in administrative and R&D expenses. Net profit was Rmb2,120m (-3% yoy), and net margin was 22.6% (+0.8ppt yoy).
Highlights
- Tsingtao Brewery’s 2Q26 earnings were in line with consensus estimates.
- In 2Q26, beer sales volume was 23.0m hl (-7% yoy). By brand, sales volume of the Tsingtao brand/secondary brand was 13.3m hl/9.7m hl (-1%/-14% yoy), respectively. By category, sales volume of mid-range to high-end/other products was 10.0m hl/13.0m hl (+2%/-13% yoy), respectively.
- Product mix continued to improve yoy, with mid-range to high-end products accounting for 44% of 2Q26 sales volume (vs 40% in 2Q25). However, ASP remained largely flat yoy. Maintain BUY, cut target price by 6% to HK$62.40.
Analysis
- 2Q26 net profit in line. Tsingtao Brewery reported 1H26 revenue of Rmb19,655m (-4% yoy). Gross margin was 44.9% (+1.2ppt yoy). EBIT
totalled Rmb4,808m (+4% yoy), and EBIT margin was 24.5% (+1.8ppt yoy). Net profit was Rmb3,920m (flat yoy), in line with VA consensus. Net margin was 19.9% (+0.9ppt yoy).
- This implies that in 2Q26, revenue was Rmb9,370m (-7% yoy). Gross margin was 47.2% (+1.4ppt yoy), supported by a 2% yoy decline in unit COGS. EBIT was Rmb2,605m (+1% yoy), and EBIT margin was 27.8% (+2.1ppt yoy), driven by: a) gross margin expansion; and b) a 0.9ppt decline in selling expenses, partially offset by a 0.2ppt increase in administrative and R&D expenses. Net profit was Rmb2,120m (-3% yoy), and net margin was 22.6% (+0.8ppt yoy).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$42.86
HK$62.40
+45.6%
HK$66.70
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

8 Oct 2026
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales

12 Oct 2026
Xiaomi Corp (1810 HK): SKYNOAD’s Locked Orders Surpass 70,000 Units
Our latest research
16 Oct 2026
TA: SITC International (1308 HK) / China Hongqiao Group (1378 HK)
15 Oct 2026
TA: Lenovo Group (0992 HK) / SHEIN Global (0625 HK)
14 Oct 2026