
Company Coverage
China State Construction Engineering Corporation (601668 CH) - 9M26: Net Profit Down 27.4%; Committed To Stable DPS
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb4.65
Rmb4.88
+5.0%
Rmb4.90
Analyst
Analyst
Highlights
- 9M26 attributable net profit fell 24.8% yoy to Rmb28.7b on lower revenue and higher R&D, SG&A and impairment cost ratios. The construction segment improved with margin expansion and a return to order growth in 3Q26.
- Management reiterates targets of stable DPS, higher positive OCF and stable impairment for 2026. The stake purchase programme will continue.
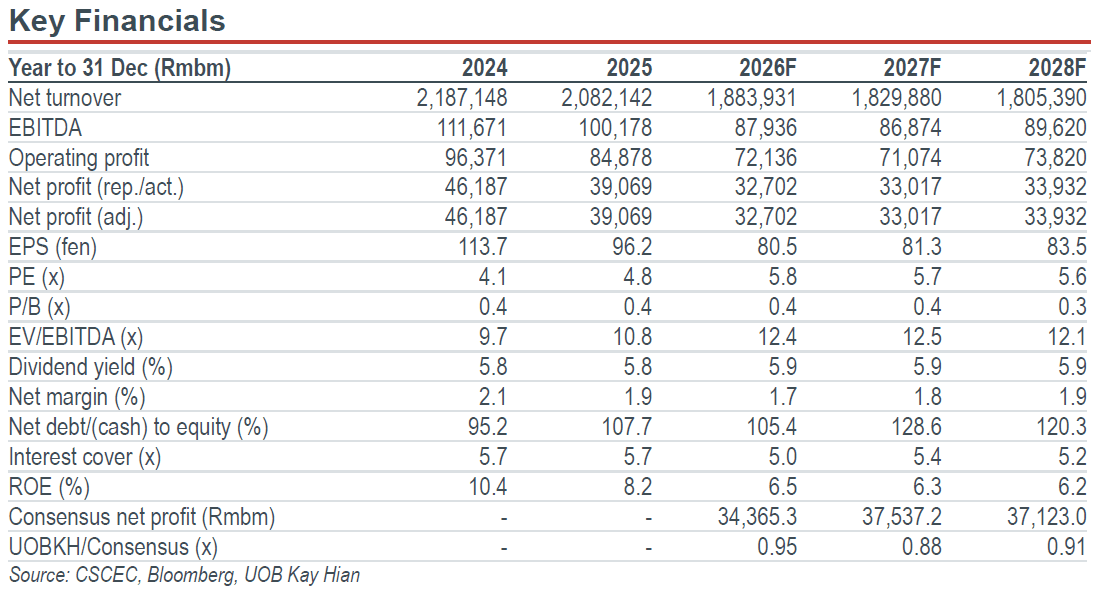
- Maintain HOLD with a largely unchanged target price of Rmb4.88.
Analysis
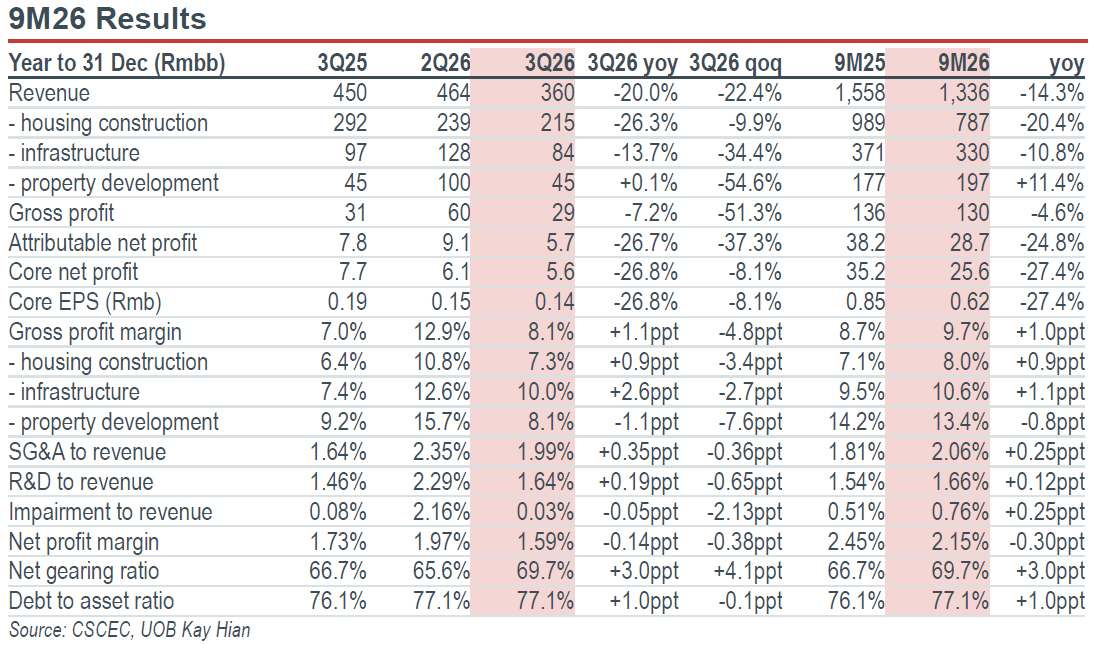
Net profit fell 24.8% yoy in 9M26 and 26.7% in 3Q26. China State Construction Engineering Corporation's (CSCEC) 9M26 attributable net profit declined 24.8% yoy to Rmb28.7b, and 3Q26 attributable net profit fell 26.7% yoy to Rmb5.7b. 3Q26 revenue dropped 20.0% yoy, led by housing construction. Gross profit margin rose 1.0ppt yoy to 9.7% in 9M26, supported by margin improvement of housing and infrastructure construction. However, impairment/SG&A/R&D to revenue ratios rose 0.25ppt/0.25ppt/0.12ppt yoy respectively, resulting in 0.3ppt yoy decline in net margin. Net gearing rose 3.0ppt yoy to 69.7% as of Sep 26..
Highlights
- 9M26 attributable net profit fell 24.8% yoy to Rmb28.7b on lower revenue and higher R&D, SG&A and impairment cost ratios. The construction segment improved with margin expansion and a return to order growth in 3Q26.
- Management reiterates targets of stable DPS, higher positive OCF and stable impairment for 2026. The stake purchase programme will continue.
- Maintain HOLD with a largely unchanged target price of Rmb4.88.
Analysis
Net profit fell 24.8% yoy in 9M26 and 26.7% in 3Q26. China State Construction Engineering Corporation's (CSCEC) 9M26 attributable net profit declined 24.8% yoy to Rmb28.7b, and 3Q26 attributable net profit fell 26.7% yoy to Rmb5.7b. 3Q26 revenue dropped 20.0% yoy, led by housing construction. Gross profit margin rose 1.0ppt yoy to 9.7% in 9M26, supported by margin improvement of housing and infrastructure construction. However, impairment/SG&A/R&D to revenue ratios rose 0.25ppt/0.25ppt/0.12ppt yoy respectively, resulting in 0.3ppt yoy decline in net margin. Net gearing rose 3.0ppt yoy to 69.7% as of Sep 26..
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb4.65
Rmb4.88
+5.0%
Rmb4.90
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Inner Mongolia Yili Industrial Group (600887 CH) - 3Q26: Revenue Misses But Operating Margin Expansion Continues; Reiterates MSD Revenue Growth Target For 2026

2 Nov 2026
Kweichow Moutai (600519 CH) - 3Q26: Results In Line; Direct Sales Up 40% On i-Moutai Growth

2 Nov 2026
Estun Automation (002747 CH) - 3Q26: Mixed Quarter But Profitability Improvements Ahead of Expectations
Our latest research
3 Nov 2026
TA: Nongfu Spring (9633 HK) / Xiaomi (1810 HK)

2 Nov 2026
China Tourism Group Duty Free (601888 CH) - 3Q26: Results Miss Expectations
2 Nov 2026