

Company Coverage
Ningbo Joyson Electronic Corporation (600699 CH): 3Q26: Results Miss On Top-Line; Downgrade to HOLD
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Rmb21.87
Rmb19.00
-13.1%
Rmb25.00
Analyst
Highlights
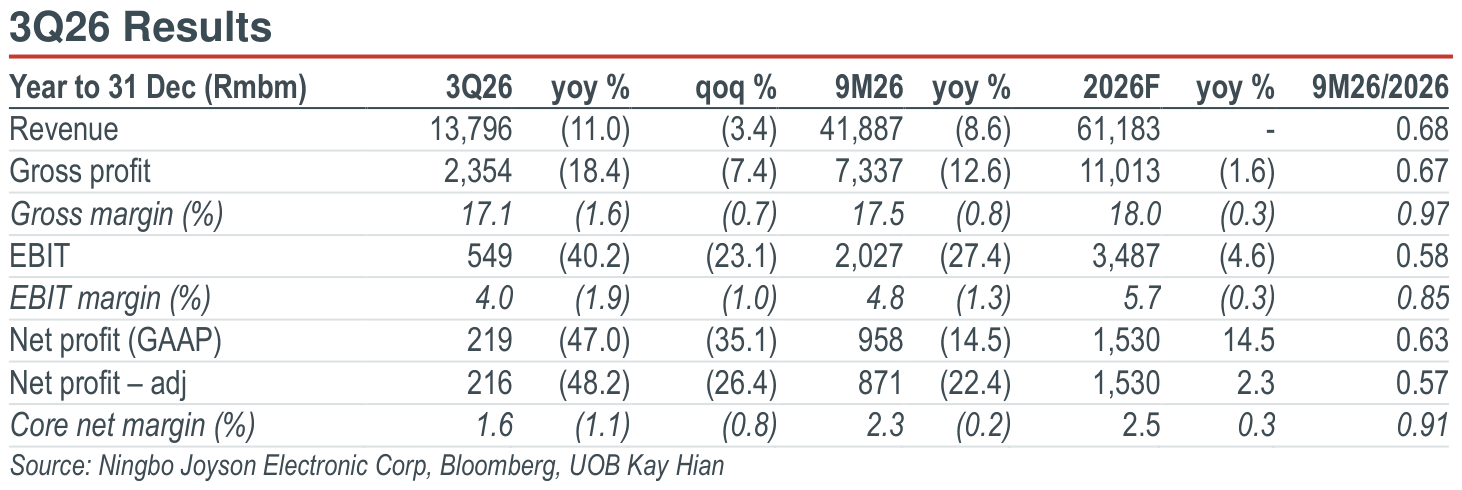
- 3Q26 net profit misses estimates at Rmb219m (-47% yoy/-35% qoq) due to renminbi appreciation, business disposal, and chip cost hikes.
- Order flows slowed in 9M26 with new-order backlog of only Rmb61.5b (-13.9% yoy). Forward revenue will be driven by smart-driving programs entering mass production, likely global-OEM awards, robot-component deliveries, and AIDC power commercialisation.
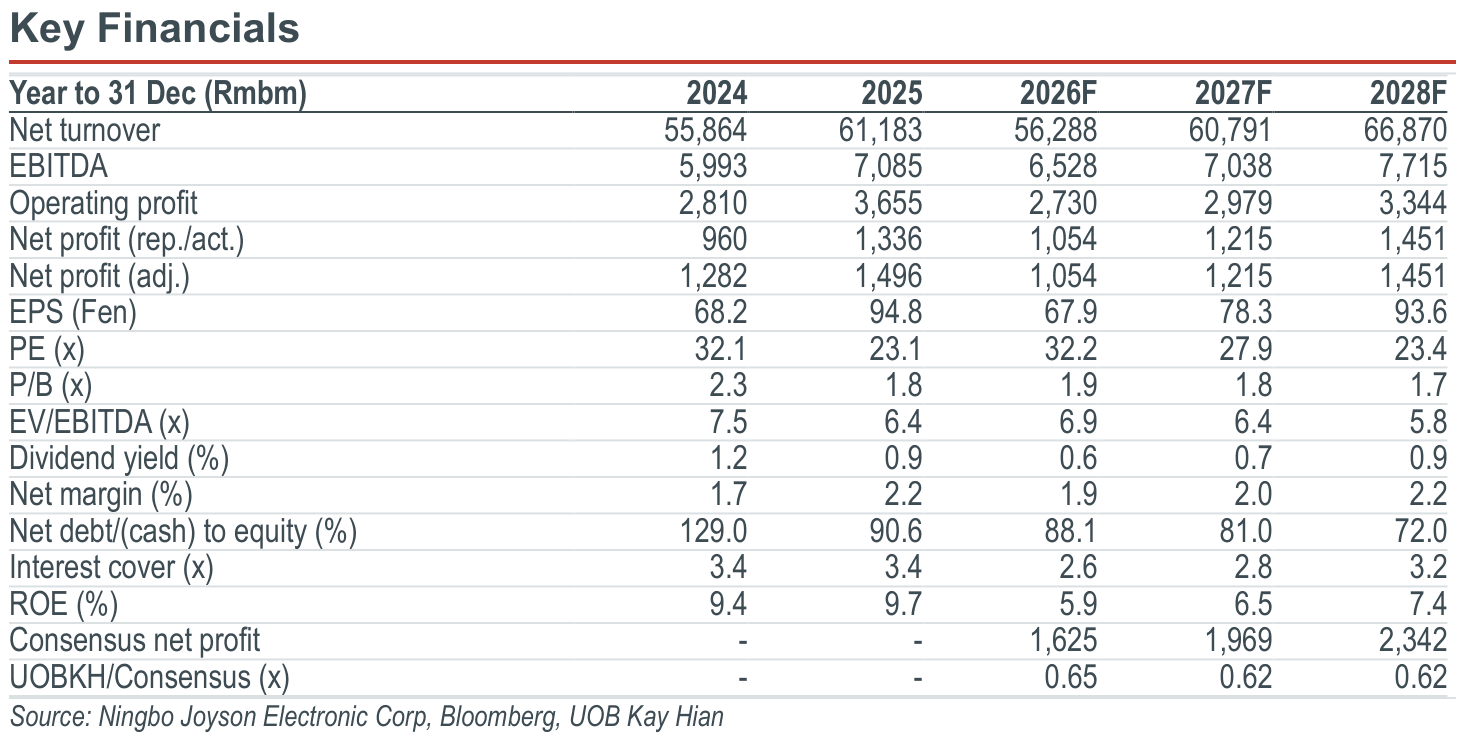
- We cut our 2026-28 net profit forecasts by 31%/29%/26% on lower revenue and gross margin.
- Downgrade from BUY to HOLD and cut our target price to Rmb19.00.
Analysis
- 3Q26 net profit missed our estimates at Rmb219m (-47% yoy/-35% qoq), bringing 9M26 net profit to Rmb958m (-14.5% yoy), 63% of our previous full-year estimate. The earnings miss comes from both top-line and margins. - Yoy revenue drop expanded to 11%, worse than expected on forex and business disposal. Revenue dropped 11% yoy and 3% qoq to Rmb13.8b in 3Q26, and by 8.6% yoy to Rmb41.89b (68% of our full-year estimate). The revenue miss stems from renminbi appreciation (overseas revenue is settled in foreign currencies), and its subsidiary Senssun’s disposal of a business. Stripping them off, revenue fell 4% yoy to Rmb44b in 9M26 (in line with global auto sales drop), implying 3Q26 revenue of Rmb15.9b (+3% yoy/+12% qoq). - Gross margin squeezed by cost hikes. Gross margin dropped to 17.1% (-1.6ppt yoy/-0.7ppt qoq) in 3Q26 and 17.5% (-0.8ppt yoy) in 9M26, below our full-year assumption of 18.0%, due to the price hikes of chips, electronic components like PCBs, and energy costs.
Highlights
- 3Q26 net profit misses estimates at Rmb219m (-47% yoy/-35% qoq) due to renminbi appreciation, business disposal, and chip cost hikes.
- Order flows slowed in 9M26 with new-order backlog of only Rmb61.5b (-13.9% yoy). Forward revenue will be driven by smart-driving programs entering mass production, likely global-OEM awards, robot-component deliveries, and AIDC power commercialisation.
- We cut our 2026-28 net profit forecasts by 31%/29%/26% on lower revenue and gross margin.
- Downgrade from BUY to HOLD and cut our target price to Rmb19.00.
Analysis
- 3Q26 net profit missed our estimates at Rmb219m (-47% yoy/-35% qoq), bringing 9M26 net profit to Rmb958m (-14.5% yoy), 63% of our previous full-year estimate. The earnings miss comes from both top-line and margins. - Yoy revenue drop expanded to 11%, worse than expected on forex and business disposal. Revenue dropped 11% yoy and 3% qoq to Rmb13.8b in 3Q26, and by 8.6% yoy to Rmb41.89b (68% of our full-year estimate). The revenue miss stems from renminbi appreciation (overseas revenue is settled in foreign currencies), and its subsidiary Senssun’s disposal of a business. Stripping them off, revenue fell 4% yoy to Rmb44b in 9M26 (in line with global auto sales drop), implying 3Q26 revenue of Rmb15.9b (+3% yoy/+12% qoq). - Gross margin squeezed by cost hikes. Gross margin dropped to 17.1% (-1.6ppt yoy/-0.7ppt qoq) in 3Q26 and 17.5% (-0.8ppt yoy) in 9M26, below our full-year assumption of 18.0%, due to the price hikes of chips, electronic components like PCBs, and energy costs.
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Rmb21.87
Rmb19.00
-13.1%
Rmb25.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
Huizhou Desay SV (002920 CH): 3Q26: Revenue Growth Accelerates To 24%, But Earnings Miss On Subsidy Cuts, Credit Provisions, Associates’ Losses, And Tax Hikes

27 Oct 2026


