

Company Coverage
CSPC Pharmaceutical Group (1093 HK): 1H26: Results Beat; Out-licensing Income Boosts Earnings Growth
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
HK$9.52
HK$11.50
+20.8%
HK$6.00
Analyst
Analyst
Highlights
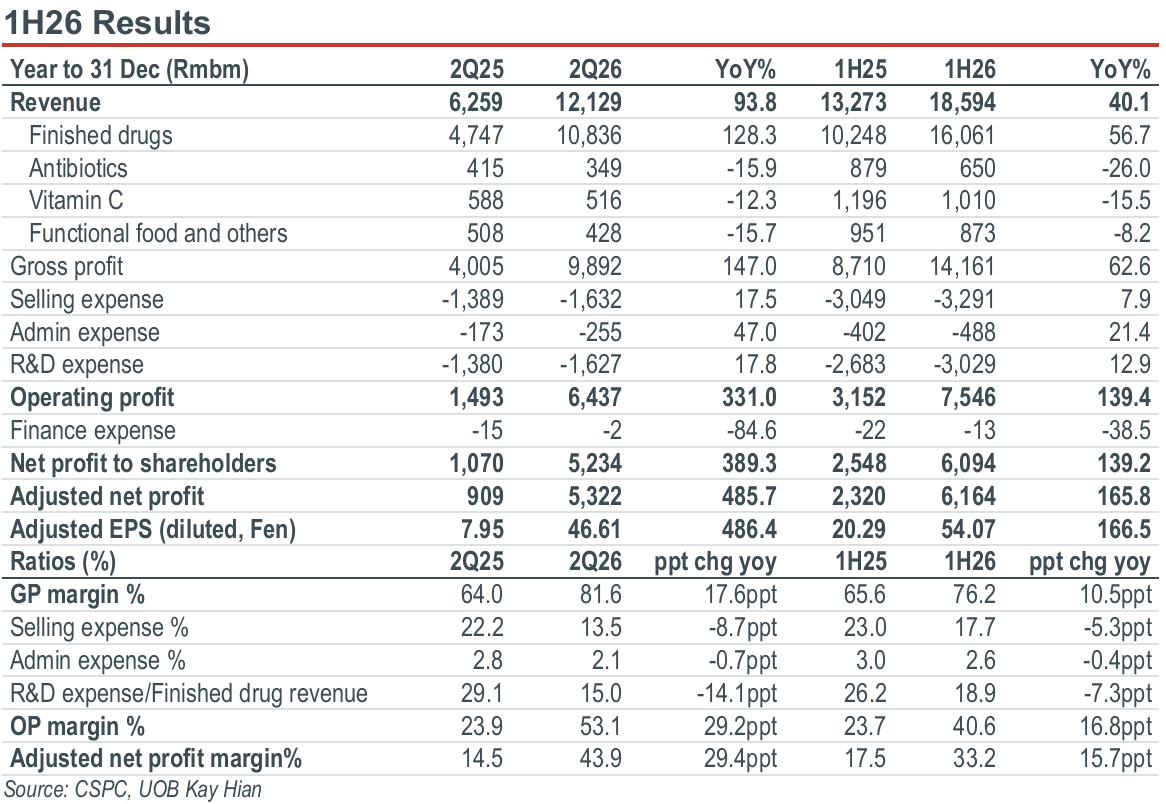
CSPC’s 1H26 revenue rose 40.1% yoy to Rmb18.6b and underlying net profit jumped 165.8% yoy to Rmb6.2b, well above our full-year growth estimates. Licence fee income surged 448.5% yoy to Rmb5.9b, serving as the key growth driver.
CSPC expects its growth momentum to continue over the next five years, driven by rising out-licensing income and new product launches, with over 30 new product/indication approvals targeted in the next three years.
Upgrade to BUY with a higher target price of HK$11.50.
Analysis
1H26 results beat. CSPC Pharmaceutical Group’s (CSPC) 1H26 revenue rose 40.1% yoy to Rmb18.6b and underlying net profit jumped 165.8% yoy to Rmb6.2b on Rmb5.9b of licence fee income. Interim dividend amounted to 18 HK cents, up 28.5% yoy.
Highlights
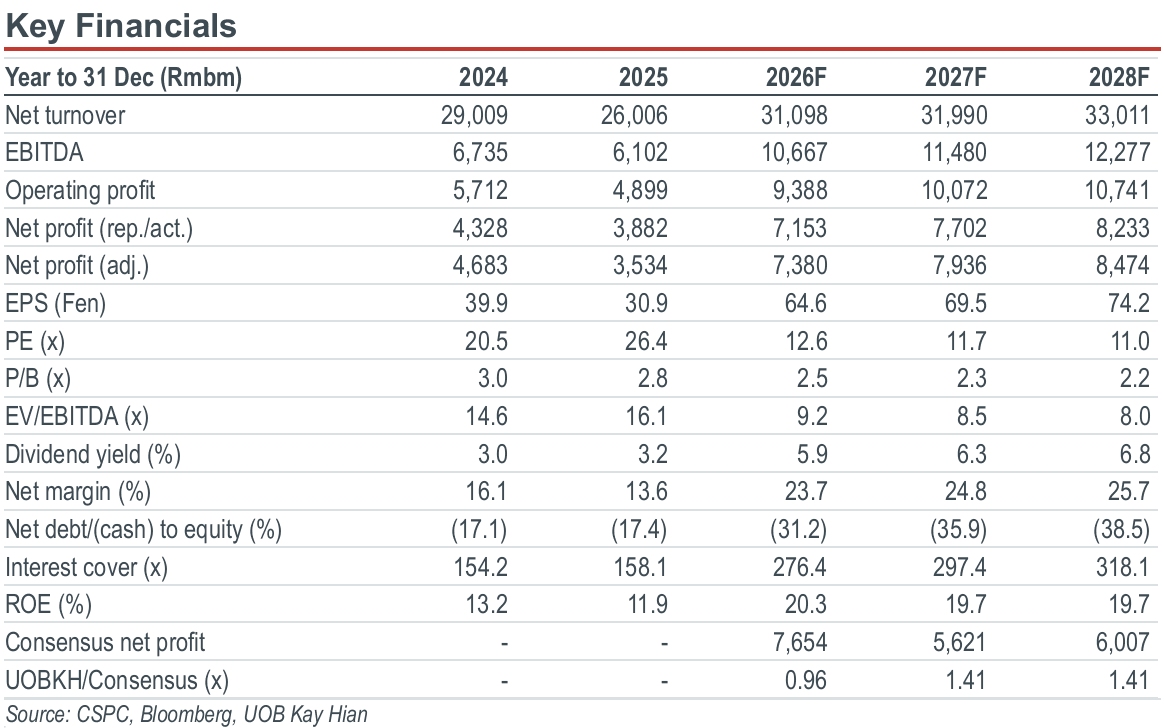
CSPC’s 1H26 revenue rose 40.1% yoy to Rmb18.6b and underlying net profit jumped 165.8% yoy to Rmb6.2b, well above our full-year growth estimates. Licence fee income surged 448.5% yoy to Rmb5.9b, serving as the key growth driver.
CSPC expects its growth momentum to continue over the next five years, driven by rising out-licensing income and new product launches, with over 30 new product/indication approvals targeted in the next three years.
Upgrade to BUY with a higher target price of HK$11.50.
Analysis
1H26 results beat. CSPC Pharmaceutical Group’s (CSPC) 1H26 revenue rose 40.1% yoy to Rmb18.6b and underlying net profit jumped 165.8% yoy to Rmb6.2b on Rmb5.9b of licence fee income. Interim dividend amounted to 18 HK cents, up 28.5% yoy.
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
HK$9.52
HK$11.50
+20.8%
HK$6.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Inner Mongolia Yili Industrial Group (600887 CH) - 3Q26: Revenue Misses But Operating Margin Expansion Continues; Reiterates MSD Revenue Growth Target For 2026

2 Nov 2026
Kweichow Moutai (600519 CH) - 3Q26: Results In Line; Direct Sales Up 40% On i-Moutai Growth

2 Nov 2026
Estun Automation (002747 CH) - 3Q26: Mixed Quarter But Profitability Improvements Ahead of Expectations
Our latest research

19 Nov 2026
CSPC Pharmaceutical Group (1093 HK): 9M26: Results Beat; Targets Positive Revenue Growth In 2027

19 Nov 2026
Tencent Holdings (700 HK): 3Q26: Higher AI Costs Result In Operating Profit Miss and Weigh on FCF
19 Nov 2026