

Analyst
Analyst
August Loans Growth Falls Below 5%
- August's M1 growth edged up to 4.1% yoy (+0.1ppt mom), in line with Bloomberg's consensus estimate, while M2 growth eased to 7.5% yoy (-0.2ppt mom), slightly below consensus of 7.6% yoy and a third straight month of deceleration.
- New bank loans turned positive at Rmb0.06t from July's -Rmb0.34t but missed consensus of Rmb0.40t and were well below Aug 25's Rmb0.59t. New TSF of Rmb1.66t also fell short of the Rmb2.12t consensus, with new government bond issuance easing to Rmb1.01t (-Rmb0.31t mom).
- Outstanding bank loans growth fell to 4.9% yoy (-0.2ppt mom), dropping below 5% for the first time, while outstanding TSF growth eased to 7.2% yoy (-0.2ppt mom). With the recent push for faster FAI project implementation, new corporate loans may pick up in the coming months.
Our View
- M2 growth eased by 0.2ppt to 7.5% yoy in Aug 26, slightly below Bloomberg's consensus forecast of 7.6% yoy and extending the deceleration to a third consecutive month. M1 money supply growth edged up to 4.1% yoy from 4.0% yoy in July, matching market expectation, while M0 growth moderated to 11.2% yoy (-0.4ppt mom). M1 has now held in a narrow 4.0-4.1% range for three months, a slight positive as it stabilised at a subdued level rather than beginning to recover.
- Banks added Rmb0.06t in new loans in Aug 26, returning to positive territory after July's Rmb0.34t net repayment but falling short of Bloomberg's consensus estimate of Rmb0.40t and the Rmb0.59t recorded in Aug 25. New household loans stayed negative at -Rmb0.20t (+Rmb0.26t mom), with both short-term and long-term borrowing still contracting for a second month. New corporate and government loans turned positive at Rmb0.22t (+Rmb0.32t mom), driven entirely by medium-to-long-term lending of Rmb0.32t (+Rmb0.55t mom) as short-term loans remained in negative territory at -Rmb0.16t.
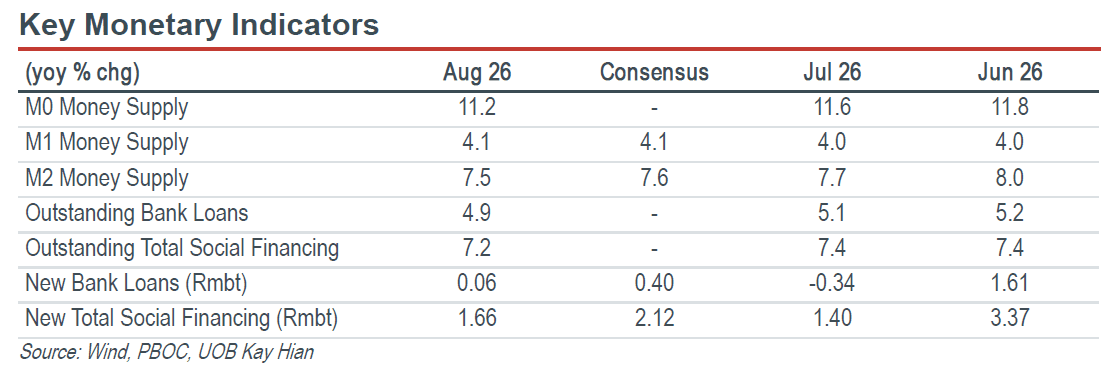
- Aug 26's new TSF rose to Rmb1.66t from Jul 26's Rmb1.40t, but missed Bloomberg's consensus of Rmb2.12t and was materially below Aug 25's Rmb2.57t. Renminbi loans within TSF recovered to Rmb0.06t (+Rmb0.65t mom) but contributed little, while new government bond issuance fell to Rmb1.01t (-Rmb0.31t mom), taking the growth rate down to 13.5% yoy (-0.6ppt mom). Corporate bond growth accelerated to 9.7% yoy (+0.5ppt mom) and equity issuance rose to 5.7% yoy (+0.2ppt mom), consistent with the continued shift towards non-bank channels. However, the shadow financing leg was uneven, with bank acceptances reversing to -5.1% yoy (-7.8ppt mom) and trust loan growth slowing to 1.9% yoy (-1.3ppt mom).
August Loans Growth Falls Below 5%
- August's M1 growth edged up to 4.1% yoy (+0.1ppt mom), in line with Bloomberg's consensus estimate, while M2 growth eased to 7.5% yoy (-0.2ppt mom), slightly below consensus of 7.6% yoy and a third straight month of deceleration.
- New bank loans turned positive at Rmb0.06t from July's -Rmb0.34t but missed consensus of Rmb0.40t and were well below Aug 25's Rmb0.59t. New TSF of Rmb1.66t also fell short of the Rmb2.12t consensus, with new government bond issuance easing to Rmb1.01t (-Rmb0.31t mom).
- Outstanding bank loans growth fell to 4.9% yoy (-0.2ppt mom), dropping below 5% for the first time, while outstanding TSF growth eased to 7.2% yoy (-0.2ppt mom). With the recent push for faster FAI project implementation, new corporate loans may pick up in the coming months.
Our View
- M2 growth eased by 0.2ppt to 7.5% yoy in Aug 26, slightly below Bloomberg's consensus forecast of 7.6% yoy and extending the deceleration to a third consecutive month. M1 money supply growth edged up to 4.1% yoy from 4.0% yoy in July, matching market expectation, while M0 growth moderated to 11.2% yoy (-0.4ppt mom). M1 has now held in a narrow 4.0-4.1% range for three months, a slight positive as it stabilised at a subdued level rather than beginning to recover.
- Banks added Rmb0.06t in new loans in Aug 26, returning to positive territory after July's Rmb0.34t net repayment but falling short of Bloomberg's consensus estimate of Rmb0.40t and the Rmb0.59t recorded in Aug 25. New household loans stayed negative at -Rmb0.20t (+Rmb0.26t mom), with both short-term and long-term borrowing still contracting for a second month. New corporate and government loans turned positive at Rmb0.22t (+Rmb0.32t mom), driven entirely by medium-to-long-term lending of Rmb0.32t (+Rmb0.55t mom) as short-term loans remained in negative territory at -Rmb0.16t.
- Aug 26's new TSF rose to Rmb1.66t from Jul 26's Rmb1.40t, but missed Bloomberg's consensus of Rmb2.12t and was materially below Aug 25's Rmb2.57t. Renminbi loans within TSF recovered to Rmb0.06t (+Rmb0.65t mom) but contributed little, while new government bond issuance fell to Rmb1.01t (-Rmb0.31t mom), taking the growth rate down to 13.5% yoy (-0.6ppt mom). Corporate bond growth accelerated to 9.7% yoy (+0.5ppt mom) and equity issuance rose to 5.7% yoy (+0.2ppt mom), consistent with the continued shift towards non-bank channels. However, the shadow financing leg was uneven, with bank acceptances reversing to -5.1% yoy (-7.8ppt mom) and trust loan growth slowing to 1.9% yoy (-1.3ppt mom).
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Aug 2026
Zhejiang Sanhua Intelligent Controls Co (002050 CH): 2Q26: Core Earnings In Line; Reported Profit Misses On Forex Loss

26 Aug 2026
NAURA Technology Group (002371 CH): 2Q26: Uneventful Results But Order Momentum Continues To Accelerate

31 Aug 2026


