

Country Daily
China Economics PMI / China Healthcare Bi-weekly / Macau Gaming / New World Development
Analyst
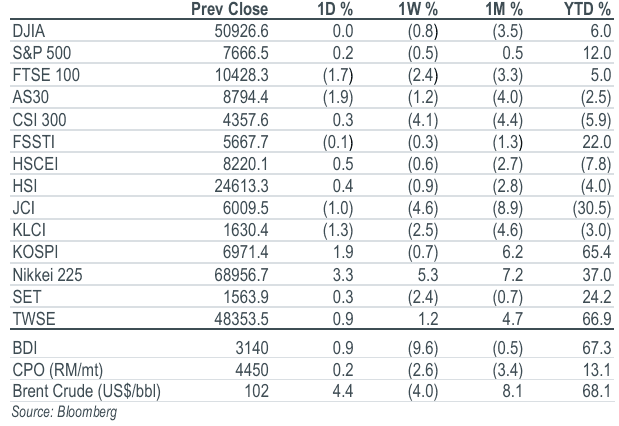
Key Indices
Top Stories
Economics | PMI
September's PMI was positive. Manufacturing PMI returned to expansion at 50.1 (+0.3ppt mom), in line with Bloomberg's consensus, but the gain was output-led as the new orders sub-index dipped slightly. Non-manufacturing PMI beat consensus at 50.2 (+1.2ppt mom), as the construction industry index rebounded from its cycle low into expansion, following heavy special bond issuance in August. The widening price gaps point to persistent margin pressure, while the PBOC's targeted easing should support activity in 4Q26.
Sector Update | China Healthcare
The HSHCI rose significantly by 8.5% during 16-30 September, supported by the strong healthcare market sentiment in both China and the overseas market. Akeso, Insilico, XtalPi, CSPC, WuXi Bio, and WuXi AppTec were the major outperformers. China's 15th Five-Year Plan for the pharmaceutical industry strikes a supportive tone for the long-term development of the broader biopharmaceutical sector. It also champions AI-enabled drug discovery and development – an area that has drawn growing investor interest in recent years. Maintain MARKET WEIGHT.
Sector Update | Macau Gaming
Macau’s Sep 26 GGR reached MOP18.1b, down 1% yoy and 17% mom. The figure missed market consensus by 3%, and recovered to 82% of 2019’s level. For 9M26, GGR rose 3% yoy to MOP187.1b. For 8M26, visitation rose 8% yoy to 29.0m, 6% above 2019’s level. For the Mid-Autumn Festival holiday, daily visitor arrivals fell 3% yoy to 138,300. The National Day holiday daily arrivals are expected to reach 150,000. Maintain OVERWEIGHT; top pick: Galaxy.
Company Results | New World Development (17 HK/HOLD/HK$6.05/Target:HK$6.44)
NWD's recurring operations earned HK$2.2b in FY26, against a loss of HK$1.2b a year earlier, as Hong Kong development and investment results rose over 7% and finance costs fell 14.9%. Provisions and impairments, mainly on 11 SKIES, widened the attributable loss to HK$28.2b. Net gearing rose 10.2ppt to 68.3% and cash fell 34.4%. The 11 SKIES exit ends a long-term rent obligation for a HK$2.3b fee. Maintain HOLD with a target price of HK$6.44, based on an 80% NAV discount.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


