
分析员
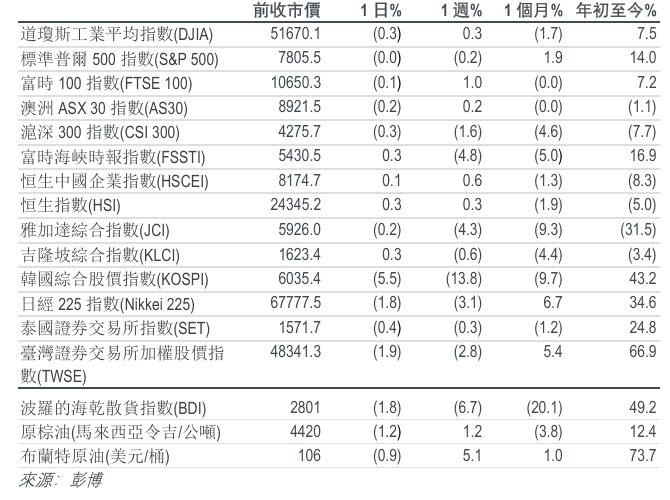
主要指数
焦点新闻
公司更新 | 京东集团(9618 HK/买入/港币104.9元/目标价:港币148元)
京东预计将于11月中旬公布其2026年第3季度业绩。 我们预测集团收入按年增长3.5%至人民币3,096亿元,大致符合市场预期,主要受惠于京东零售重回正增长。 零售业务的经营利润率按年应大致保持稳定,而外卖及京喜业务亏损收窄应可支持集团盈利复苏,惟京东持续拓展欧洲业务导致国际业务亏损温和增加,抵销了部分利好。 维持「买入」评级,目标价维持港币148元(美金38元)不变。
公司更新 | 联想集团(992 HK/买入/港币31.1元/目标价:港币49元)
IDC的2026年第3季度个人电脑初步出货量数据显示,联想的个人电脑出货量按年下跌22.6%,按季下跌10.2%至1,490万部,分别比我们及市场预测低8%及4%。业绩未达预期,主要是由于2026年上半年的提前备货效应强于预期,进而导致库存消化期间的出货量下降。我们相应下调对联想的个人电脑出货量预测,但亦预期平均售价上调将大致抵销出货量的任何不足。维持「买入」评级。目标价:港币49元。
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


