
Wealth Daily
Intel and Reddit Tumble as Chip Shares Slide
Today’s Must-Know News
Overnight Markets
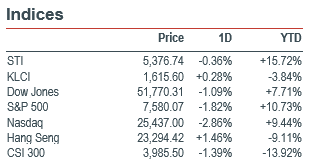
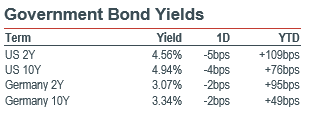
Market Movers: At the 30 October close, the S&P 500 fell 1.82% and the iShares Semiconductor ETF (SOXX US) lost 8.24%. Intel (INTC US) sank 28.58% in the first full session after it forecast 4Q revenue of US$15–16bn amid weak PC demand and a disruption at its Israeli factory. Reddit (RDDT US) fell 29.22% after warning that fewer search referrals could cut daily active users by a low-double-digit percentage if the trend persists. AstraZeneca (AZN.L) gained 6.96% as it projected US$1.5bn of annualised pre-tax savings to reinvest principally in its drug pipeline. (Reuters markets / Intel / Reuters on Intel / Reuters on Reddit / AstraZeneca / SOXX) iShares Semiconductor ETF (SOXX US) is our Investment Opportunity.
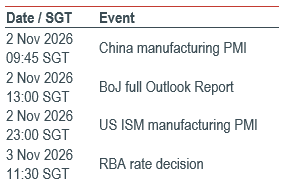
Macro: The BoJ held its policy rate at 1.25% by an 8–1 vote and will raise annual ETF sales from ¥330bn to ¥860bn at book value from January 2027. China’s manufacturing PMI fell from 50.1 to 49.30. New orders at 49.40 point to weaker factory demand. (BoJ / NBS)
Geopolitical: The FBI attributed the US$6.3bn Binance theft to North Korea. Binance resumed selected withdrawals on Sunday and said its replacement purchases covered about 95% of the loss. The pace of withdrawals will test customers’ confidence. (FBI / Reuters)
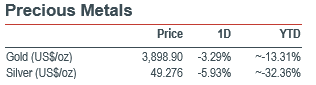
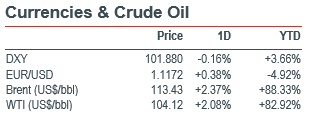
FICC: December gold and silver settled 3.29% and 5.93% lower, respectively. January Brent rose 2.37% to US$113.43/bbl and December WTI gained 2.08% to US$104.12/bbl on Friday. Seven OPEC+ members subsequently held December production targets steady, leaving actual shipments sensitive to passage through Hormuz. (AP / QNA / OPEC)
AI
• Amazon slips despite stronger AWS growth. Amazon (AMZN US) shares fell 1.41% in the first cash session after results. AWS sales rose 39% YoY to US$46.0bn, while trailing annual free cash flow turned negative at US$42.4bn. The US$240–247bn holiday sales forecast leaves limited room for retail weakness as infrastructure spending consumes cash. (Amazon / Reuters / Market data) Amazon (AMZN US) is our Core Recommendation.
• Intel triggers a semiconductor sell-off. Intel (INTC US) shares fell 28.58% after Intel forecast fourth-quarter revenue of US$15–16bn and adjusted EPS of US$0.25. Third-quarter sales rose 21% YoY to US$16.5bn. The guidance disappointment hit peers too, with the Philadelphia Semiconductor Index down 7.20%, highlighting the sector’s exposure to slowing PC demand. (Intel / Reuters / Reuters / Market data)
• Nvidia weighs backing a customer’s borrowing. Nvidia (NVDA US) is reportedly in talks over billions of dollars in credit guarantees for Nscale’s West Virginia data centre, according to Reuters, citing The Information. Anthropic previously agreed to rent US$45bn of computing capacity there. A guarantee would expose Nvidia to customer financing risk. Terms remain unsigned. (Reuters / TechCrunch) Nvidia (NVDA US) is our Core Recommendation.
• AI search threatens Reddit referral traffic. Reddit (RDDT US) shares fell 29.22% despite quarterly revenue rising 53% YoY to US$895m. Weekly search referrals fell by more than one million on average in October. If that pace persists, management said fourth-quarter daily active uniques could fall by a low-double-digit percentage from roughly 130m. (Reddit / Reuters / Market data)
Americas
• ExxonMobil converts refining strength into cash. ExxonMobil (XOM US) reported the third-quarter earnings rose 104% YoY to US$15.4bn and free cash flow was US$19.1bn. Nine-month earnings rose 53% YoY to US$34.1bn. Management expects US$20bn of repurchases next year. Refining earnings exceeded upstream earnings, increasing sensitivity to fuel margins as damaged capacity returns to service. (ExxonMobil / ExxonMobil 2025 / Reuters)
• Sandisk slides despite a flash-storage boom. Sandisk (SNDK US) shares fell 13.47% in the first cash session after results. Fiscal first-quarter revenue rose 378% YoY to US$11.03bn. Data-centre revenue reached US$4.80bn versus US$269m a year earlier. Peer pricing commentary put the durability of those gains in focus despite strong demand. (Sandisk / Reuters / Investing.com / Market data)
• Chevron uses stronger earnings to reduce debt. Chevron (CVX US) reported the third-quarter net income reached US$9.92bn from US$3.54bn a year earlier. U.S. refinery throughput hit a record 1.09m barrels per day and net debt fell US$7.8bn during the quarter. A stronger balance sheet gives Chevron room to absorb a reversal in refining margins. (Chevron / Reuters)
• AbbVie raises its profit outlook. AbbVie (ABBV US) reported a 22.7% YoY increase in Skyrizi sales to US$5.78bn, as newer immunology treatments offset the continuing contraction in Humira sales. Third-quarter revenue reached US$17.40bn and adjusted EPS was US$3.82. Management lifted annual adjusted EPS guidance to US$13.95–13.99 from US$13.76–13.96, narrowing uncertainty over this year’s earnings. (AbbVie / Reuters)
• Regeneron rallies on earnings and pipeline funding. Regeneron (REGN US) shares gained 13.33%. Third-quarter revenue rose 36% YoY to US$5.12bn and adjusted EPS rose 70% to US$20.07. An expanded Sanofi immunology alliance adds US$1bn of upfront collaboration revenue in the fourth quarter. Further milestone payments depend on future outcomes. (Regeneron / Market data)
• Take-private interest lifts Global Payments (GPN US). Global Payments (GPN US) shares gained 12.97% after Reuters reported that CD&R was exploring a buyout. The talks were preliminary, with no agreed price. Equity was worth about US$23bn, and analysts put net debt near US$22bn. Financing that debt could determine whether a bid proceeds. (Reuters / Market data)
• Canadian National Railway lifts adjusted earnings. Canadian National Railway (CNR.TO) posted the third-quarter revenue rose 15% YoY to C$4.77bn and adjusted EPS advanced 18% to C$2.16. The adjusted operating ratio improved 40bps to 61.0%, while the reported ratio worsened 230bps to 63.7%. The gap matters when assessing how much underlying efficiency reached reported profit. (CN)
• Coinbase falls as trading income contracts. Coinbase (COIN US) shares lost 10.62% after results and amid the Binance theft. Quarterly transaction revenue fell 43% YoY to US$590.2m, while crypto investment gains helped lift net income to US$718.7m from US$432.6m. Trading fees therefore give a different picture of operating momentum than headline profit. (Reuters / Reuters / Market data)
• Improved pricing supports FedEx Freight. FedEx Freight (FDXF US) shares gained 14.91% after its first four-month transition report. Revenue grew 9.2% YoY to US$3.3bn, while adjusted operating income rose 16.4% to US$510m. Daily shipments fell 1.4%. Higher fuel surcharges helped revenue, so pricing excluding fuel offers a clearer gauge of freight demand. (FedEx Freight / Reuters / Market data)
• Illumina drops despite higher guidance. Illumina (ILMN US) shares fell 18.64% after results. Quarterly revenue excluding tariff refunds was US$1.17bn. Organic revenue outside Greater China rose 4.7% YoY, but China revenue slipped 0.1%. Management raised full-year revenue guidance to US$4.64–4.66bn. The regional gap complicates the outlook for sequencing demand. (Illumina / Investing.com / Market data)
• Roblox flags weaker holiday bookings. Roblox (RBLX US) shares fell 18.05% after results. Quarterly revenue rose 16% YoY to US$1.6bn, but bookings fell 12% to US$1.7bn. Management expects fourth-quarter bookings to fall another 10–15% YoY. Bookings track current purchases, making the divergence from recognised revenue relevant to the next quarter’s cash generation. (Roblox / Market data)
• Twilio forecasts slower underlying growth. Twilio (TWLO US) shares fell 15.24% in the first cash session after results. Revenue rose 20% YoY to US$1.56bn in the third quarter and organic growth was 16%. Fourth-quarter organic growth guidance of 11–12% signals a slowdown despite management’s full-year reported growth forecast of 20%. (Twilio / Market data)
Greater China
• ICBC margin stabilises as profit recovers. ICBC (1398.HK) reported quarterly attributable profit of RMB111.96bn, up 9.97% YoY, after the Hong Kong close. Operating income rose 9.45% to RMB220.97bn. Nine-month net interest margin improved one basis point to 1.29%. Deposit repricing supported earnings, while weaker loan demand limits the benefit of steadier margins. (ICBC / Reuters) ICBC (1398.HK) is our Investment Opportunity.
• Agricultural Bank revenue outpaces profit growth. Agricultural Bank of China (1288.HK) reported third-quarter attributable profit of RMB90.17bn, up 10.84% YoY, and operating income of RMB208.38bn, up 15.14%. Its non-performing loan ratio fell four basis points from year-end to 1.23%. Improving asset quality supports earnings as the bank expands its balance sheet. (Agricultural Bank of China / Reuters) Agricultural Bank of China (1288.HK) is our Investment Opportunity.
• GigaDevice falls despite surging earnings. GigaDevice Semiconductor (3986.HK) lost 8.06% in the first Hong Kong session after results. Third-quarter revenue rose 225.7% YoY to RMB8.73bn and attributable profit rose 728.9% to RMB4.21bn. Operating cash flow rose 386.5% to RMB4.08bn. Strong cash generation accompanied the earnings surge, even as chip shares retreated. (GigaDevice / Market data) GigaDevice Semiconductor (3986.HK) is our Investment Opportunity.
• Battery electrics drive BYD sales gains. BYD (1211.HK) sold 490,168 new-energy vehicles in October, up 11.0% YoY. Battery-electric passenger-car sales rose 37.4% to 305,743, outweighing a decline in plug-in hybrids. Despite six consecutive months of year-on-year growth, cumulative new-energy vehicle sales through October remained 2.2% below the prior-year period. (BYD / CnEVPost)
• Exports offset Geely domestic volume decline. Geely Automobile (0175.HK) sold 310,183 vehicles in October, up 1.0% YoY. Exports rose 158% to 107,153, while domestic sales fell 23.6% to 203,030. Battery-electric sales rose 43%, against a 7% decline for plug-in hybrids. Overseas demand now carries more of the burden of sustaining growth. (Geely Automobile / CnEVPost) Geely Automobile (0175.HK) is our Core Recommendation.
Asia ex. China
• Kioxia initiates a dividend as profit growth flattens. Kioxia (285A.T) reported first-half sales of ¥4.25tn, up 436.8% YoY, as data-centre demand lifted flash prices. It announced its first interim dividend of ¥90 per pre-split share. December-quarter operating profit guidance of ¥2.00tn is essentially flat sequentially, suggesting slower incremental earnings growth. (Kioxia / Dividend notice)
• Tokyo Electron raises its earnings outlook. Tokyo Electron (8035.T) reported first-half operating profit of ¥506.78bn, up 67.2% YoY, on sales growth of 41.3% to ¥1.67tn. Its revised full-year forecast implies 87.1% operating profit growth to ¥1.17tn. The forecast depends on customers sustaining investment in manufacturing equipment for AI chips. (Tokyo Electron / Company presentation)
• Chip shipments account for nearly half of Korean exports. South Korea’s October exports rose 93.7% YoY to US$115.3bn, including US$56.4bn of semiconductors, up 259%. Imports increased 36.0%, leaving a US$42.5bn trade surplus. The figures highlight how strongly Korea’s trade balance now depends on overseas demand for chips used in AI infrastructure. (Trade ministry / Yonhap)
• Singapore retail strength cushions overseas weakness. Mapletree Pan Asia Commercial Trust (N2IU.SI) reported quarterly distribution per unit down 3.5% YoY to 1.94 Singapore cents. Net property income fell 6.3% to S$153.54m. VivoCity’s net property income rose 5.0% and finance costs fell 10.1%, partly offsetting weaker contributions from Japan, China and Hong Kong. (MPACT / The Business Times)
EMEA and Others
• AstraZeneca targets savings to fund its pipeline. AstraZeneca (AZN.L) rose 6.96% after outlining US$1.5bn in annualised pretax savings with up to US$2bn in restructuring costs. Quarterly revenue rose 7% YoY to US$16.21bn and core EPS rose 17% to US$2.79. Management expects to reinvest the savings principally in its drug pipeline. (AstraZeneca / Reuters / Market data)
• NatWest margin outlook disappoints investors. NatWest (NWG.L) fell 8.75%. Quarterly attributable profit fell 4.4% YoY to £1.5bn and return on tangible equity reached 21.60%. Management expects net interest margin to remain near 2.50% into 2027. Competition leaves less room for earnings growth from lending margins even as efficiency improves. (NatWest / Reuters / Sharecast / Market data)
• BP refining windfall accelerates debt reduction. BP (BP.L) reported quarterly underlying replacement cost profit of US$8.46bn, versus US$2.2bn a year earlier and US$7.33bn expected. Operating cash flow reached US$14.8bn, cutting net debt to US$13.9bn. Management plans to use part of surplus cash to settle remaining Deepwater Horizon liabilities. (BP / Reuters)
• Bayer wins Roundup trial after June’s ruling. Bayer (BAYN.DE) gained 5.46% in Europe after a St. Louis jury rejected three plaintiffs’ claims of design defect, fraud and negligence. The verdict tests legal theories still available after June’s Supreme Court ruling on warning labels. Other cases continue to shape potential settlement costs. (Bayer / Reuters / Reuters / Market data)
Traders' Corner
Our Technical View
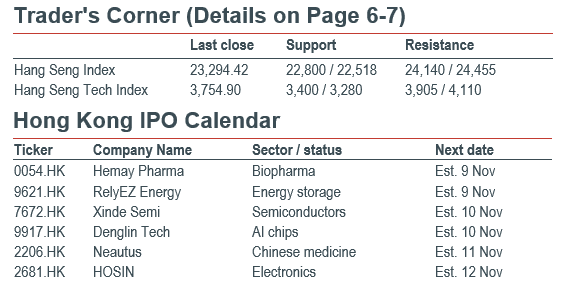
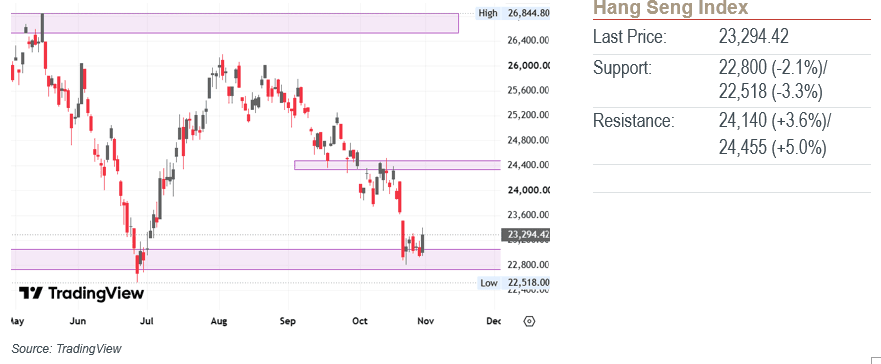
Weekly Chart: Price is currently testing its previous low support zone following a steep, impulsive downward wave. The localized deceleration at this key structural floor suggests an initial pause in sell-side dominance. The RSI is ticking upward from near the oversold threshold with positive velocity. As long as price remains defended above this support, we see a technical rebound toward upper overhead supply next week.
Daily Chart: Price is currently consolidating at its previous low support zone following a prior mark-down phase. The RSI is executing a positive inflection, turning upward directly out of the oversold zone with positive velocity. As long as price remains defended above this support, we see a technical rebound toward higher resistance.
Our Technical View
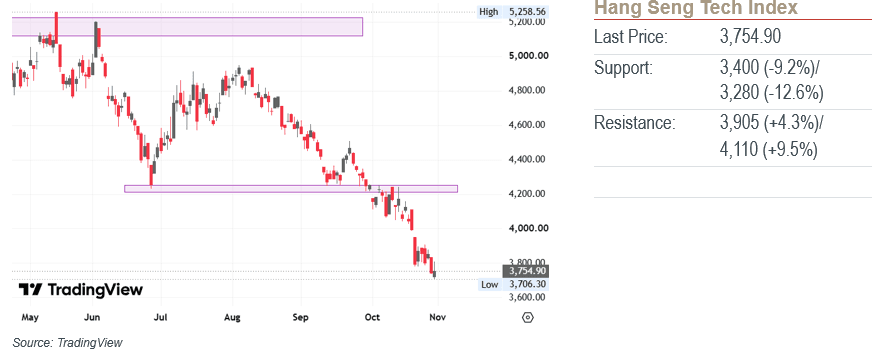
Weekly Chart: Price executed a firm downside continuation following a successful rejection at its support-turned-resistance zone. Having sustained its downward momentum, price action is currently traversing mid-way toward its lower support zone. The RSI is falling and has entered the oversold zone with negative velocity. As long as price remains suppressed beneath the converted resistance, we see continued downward expansion to complete the trajectory toward the lower support.
Daily Chart: Price is currently traversing mid-way toward its lower support zone within a dominant mark-down sequence. While the broader structural hierarchy remains firmly bearish, the localized compression and hover of the RSI around the oversold threshold signals a temporary momentum deceleration. This setup favors a short-term counter-trend corrective rebound before the primary trend reasserts itself. As long as any counter-trend relief bounce remains capped beneath key resistance, we see eventual resumption of downward expansion toward the lower support.
Market Movers: At the 30 October close, the S&P 500 fell 1.82% and the iShares Semiconductor ETF (SOXX US) lost 8.24%. Intel (INTC US) sank 28.58% in the first full session after it forecast 4Q revenue of US$15–16bn amid weak PC demand and a disruption at its Israeli factory. Reddit (RDDT US) fell 29.22% after warning that fewer search referrals could cut daily active users by a low-double-digit percentage if the trend persists. AstraZeneca (AZN.L) gained 6.96% as it projected US$1.5bn of annualised pre-tax savings to reinvest principally in its drug pipeline. (Reuters markets / Intel / Reuters on Intel / Reuters on Reddit / AstraZeneca / SOXX) iShares Semiconductor ETF (SOXX US) is our Investment Opportunity.
Macro: The BoJ held its policy rate at 1.25% by an 8–1 vote and will raise annual ETF sales from ¥330bn to ¥860bn at book value from January 2027. China’s manufacturing PMI fell from 50.1 to 49.30. New orders at 49.40 point to weaker factory demand. (BoJ / NBS)
Geopolitical: The FBI attributed the US$6.3bn Binance theft to North Korea. Binance resumed selected withdrawals on Sunday and said its replacement purchases covered about 95% of the loss. The pace of withdrawals will test customers’ confidence. (FBI / Reuters)
FICC: December gold and silver settled 3.29% and 5.93% lower, respectively. January Brent rose 2.37% to US$113.43/bbl and December WTI gained 2.08% to US$104.12/bbl on Friday. Seven OPEC+ members subsequently held December production targets steady, leaving actual shipments sensitive to passage through Hormuz. (AP / QNA / OPEC)
AI
• Amazon slips despite stronger AWS growth. Amazon (AMZN US) shares fell 1.41% in the first cash session after results. AWS sales rose 39% YoY to US$46.0bn, while trailing annual free cash flow turned negative at US$42.4bn. The US$240–247bn holiday sales forecast leaves limited room for retail weakness as infrastructure spending consumes cash. (Amazon / Reuters / Market data) Amazon (AMZN US) is our Core Recommendation.
• Intel triggers a semiconductor sell-off. Intel (INTC US) shares fell 28.58% after Intel forecast fourth-quarter revenue of US$15–16bn and adjusted EPS of US$0.25. Third-quarter sales rose 21% YoY to US$16.5bn. The guidance disappointment hit peers too, with the Philadelphia Semiconductor Index down 7.20%, highlighting the sector’s exposure to slowing PC demand. (Intel / Reuters / Reuters / Market data)
• Nvidia weighs backing a customer’s borrowing. Nvidia (NVDA US) is reportedly in talks over billions of dollars in credit guarantees for Nscale’s West Virginia data centre, according to Reuters, citing The Information. Anthropic previously agreed to rent US$45bn of computing capacity there. A guarantee would expose Nvidia to customer financing risk. Terms remain unsigned. (Reuters / TechCrunch) Nvidia (NVDA US) is our Core Recommendation.
• AI search threatens Reddit referral traffic. Reddit (RDDT US) shares fell 29.22% despite quarterly revenue rising 53% YoY to US$895m. Weekly search referrals fell by more than one million on average in October. If that pace persists, management said fourth-quarter daily active uniques could fall by a low-double-digit percentage from roughly 130m. (Reddit / Reuters / Market data)
Americas
• ExxonMobil converts refining strength into cash. ExxonMobil (XOM US) reported the third-quarter earnings rose 104% YoY to US$15.4bn and free cash flow was US$19.1bn. Nine-month earnings rose 53% YoY to US$34.1bn. Management expects US$20bn of repurchases next year. Refining earnings exceeded upstream earnings, increasing sensitivity to fuel margins as damaged capacity returns to service. (ExxonMobil / ExxonMobil 2025 / Reuters)
• Sandisk slides despite a flash-storage boom. Sandisk (SNDK US) shares fell 13.47% in the first cash session after results. Fiscal first-quarter revenue rose 378% YoY to US$11.03bn. Data-centre revenue reached US$4.80bn versus US$269m a year earlier. Peer pricing commentary put the durability of those gains in focus despite strong demand. (Sandisk / Reuters / Investing.com / Market data)
• Chevron uses stronger earnings to reduce debt. Chevron (CVX US) reported the third-quarter net income reached US$9.92bn from US$3.54bn a year earlier. U.S. refinery throughput hit a record 1.09m barrels per day and net debt fell US$7.8bn during the quarter. A stronger balance sheet gives Chevron room to absorb a reversal in refining margins. (Chevron / Reuters)
• AbbVie raises its profit outlook. AbbVie (ABBV US) reported a 22.7% YoY increase in Skyrizi sales to US$5.78bn, as newer immunology treatments offset the continuing contraction in Humira sales. Third-quarter revenue reached US$17.40bn and adjusted EPS was US$3.82. Management lifted annual adjusted EPS guidance to US$13.95–13.99 from US$13.76–13.96, narrowing uncertainty over this year’s earnings. (AbbVie / Reuters)
• Regeneron rallies on earnings and pipeline funding. Regeneron (REGN US) shares gained 13.33%. Third-quarter revenue rose 36% YoY to US$5.12bn and adjusted EPS rose 70% to US$20.07. An expanded Sanofi immunology alliance adds US$1bn of upfront collaboration revenue in the fourth quarter. Further milestone payments depend on future outcomes. (Regeneron / Market data)
• Take-private interest lifts Global Payments (GPN US). Global Payments (GPN US) shares gained 12.97% after Reuters reported that CD&R was exploring a buyout. The talks were preliminary, with no agreed price. Equity was worth about US$23bn, and analysts put net debt near US$22bn. Financing that debt could determine whether a bid proceeds. (Reuters / Market data)
• Canadian National Railway lifts adjusted earnings. Canadian National Railway (CNR.TO) posted the third-quarter revenue rose 15% YoY to C$4.77bn and adjusted EPS advanced 18% to C$2.16. The adjusted operating ratio improved 40bps to 61.0%, while the reported ratio worsened 230bps to 63.7%. The gap matters when assessing how much underlying efficiency reached reported profit. (CN)
• Coinbase falls as trading income contracts. Coinbase (COIN US) shares lost 10.62% after results and amid the Binance theft. Quarterly transaction revenue fell 43% YoY to US$590.2m, while crypto investment gains helped lift net income to US$718.7m from US$432.6m. Trading fees therefore give a different picture of operating momentum than headline profit. (Reuters / Reuters / Market data)
• Improved pricing supports FedEx Freight. FedEx Freight (FDXF US) shares gained 14.91% after its first four-month transition report. Revenue grew 9.2% YoY to US$3.3bn, while adjusted operating income rose 16.4% to US$510m. Daily shipments fell 1.4%. Higher fuel surcharges helped revenue, so pricing excluding fuel offers a clearer gauge of freight demand. (FedEx Freight / Reuters / Market data)
• Illumina drops despite higher guidance. Illumina (ILMN US) shares fell 18.64% after results. Quarterly revenue excluding tariff refunds was US$1.17bn. Organic revenue outside Greater China rose 4.7% YoY, but China revenue slipped 0.1%. Management raised full-year revenue guidance to US$4.64–4.66bn. The regional gap complicates the outlook for sequencing demand. (Illumina / Investing.com / Market data)
• Roblox flags weaker holiday bookings. Roblox (RBLX US) shares fell 18.05% after results. Quarterly revenue rose 16% YoY to US$1.6bn, but bookings fell 12% to US$1.7bn. Management expects fourth-quarter bookings to fall another 10–15% YoY. Bookings track current purchases, making the divergence from recognised revenue relevant to the next quarter’s cash generation. (Roblox / Market data)
• Twilio forecasts slower underlying growth. Twilio (TWLO US) shares fell 15.24% in the first cash session after results. Revenue rose 20% YoY to US$1.56bn in the third quarter and organic growth was 16%. Fourth-quarter organic growth guidance of 11–12% signals a slowdown despite management’s full-year reported growth forecast of 20%. (Twilio / Market data)
Greater China
• ICBC margin stabilises as profit recovers. ICBC (1398.HK) reported quarterly attributable profit of RMB111.96bn, up 9.97% YoY, after the Hong Kong close. Operating income rose 9.45% to RMB220.97bn. Nine-month net interest margin improved one basis point to 1.29%. Deposit repricing supported earnings, while weaker loan demand limits the benefit of steadier margins. (ICBC / Reuters) ICBC (1398.HK) is our Investment Opportunity.
• Agricultural Bank revenue outpaces profit growth. Agricultural Bank of China (1288.HK) reported third-quarter attributable profit of RMB90.17bn, up 10.84% YoY, and operating income of RMB208.38bn, up 15.14%. Its non-performing loan ratio fell four basis points from year-end to 1.23%. Improving asset quality supports earnings as the bank expands its balance sheet. (Agricultural Bank of China / Reuters) Agricultural Bank of China (1288.HK) is our Investment Opportunity.
• GigaDevice falls despite surging earnings. GigaDevice Semiconductor (3986.HK) lost 8.06% in the first Hong Kong session after results. Third-quarter revenue rose 225.7% YoY to RMB8.73bn and attributable profit rose 728.9% to RMB4.21bn. Operating cash flow rose 386.5% to RMB4.08bn. Strong cash generation accompanied the earnings surge, even as chip shares retreated. (GigaDevice / Market data) GigaDevice Semiconductor (3986.HK) is our Investment Opportunity.
• Battery electrics drive BYD sales gains. BYD (1211.HK) sold 490,168 new-energy vehicles in October, up 11.0% YoY. Battery-electric passenger-car sales rose 37.4% to 305,743, outweighing a decline in plug-in hybrids. Despite six consecutive months of year-on-year growth, cumulative new-energy vehicle sales through October remained 2.2% below the prior-year period. (BYD / CnEVPost)
• Exports offset Geely domestic volume decline. Geely Automobile (0175.HK) sold 310,183 vehicles in October, up 1.0% YoY. Exports rose 158% to 107,153, while domestic sales fell 23.6% to 203,030. Battery-electric sales rose 43%, against a 7% decline for plug-in hybrids. Overseas demand now carries more of the burden of sustaining growth. (Geely Automobile / CnEVPost) Geely Automobile (0175.HK) is our Core Recommendation.
Asia ex. China
• Kioxia initiates a dividend as profit growth flattens. Kioxia (285A.T) reported first-half sales of ¥4.25tn, up 436.8% YoY, as data-centre demand lifted flash prices. It announced its first interim dividend of ¥90 per pre-split share. December-quarter operating profit guidance of ¥2.00tn is essentially flat sequentially, suggesting slower incremental earnings growth. (Kioxia / Dividend notice)
• Tokyo Electron raises its earnings outlook. Tokyo Electron (8035.T) reported first-half operating profit of ¥506.78bn, up 67.2% YoY, on sales growth of 41.3% to ¥1.67tn. Its revised full-year forecast implies 87.1% operating profit growth to ¥1.17tn. The forecast depends on customers sustaining investment in manufacturing equipment for AI chips. (Tokyo Electron / Company presentation)
• Chip shipments account for nearly half of Korean exports. South Korea’s October exports rose 93.7% YoY to US$115.3bn, including US$56.4bn of semiconductors, up 259%. Imports increased 36.0%, leaving a US$42.5bn trade surplus. The figures highlight how strongly Korea’s trade balance now depends on overseas demand for chips used in AI infrastructure. (Trade ministry / Yonhap)
• Singapore retail strength cushions overseas weakness. Mapletree Pan Asia Commercial Trust (N2IU.SI) reported quarterly distribution per unit down 3.5% YoY to 1.94 Singapore cents. Net property income fell 6.3% to S$153.54m. VivoCity’s net property income rose 5.0% and finance costs fell 10.1%, partly offsetting weaker contributions from Japan, China and Hong Kong. (MPACT / The Business Times)
EMEA and Others
• AstraZeneca targets savings to fund its pipeline. AstraZeneca (AZN.L) rose 6.96% after outlining US$1.5bn in annualised pretax savings with up to US$2bn in restructuring costs. Quarterly revenue rose 7% YoY to US$16.21bn and core EPS rose 17% to US$2.79. Management expects to reinvest the savings principally in its drug pipeline. (AstraZeneca / Reuters / Market data)
• NatWest margin outlook disappoints investors. NatWest (NWG.L) fell 8.75%. Quarterly attributable profit fell 4.4% YoY to £1.5bn and return on tangible equity reached 21.60%. Management expects net interest margin to remain near 2.50% into 2027. Competition leaves less room for earnings growth from lending margins even as efficiency improves. (NatWest / Reuters / Sharecast / Market data)
• BP refining windfall accelerates debt reduction. BP (BP.L) reported quarterly underlying replacement cost profit of US$8.46bn, versus US$2.2bn a year earlier and US$7.33bn expected. Operating cash flow reached US$14.8bn, cutting net debt to US$13.9bn. Management plans to use part of surplus cash to settle remaining Deepwater Horizon liabilities. (BP / Reuters)
• Bayer wins Roundup trial after June’s ruling. Bayer (BAYN.DE) gained 5.46% in Europe after a St. Louis jury rejected three plaintiffs’ claims of design defect, fraud and negligence. The verdict tests legal theories still available after June’s Supreme Court ruling on warning labels. Other cases continue to shape potential settlement costs. (Bayer / Reuters / Reuters / Market data)
Traders' Corner
Our Technical View
Weekly Chart: Price is currently testing its previous low support zone following a steep, impulsive downward wave. The localized deceleration at this key structural floor suggests an initial pause in sell-side dominance. The RSI is ticking upward from near the oversold threshold with positive velocity. As long as price remains defended above this support, we see a technical rebound toward upper overhead supply next week.
Daily Chart: Price is currently consolidating at its previous low support zone following a prior mark-down phase. The RSI is executing a positive inflection, turning upward directly out of the oversold zone with positive velocity. As long as price remains defended above this support, we see a technical rebound toward higher resistance.
Our Technical View
Weekly Chart: Price executed a firm downside continuation following a successful rejection at its support-turned-resistance zone. Having sustained its downward momentum, price action is currently traversing mid-way toward its lower support zone. The RSI is falling and has entered the oversold zone with negative velocity. As long as price remains suppressed beneath the converted resistance, we see continued downward expansion to complete the trajectory toward the lower support.
Daily Chart: Price is currently traversing mid-way toward its lower support zone within a dominant mark-down sequence. While the broader structural hierarchy remains firmly bearish, the localized compression and hover of the RSI around the oversold threshold signals a temporary momentum deceleration. This setup favors a short-term counter-trend corrective rebound before the primary trend reasserts itself. As long as any counter-trend relief bounce remains capped beneath key resistance, we see eventual resumption of downward expansion toward the lower support.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


