

Periodic/Sector reports
Property: August Home Sales Dragged By Lack Of New Launches
Highlights
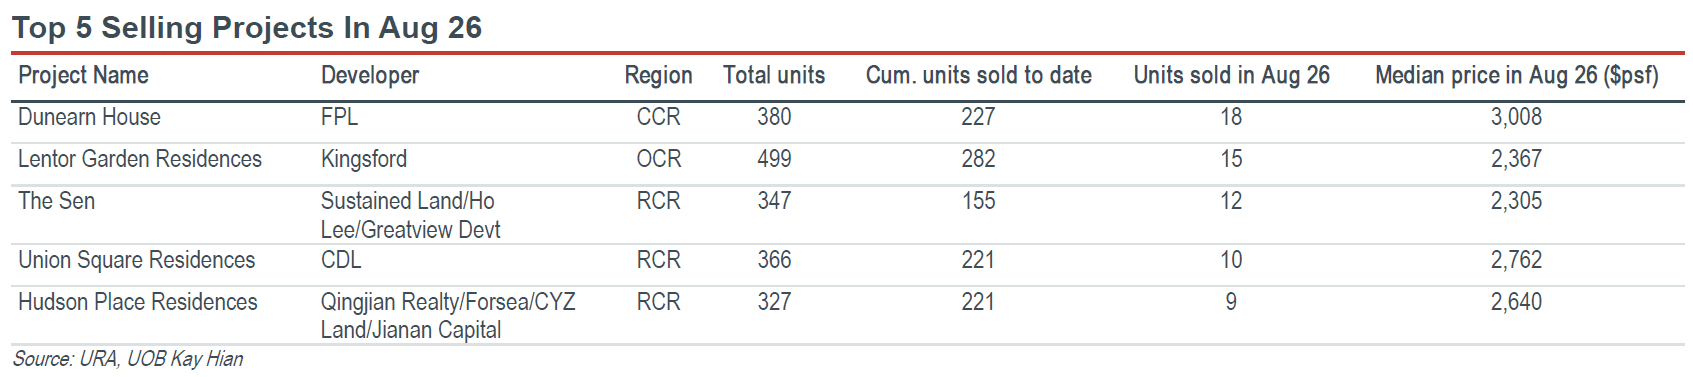
- Dearth of new launches resulted in muted August new home sales. A lack of new launches during the Hungry Ghost month led to monthly new-home sales declining to a ytd low of 171 units in Aug 26. Excluding executive condominiums (EC), primary home sales fell around 93% yoy and 79% mom, to 153 units. In Aug 26, only additional new units from Union Square Residences were launched, according to URA data. The top five selling developments during the month were Dunearn House, Lentor Garden Residences, The Sen, Union Square Residences and The Hudson Place Residences.
- RCR accounted for bulk of monthly home sales. Take-up in the Rest of Central Region (RCR) made up 47% of total ex-EC sales while Outside Central Region (OCR) transactions accounted for another 37%. Core Central Region sales took up the remaining 16%.
- URA residential price index up 1.4% in 1H26. Meanwhile, private home prices grew 1.4% in 1H26 while HDB resale prices retraced 0.4% over the same period. Based on SRX data for the secondary market prices and transactions, we note that private condo resale prices inched up 2.3% for 7M26 even as resale volumes fell 4.1% yoy to 6,863 units. Maintain OVERWEIGHT.
Analysis
- Maintain our forecast of 8,000-9,000 home sales and 2-3% price appreciation for 2026. Excluding ECs, primary home sales in 8M26 of 5,047 units are broadly in line with our projection of 8,000-9,000 units for 2026 while price growth of 1.4% in 1H26 also fell within our forecast range of 2-3% for the year.
- Slower new launch pipeline in 2H26. An estimated 4,222 units are expected to be marketed in 2H26, slightly lower than the 4,874 units launched in 1H26. Notable projects to be rolled out include Amberwood at Holland, the first residential project in the Holland Plain precinct, CDL’s Lucerne Grand and UOL/Capitaland Development’s Thomson Reserve. With interest rates ticking up from their Apr 26 low amid rising land cost, we think buying sentiment is likely to be shaped by developers’ pricing strategy and absolute quantum affordability, in addition to location considerations.
Highlights
- Dearth of new launches resulted in muted August new home sales. A lack of new launches during the Hungry Ghost month led to monthly new-home sales declining to a ytd low of 171 units in Aug 26. Excluding executive condominiums (EC), primary home sales fell around 93% yoy and 79% mom, to 153 units. In Aug 26, only additional new units from Union Square Residences were launched, according to URA data. The top five selling developments during the month were Dunearn House, Lentor Garden Residences, The Sen, Union Square Residences and The Hudson Place Residences.
- RCR accounted for bulk of monthly home sales. Take-up in the Rest of Central Region (RCR) made up 47% of total ex-EC sales while Outside Central Region (OCR) transactions accounted for another 37%. Core Central Region sales took up the remaining 16%.
- URA residential price index up 1.4% in 1H26. Meanwhile, private home prices grew 1.4% in 1H26 while HDB resale prices retraced 0.4% over the same period. Based on SRX data for the secondary market prices and transactions, we note that private condo resale prices inched up 2.3% for 7M26 even as resale volumes fell 4.1% yoy to 6,863 units. Maintain OVERWEIGHT.
Analysis
- Maintain our forecast of 8,000-9,000 home sales and 2-3% price appreciation for 2026. Excluding ECs, primary home sales in 8M26 of 5,047 units are broadly in line with our projection of 8,000-9,000 units for 2026 while price growth of 1.4% in 1H26 also fell within our forecast range of 2-3% for the year.
- Slower new launch pipeline in 2H26. An estimated 4,222 units are expected to be marketed in 2H26, slightly lower than the 4,874 units launched in 1H26. Notable projects to be rolled out include Amberwood at Holland, the first residential project in the Holland Plain precinct, CDL’s Lucerne Grand and UOL/Capitaland Development’s Thomson Reserve. With interest rates ticking up from their Apr 26 low amid rising land cost, we think buying sentiment is likely to be shaped by developers’ pricing strategy and absolute quantum affordability, in addition to location considerations.
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


