

Periodic/Sector reports
Renewable Energy - Solar: The Fastest Growing Energy Mix In Peninsular Malaysia; Players Set To Benefit From RM14b CRESS Wins
OVERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- Solar will be the fastest growing energy mix by 2035, supporting the government’s net-zero greenhouse emission by 2050. As the government is supportive, we expect a further drop in SAC for CRESS programme (to 15 sen/kwh).
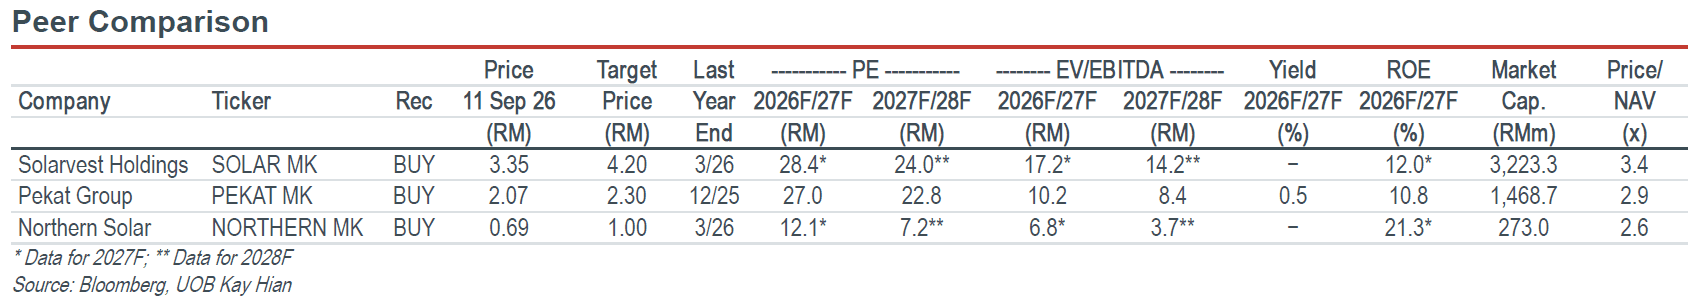
- This will pave the way for positive CRESS contract win(s) for solar EPCC players. Our sensitivity suggests a 50MW CRESS win can lift market cap by 5%/10%/55% for Solarvest/Pekat/Northern Solar respectively.
- Maintain OVERWEIGHT. We lift Solarvest’s target price to RM4.20 to reflect the inflection point as the group enters its next phase of growth with Brookfield. We also continue to like Pekat for its strong set of management, and raise our target price to RM2.30.
Analysis
- Government committed to NeTR. We recently attended the Energy Regulatory Insights 2026, organised by the regulator Energy Commission. Key takeaways are: a) the government remains committed to ensuring sustainable and affordable power supply in Malaysia; and b) Malaysia is on track to achieving 70% clean energy capacity by 2050. A NeTR report card will be published in 2027, which will accurately reflect current progress and market trends, and battery storage will be a key enabler for the renewable energy (RE) sector, we opine.
- Solar: Fastest growing energy mix by 2035. Solar capacity is projected to grow at a 22% CAGR over the next decade (2026-35), making it the fastest growing energy mix in Peninsular Malaysia. In fact, the grid system operator (GSO) expects peak demand to surge by 50% in 2035, driven largely by data centre (DC) plant ups. To keep pace, GSO expects solar capacity to grow by 5x over the next decade. We remain positive on the RE sector as it is a key enabler in achieving net zero carbon emission by 2050.
- Supportive RE policy: SAC may drop to 15 sen/kwh. Importantly, the regulator remains supportive of the RE sector. Our channel checks suggest that the system access charge (SAC) for the Corporate Renewable Energy Supply Scheme (CRESS) may drop from 20sen/kwh to 15 sen/kwh for firm output with battery storage. This is a key re-rating catalyst for solar EPCC players, as the market awaits new CRESS project wins for DC players. Our sensitivity analysis suggests every 50MW CRESS win will raise the market caps of Solarvest/Pekat/Northern Solar by 5%/10%/55% respectively (please see overleaf).
- The economics of CRESS: Project IRR of 9%. At present, to maintain competitiveness, solar EPCC players must benchmark their CRESS tariff against Tenaga Nasional's ultra-high-voltage (UHV) charge of 55 sen/kwh for DCs. A 15-year CRESS – based on current SAC charge of 20 sen/kwh – will yield a project IRR of 7%. We believe this is not attractive enough for the likes of Solarvest and Pekat given higher funding costs of 5-6%. It does however, make sense for large players like TNB who have stronger funding leverage. A 5 sen/kwh reduction in SAC will lift CRESS project IRRs to 9%, making it more attractive for solar EPCC players to enter into a long-term CRESS agreement.
Highlights
- Solar will be the fastest growing energy mix by 2035, supporting the government’s net-zero greenhouse emission by 2050. As the government is supportive, we expect a further drop in SAC for CRESS programme (to 15 sen/kwh).
- This will pave the way for positive CRESS contract win(s) for solar EPCC players. Our sensitivity suggests a 50MW CRESS win can lift market cap by 5%/10%/55% for Solarvest/Pekat/Northern Solar respectively.
- Maintain OVERWEIGHT. We lift Solarvest’s target price to RM4.20 to reflect the inflection point as the group enters its next phase of growth with Brookfield. We also continue to like Pekat for its strong set of management, and raise our target price to RM2.30.
Analysis
- Government committed to NeTR. We recently attended the Energy Regulatory Insights 2026, organised by the regulator Energy Commission. Key takeaways are: a) the government remains committed to ensuring sustainable and affordable power supply in Malaysia; and b) Malaysia is on track to achieving 70% clean energy capacity by 2050. A NeTR report card will be published in 2027, which will accurately reflect current progress and market trends, and battery storage will be a key enabler for the renewable energy (RE) sector, we opine.
- Solar: Fastest growing energy mix by 2035. Solar capacity is projected to grow at a 22% CAGR over the next decade (2026-35), making it the fastest growing energy mix in Peninsular Malaysia. In fact, the grid system operator (GSO) expects peak demand to surge by 50% in 2035, driven largely by data centre (DC) plant ups. To keep pace, GSO expects solar capacity to grow by 5x over the next decade. We remain positive on the RE sector as it is a key enabler in achieving net zero carbon emission by 2050.
- Supportive RE policy: SAC may drop to 15 sen/kwh. Importantly, the regulator remains supportive of the RE sector. Our channel checks suggest that the system access charge (SAC) for the Corporate Renewable Energy Supply Scheme (CRESS) may drop from 20sen/kwh to 15 sen/kwh for firm output with battery storage. This is a key re-rating catalyst for solar EPCC players, as the market awaits new CRESS project wins for DC players. Our sensitivity analysis suggests every 50MW CRESS win will raise the market caps of Solarvest/Pekat/Northern Solar by 5%/10%/55% respectively (please see overleaf).
- The economics of CRESS: Project IRR of 9%. At present, to maintain competitiveness, solar EPCC players must benchmark their CRESS tariff against Tenaga Nasional's ultra-high-voltage (UHV) charge of 55 sen/kwh for DCs. A 15-year CRESS – based on current SAC charge of 20 sen/kwh – will yield a project IRR of 7%. We believe this is not attractive enough for the likes of Solarvest and Pekat given higher funding costs of 5-6%. It does however, make sense for large players like TNB who have stronger funding leverage. A 5 sen/kwh reduction in SAC will lift CRESS project IRRs to 9%, making it more attractive for solar EPCC players to enter into a long-term CRESS agreement.
OVERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Our latest research

14 Sept 2026
IT Hardware - Handset: Apple-linked And Premium Suppliers To Widen Their Lead Amid The Downcycle

11 Sept 2026
