
Periodic/Sector reports
China Property: Second-hand Sales Outperform New-Home Sales In Sep 26; Tier 1 Cities Property Transactions Rebound In Oct 26
UNDERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- New-home sales growth slowed in Sep 26, while second-hand sales remained more resilient. The 14-city average rental yield rose further by 0.12ppt yoy to 2.59% as prices fell faster than rents. Land market sentiment continues to be concentrated in Tier 1 cities, with land sales in 300 cities/Tier 1 cities dropping 21% yoy and rising 14% yoy respectively in 9M26.
- Property transactions in Oct 26 thus far are encouraging, with Tier 1 new-home and second-hand sales rising 44%/54% yoy respectively. This could possibly be due to the mortgage rate subsidy. The overall price trends remain on a downward trajectory.
- Maintain UNDERWEIGHT on the sector. Top picks are COLI and CR Mixc.
Analysis
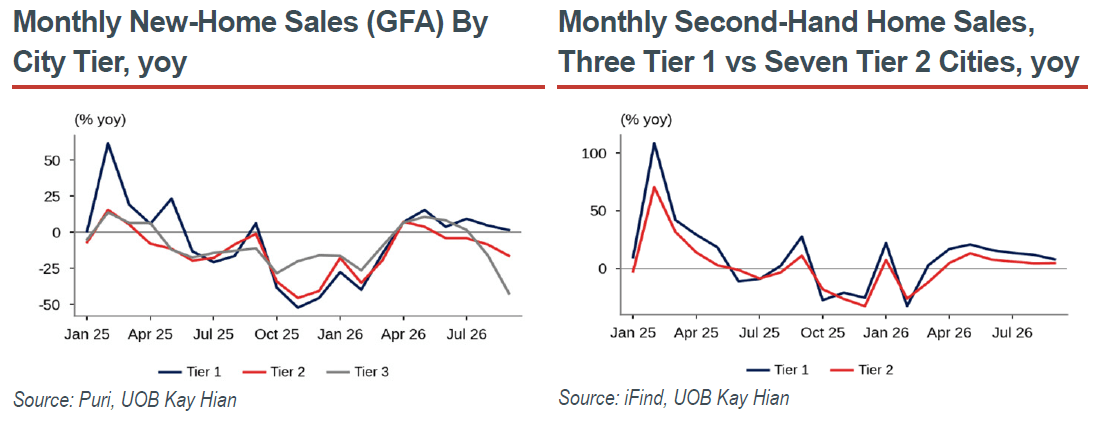
- In Tier 1 cities, new-home sales growth moderated in Sep 26 despite Beijing’s post-easing rebound. According to Puri, residential GFA sold in Tier 1 cities rose 1.5% yoy in Sep 26, down from +4.7% in Aug 26, while residential GFA sold in Tier 2/3 cities fell 16.4%/42.3% yoy respectively. We attribute part of the slowdown to the high base, as Tier 1 sales rose 6.2% yoy in Sep 25 after falling 16.5% in Aug 25. In Sep 26, residential GFA sold in Beijing /Shanghai/ Guangzhou/Shenzhen sales changed by +29.6%/-11.3%/-8.3%/+1.2% yoy respectively, with Beijing’s up 46.5% mom in its first full month after the 7 August easing. In 9M26, GFA sold fell 3.4%/10.1%/8.4% yoy in Tier 1/2/3 cities respectively.
- Second-hand sales growth is relatively stronger than new-home sales. According to iFind, second-hand sales in three Tier 1 cities and seven Tier 2 cities rose 7.9%/4.7% yoy respectively in Sep 26, against +11.9%/+4.5% yoy in Aug 26. We attribute the slowdown in Tier 1 cities mainly to the high base, as Sep 25 sales rose 27.6% yoy. Second-hand sales in Shanghai (+15.7% yoy) grew for the seventh consecutive month, while that in Beijing (+0.8%) and Shenzhen (-2.5%) lagged. In 9M26, second-hand sales rose 9.3%/1.3% yoy in Tier 1/2 cities respectively.
Highlights
- New-home sales growth slowed in Sep 26, while second-hand sales remained more resilient. The 14-city average rental yield rose further by 0.12ppt yoy to 2.59% as prices fell faster than rents. Land market sentiment continues to be concentrated in Tier 1 cities, with land sales in 300 cities/Tier 1 cities dropping 21% yoy and rising 14% yoy respectively in 9M26.
- Property transactions in Oct 26 thus far are encouraging, with Tier 1 new-home and second-hand sales rising 44%/54% yoy respectively. This could possibly be due to the mortgage rate subsidy. The overall price trends remain on a downward trajectory.
- Maintain UNDERWEIGHT on the sector. Top picks are COLI and CR Mixc.
Analysis
- In Tier 1 cities, new-home sales growth moderated in Sep 26 despite Beijing’s post-easing rebound. According to Puri, residential GFA sold in Tier 1 cities rose 1.5% yoy in Sep 26, down from +4.7% in Aug 26, while residential GFA sold in Tier 2/3 cities fell 16.4%/42.3% yoy respectively. We attribute part of the slowdown to the high base, as Tier 1 sales rose 6.2% yoy in Sep 25 after falling 16.5% in Aug 25. In Sep 26, residential GFA sold in Beijing /Shanghai/ Guangzhou/Shenzhen sales changed by +29.6%/-11.3%/-8.3%/+1.2% yoy respectively, with Beijing’s up 46.5% mom in its first full month after the 7 August easing. In 9M26, GFA sold fell 3.4%/10.1%/8.4% yoy in Tier 1/2/3 cities respectively.
- Second-hand sales growth is relatively stronger than new-home sales. According to iFind, second-hand sales in three Tier 1 cities and seven Tier 2 cities rose 7.9%/4.7% yoy respectively in Sep 26, against +11.9%/+4.5% yoy in Aug 26. We attribute the slowdown in Tier 1 cities mainly to the high base, as Sep 25 sales rose 27.6% yoy. Second-hand sales in Shanghai (+15.7% yoy) grew for the seventh consecutive month, while that in Beijing (+0.8%) and Shenzhen (-2.5%) lagged. In 9M26, second-hand sales rose 9.3%/1.3% yoy in Tier 1/2 cities respectively.
UNDERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Sept 2026
China Property: First Central Mortgage Interest Subsidy From 1 Oct 26; Tier 1 Land Supply Up 12% mom In Sep 26

23 Sept 2026
China Property: NBS Publishes Inaugural Second-Hand Transactions Data; Household Mortgage Borrowing Is Still Shrinking

8 Sept 2026
China Property: Shanghai Shifts Housing Supply From New Build To Renewal; National Land Supply Keeps Shrinking
Our latest research

9 Oct 2026
Automobile: China Auto Sector Weekly (26 Sep-8 Oct 26)

9 Oct 2026
Consumer - China Consumer: 2026 National Day Holiday Consumption Trend

6 Oct 2026