
Periodic/Sector reports
Automobile: China Auto Sector Weekly (26 Sep-8 Oct 26)
Highlights
- We cut our 2026-28 sales estimates for auto OEMs, based on lower-than-expected 9M26 sales.
- 2027 sales are poised for a modest recovery on stabilisation of domestic sales and sustained buoyant export growth.
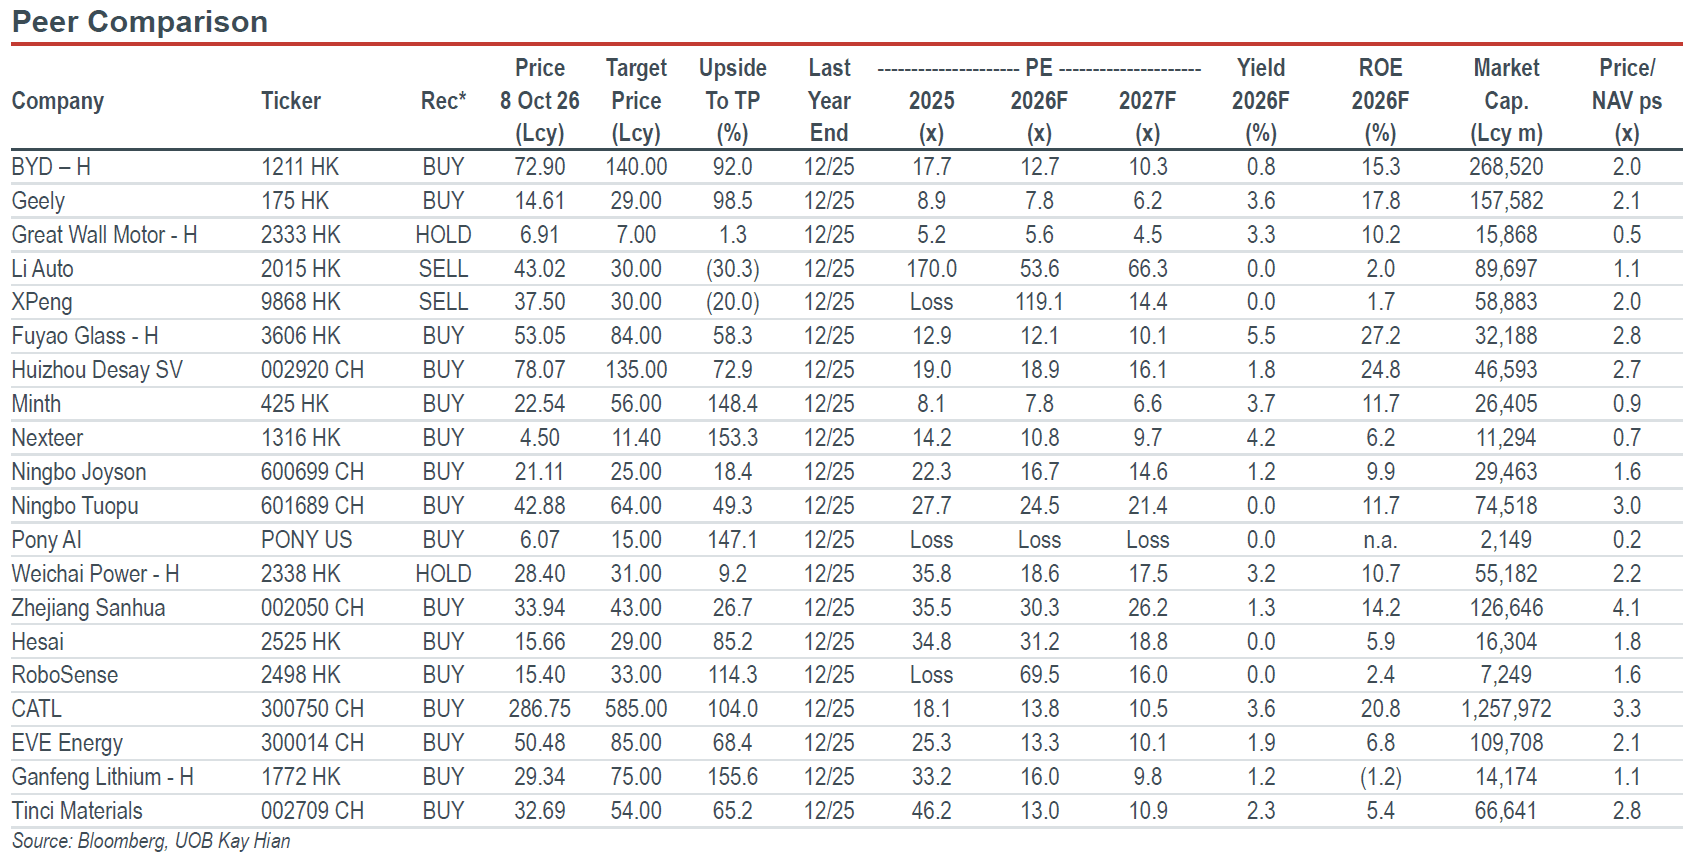
- Trade barriers to China’s EVs are rising globally through tariffs and localisation rules that force Chinese OEMs from exports to local production. This favours the leading OEMs – BYD and Geely.
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely, CATL. Top SELLs: Li Auto, XPeng.
Analysis
- Auto OEMs’ 9M26 sales came in below estimates, due to weaker-than-expected domestic market and ICE-car sales amid the expiry of the purchase tax exception and spike in oil prices.
- BYD (1211 HK/BUY/Target: HK$140.00) has resumed positive yoy sales growth since May. Monthly sales recovered from a recent trough of 190,190 units (-41% yoy/-9% mom) in Feb 26 to 463,561 units (+17% yoy/+5% mom) in Sep 26, the seventh month of positive growth in a row. This brings 9M26 sales to 3.13m units (-3.9% yoy). Attaining BYD’s 2026 sales target of 5m units requires average monthly sales of 622,800 units (+39% yoy) in 4Q26, well above September sales of 463,561 units.
- Geely (175 HK/BUY/Target: HK$29.00) has kept positive yoy sales growth ytd. Monthly sales remained at 200,000-300,000 units ytd, with export growth offset by a drop in domestic sales. September sales grew 7% yoy and 8% mom to a ytd record of 292,168 units, bringing 9M26 sales to 2.235m units (+3% yoy). It requires average monthly sales of 404,840 units (+42% yoy) in 4Q26 to reach Geely’s 2026 target of 3.45m units.
Highlights
- We cut our 2026-28 sales estimates for auto OEMs, based on lower-than-expected 9M26 sales.
- 2027 sales are poised for a modest recovery on stabilisation of domestic sales and sustained buoyant export growth.
- Trade barriers to China’s EVs are rising globally through tariffs and localisation rules that force Chinese OEMs from exports to local production. This favours the leading OEMs – BYD and Geely.
- Maintain MARKET WEIGHT. Top BUYs: BYD, Geely, CATL. Top SELLs: Li Auto, XPeng.
Analysis
- Auto OEMs’ 9M26 sales came in below estimates, due to weaker-than-expected domestic market and ICE-car sales amid the expiry of the purchase tax exception and spike in oil prices.
- BYD (1211 HK/BUY/Target: HK$140.00) has resumed positive yoy sales growth since May. Monthly sales recovered from a recent trough of 190,190 units (-41% yoy/-9% mom) in Feb 26 to 463,561 units (+17% yoy/+5% mom) in Sep 26, the seventh month of positive growth in a row. This brings 9M26 sales to 3.13m units (-3.9% yoy). Attaining BYD’s 2026 sales target of 5m units requires average monthly sales of 622,800 units (+39% yoy) in 4Q26, well above September sales of 463,561 units.
- Geely (175 HK/BUY/Target: HK$29.00) has kept positive yoy sales growth ytd. Monthly sales remained at 200,000-300,000 units ytd, with export growth offset by a drop in domestic sales. September sales grew 7% yoy and 8% mom to a ytd record of 292,168 units, bringing 9M26 sales to 2.235m units (+3% yoy). It requires average monthly sales of 404,840 units (+42% yoy) in 4Q26 to reach Geely’s 2026 target of 3.45m units.
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

25 Sept 2026
Automobile: China Auto Sector Weekly (19-25 Sep 26)

11 Sept 2026
Automobile: Weekly: 60-Day Payment Policy Reinforced; September’s New Model Launch Calendar Busier Than That Of Chengdu Auto Show

18 Sept 2026
Automobile: Weekly: Lithium Carbonate Price Drop Reconfirms Our Preference For OEMs; Bottom-fishing Opportunity Emerges For CATL
Our latest research

9 Oct 2026
Consumer - China Consumer: 2026 National Day Holiday Consumption Trend

6 Oct 2026
Hong Kong Property: Major Developers’ Balance Sheets And Profitability Repaired; SHKP Family Buying; Residential Prices Consolidating

2 Oct 2026