

Country Daily
China Economics Money Supply / ChangXin Memory Technologies
Analyst
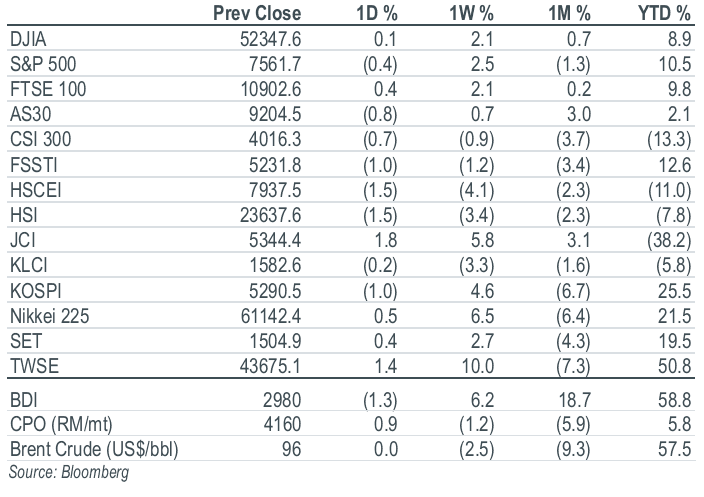
Key Indices
Top Stories
Economics | Money Supply
Oct 26’s M1 growth rebounded to 4.4% yoy (+1.2ppt mom), above consensus, while M2 eased to 7.1% yoy (-0.1ppt mom). New bank loans contracted by Rmb0.10t (-Rmb1.18t mom) and new TSF fell to Rmb1.14t (-Rmb2.41t mom), both missing forecasts. Outstanding bank loans growth slipped to 4.7% yoy (-0.1ppt mom), while outstanding TSF growth edged up to 7.2% yoy (+0.1ppt mom). Recent funding policies should support corporate lending, but household demand remains weak. Overall, the data is market neutral.
Initiate Coverage | ChangXin Memory Technologies (688825 CH/BUY/Rmb39.98/Target: Rmb59.40)
CXMT is China's largest DRAM maker and the fourth largest globally. We expect it to gain market share from 8.5% in 2025 to 10.7% in 2028 on capacity expansion and improving yields. A DRAM shortage through 2028, driven by AI servers and GPUs, should sustain elevated prices and a richer mix toward DDR5 and HBM. HBM should ramp up from 2027, lifting its revenue contribution to 11.7% by 2028 despite yield challenges. Initiate coverage with BUY; target price Rmb59.40.
Top Stories
Economics | Money Supply
Oct 26’s M1 growth rebounded to 4.4% yoy (+1.2ppt mom), above consensus, while M2 eased to 7.1% yoy (-0.1ppt mom). New bank loans contracted by Rmb0.10t (-Rmb1.18t mom) and new TSF fell to Rmb1.14t (-Rmb2.41t mom), both missing forecasts. Outstanding bank loans growth slipped to 4.7% yoy (-0.1ppt mom), while outstanding TSF growth edged up to 7.2% yoy (+0.1ppt mom). Recent funding policies should support corporate lending, but household demand remains weak. Overall, the data is market neutral.
Initiate Coverage | ChangXin Memory Technologies (688825 CH/BUY/Rmb39.98/Target: Rmb59.40)
CXMT is China's largest DRAM maker and the fourth largest globally. We expect it to gain market share from 8.5% in 2025 to 10.7% in 2028 on capacity expansion and improving yields. A DRAM shortage through 2028, driven by AI servers and GPUs, should sustain elevated prices and a richer mix toward DDR5 and HBM. HBM should ramp up from 2027, lifting its revenue contribution to 11.7% by 2028 despite yield challenges. Initiate coverage with BUY; target price Rmb59.40.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


