
Country Daily
China Automobile Weekly / LINK REIT / Edge Medical / Foxconn Industrial Internet
Analyst
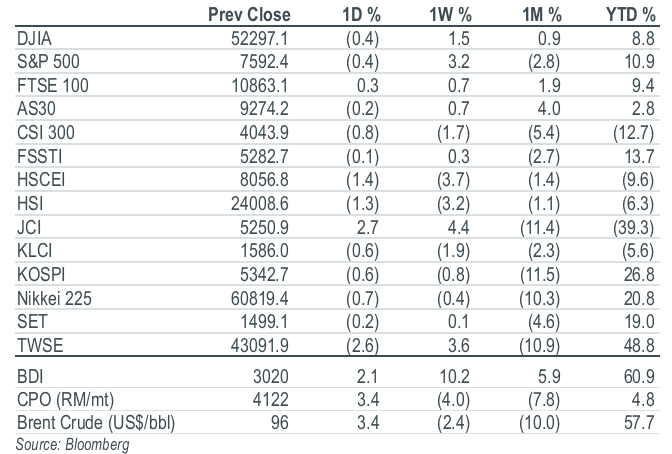
Key Indices
Top Stories
Sector Update | Automobile
October NEV sales hit a record 1.94m on exports; domestic NEV sales fell 9% yoy. China extended battery-export-control suspension to 10 Jan 27. Momenta formed a 51:49 intelligent-driving JV with SAIC to aid overseas expansion. Hesai reported mixed 3Q26 results and expects robotics to contribute 50-60% of 2027 revenue. We estimate XPeng’s 3Q26 net loss at Rmb1b. Maintain MARKET WEIGHT; BUYs: BYD, Geely; SELLs: Li Auto, XPeng.
Company Results | LINK REIT (823 HK/BUY/HK$41.50/Target: HK$45.70)
1HFY27 DPU rose 0.3% yoy to 127.25 HK cents, accounting for 51% of our FY27 forecast, as cost control offset a retail rental reversion of -7.5% in Hong Kong. Management reiterated its FY27 reversion guidance and is planning HK$1b-2b of unit buybacks in 2HFY27. Four non-core disposals in 2026 will recycle about HK$6.3b. The Eastpoint Mall stake marks a return to acquisitions and is expected to sharpen Link REIT’s focus. We increase FY27-29 earnings by 0.5%. Maintain BUY. Raise target price to HK$45.70.
Company Update | Edge Medical (2675 HK/BUY/HK$27.88/Target: HK$37.00)
Our industry check has shown that fierce price competition in the surgical robot segment may lead to slower-than-expected revenue growth and depress profit margins for Edge Medical in 2026. Edge Medical expects to launch new products in 2027 competing directly with Intuitive Surgical’s most advanced model – da Vinci 5. The move will also allow the company to price the new products favourably and promote a strategic shift towards high-end market share. Maintain BUY. Lower target price to HK$37.00 to reflect short-term price pressure.
Company Update | Foxconn Industrial Internet (601138 CH/BUY/Rmb43.35/Target: Rmb77.60)
FII’s parent company Hon Hai Precision remains well positioned for double-digit revenue growth in 2027, supported by sustained AI-rack demand and rising ASIC adoption. Vertically-integrated content and consignment should strengthen gross margin and capital efficiency, while additional NeoCloud customers provide further share-gain potential. Data centre site readiness and component shortages remain the main constraints. Maintain BUY with a target price of Rmb77.60.
Top Stories
Sector Update | Automobile
October NEV sales hit a record 1.94m on exports; domestic NEV sales fell 9% yoy. China extended battery-export-control suspension to 10 Jan 27. Momenta formed a 51:49 intelligent-driving JV with SAIC to aid overseas expansion. Hesai reported mixed 3Q26 results and expects robotics to contribute 50-60% of 2027 revenue. We estimate XPeng’s 3Q26 net loss at Rmb1b. Maintain MARKET WEIGHT; BUYs: BYD, Geely; SELLs: Li Auto, XPeng.
Company Results | LINK REIT (823 HK/BUY/HK$41.50/Target: HK$45.70)
1HFY27 DPU rose 0.3% yoy to 127.25 HK cents, accounting for 51% of our FY27 forecast, as cost control offset a retail rental reversion of -7.5% in Hong Kong. Management reiterated its FY27 reversion guidance and is planning HK$1b-2b of unit buybacks in 2HFY27. Four non-core disposals in 2026 will recycle about HK$6.3b. The Eastpoint Mall stake marks a return to acquisitions and is expected to sharpen Link REIT’s focus. We increase FY27-29 earnings by 0.5%. Maintain BUY. Raise target price to HK$45.70.
Company Update | Edge Medical (2675 HK/BUY/HK$27.88/Target: HK$37.00)
Our industry check has shown that fierce price competition in the surgical robot segment may lead to slower-than-expected revenue growth and depress profit margins for Edge Medical in 2026. Edge Medical expects to launch new products in 2027 competing directly with Intuitive Surgical’s most advanced model – da Vinci 5. The move will also allow the company to price the new products favourably and promote a strategic shift towards high-end market share. Maintain BUY. Lower target price to HK$37.00 to reflect short-term price pressure.
Company Update | Foxconn Industrial Internet (601138 CH/BUY/Rmb43.35/Target: Rmb77.60)
FII’s parent company Hon Hai Precision remains well positioned for double-digit revenue growth in 2027, supported by sustained AI-rack demand and rising ASIC adoption. Vertically-integrated content and consignment should strengthen gross margin and capital efficiency, while additional NeoCloud customers provide further share-gain potential. Data centre site readiness and component shortages remain the main constraints. Maintain BUY with a target price of Rmb77.60.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


