
Country Daily
China Internet AI Sector / FIT Hon Teng / Galaxy Entertainment Group / WuXi AppTec
Analyst
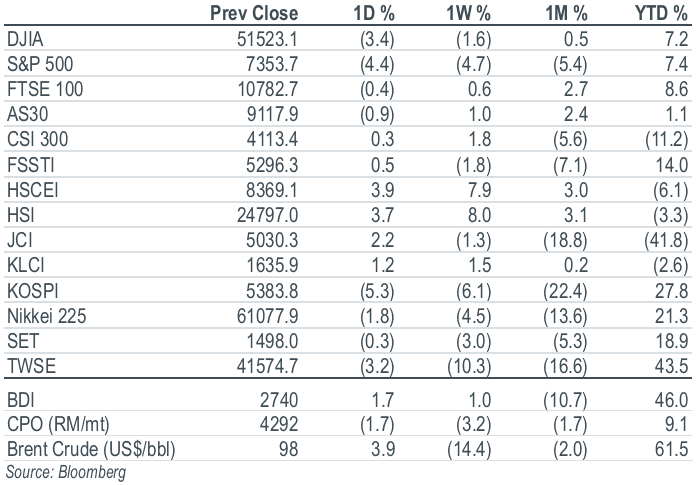
Key Indices
Top Stories
Sector Update | China Internet
We see that the AI industry is transitioning from a capacity-driven investment cycle towards an intelligence monetisation cycle, where model differentiation, inference efficiency, enterprise adoption and sustainable gross profit generation will increasingly determine value capture. We remain constructive on China's AI value chain, with a preference for Alibaba and Z.ai, while viewing Tencent as a longer-term beneficiary of AI application monetisation. Maintain MARKET WEIGHT.
Company Results | FIT Hon Teng (6088 HK/BUY/HK$2.91/Target: HK$4.20)
FIT’s 3Q26 revenue grew 4.0% yoy but operating profit declined 38.8% yoy, impacted by higher material costs and slower-than-expected facility ramp-up. 9M26 revenue and net profit represented 69% and 32% of our full-year estimates respectively. Management cut 2026 operating profit guidance from 70% yoy growth to flattish growth and targets 2027 operating profit to grow faster than its revenue. Maintain BUY but lower target price from HK$9.19 to HK$4.20, based on 15.0x 2027F PE.
Company Results | Galaxy Entertainment Group (27 HK/BUY/HK$34.84/Target: HK$43.00)
Galaxy’s 3Q26 GGR market share increased 1.7ppt qoq to 22.0%, but normalised EBITDA declined 9% qoq on a deterioration in margin. Galaxy’s market share during the Golden Week was largely flat yoy, affected by unfavourable luck. Looking ahead, management remains cautiously optimistic on 4Q26. Phase 4 will add around 1,350 suites with no additional gaming tables. At StarWorld, the renovation-related EBITDA drag is expected to be at a similar level in 4Q26. Maintain BUY; cut target price by 9% to HK$43.00.
Company Update | WuXi AppTec (2359 HK/BUY/HK$193.60/Target: HK$220.00)
During its Investor Day, WuXi AppTec highlighted how it is leveraging its operational excellence to capture the tremendous market opportunities arising from the AIDD and AI4S trends. Its end-to-end CRDMO platform precisely bridges the gap from AI design to physical implementation. The company has started to address AIDD/AI4S demand, and expects to further expand service capacity and enhance operational excellence to meet the strong market demand. Maintain BUY with a target price of HK$220.00.
Top Stories
Sector Update | China Internet
We see that the AI industry is transitioning from a capacity-driven investment cycle towards an intelligence monetisation cycle, where model differentiation, inference efficiency, enterprise adoption and sustainable gross profit generation will increasingly determine value capture. We remain constructive on China's AI value chain, with a preference for Alibaba and Z.ai, while viewing Tencent as a longer-term beneficiary of AI application monetisation. Maintain MARKET WEIGHT.
Company Results | FIT Hon Teng (6088 HK/BUY/HK$2.91/Target: HK$4.20)
FIT’s 3Q26 revenue grew 4.0% yoy but operating profit declined 38.8% yoy, impacted by higher material costs and slower-than-expected facility ramp-up. 9M26 revenue and net profit represented 69% and 32% of our full-year estimates respectively. Management cut 2026 operating profit guidance from 70% yoy growth to flattish growth and targets 2027 operating profit to grow faster than its revenue. Maintain BUY but lower target price from HK$9.19 to HK$4.20, based on 15.0x 2027F PE.
Company Results | Galaxy Entertainment Group (27 HK/BUY/HK$34.84/Target: HK$43.00)
Galaxy’s 3Q26 GGR market share increased 1.7ppt qoq to 22.0%, but normalised EBITDA declined 9% qoq on a deterioration in margin. Galaxy’s market share during the Golden Week was largely flat yoy, affected by unfavourable luck. Looking ahead, management remains cautiously optimistic on 4Q26. Phase 4 will add around 1,350 suites with no additional gaming tables. At StarWorld, the renovation-related EBITDA drag is expected to be at a similar level in 4Q26. Maintain BUY; cut target price by 9% to HK$43.00.
Company Update | WuXi AppTec (2359 HK/BUY/HK$193.60/Target: HK$220.00)
During its Investor Day, WuXi AppTec highlighted how it is leveraging its operational excellence to capture the tremendous market opportunities arising from the AIDD and AI4S trends. Its end-to-end CRDMO platform precisely bridges the gap from AI design to physical implementation. The company has started to address AIDD/AI4S demand, and expects to further expand service capacity and enhance operational excellence to meet the strong market demand. Maintain BUY with a target price of HK$220.00.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


