

Analyst
Analyst
Mixed August Data
- Industrial production growth accelerated to 5.2% yoy (+0.7ppt mom) in August, above Bloomberg's consensus estimate of 4.8% yoy. FAI ytd growth fell further to -7.2% yoy (-0.5ppt mom), marginally below consensus of -7.1% yoy, dragged by property FAI ytd (-19.9% yoy, -0.7ppt mom).
- Retail sales growth slowed to 0.4% yoy, below consensus of 0.8% yoy and July's 0.6% yoy. The surveyed unemployment rate edged up to 5.3% (+0.1ppt mom).
- August's data was mixed and slightly market negative, with a narrowly sourced production beat set against further weakness in both consumption and investment; the policy outlooks are set to stay focused on accelerating project implementation.
What’s New
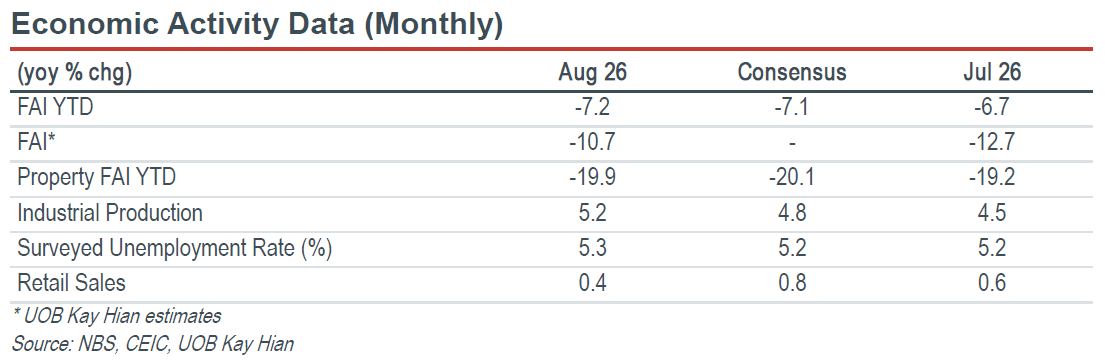
- Industrial production growth accelerated to 5.2% yoy in August (+0.7ppt mom), above Bloomberg's consensus estimate of 4.8% yoy. In August, 29 of 41 major industries maintained yoy growth in output value (vs 25 in July). High-tech manufacturing continued to stand out in terms of its growth (16.7% yoy, -0.2ppt mom), led by industrial robots (34.6% yoy), NEVs (21.9% yoy) and integrated circuits (20.6% yoy), whereas microcomputer equipment posted the steepest decline (-25.6% yoy). External demand remained a key driver of industrial production, with export delivery value rising 11.1% yoy.
- August's retail sales growth slowed to 0.4% yoy, down from July's 0.6% yoy and below Bloomberg's consensus estimate of 0.8% yoy, extending the weak run seen since April. By consumption type, catering revenue grew 1.1% yoy (-0.3ppt mom) while retail sales of goods rose just 0.3% yoy (-0.2ppt mom). Automobile sales continued to decline at -18.5% yoy (-1.5ppt mom), followed by gold, silver and jewellery (-17.5% yoy) and construction and decoration materials (-11.8% yoy, +2.4ppt mom). The main positives were communication equipment (27.3% yoy, +6.9ppt mom) and tobacco and alcohol (12.5% yoy, +6.5ppt mom).
- FAI ytd growth fell further to -7.2% yoy in August (-0.5ppt mom), marginally below Bloomberg's consensus estimate of -7.1% yoy. Property FAI ytd deepened to -19.9% yoy (-0.7ppt mom), though slightly better than consensus estimate of -20.1% yoy. The weakness remained broader than property: infrastructure and manufacturing FAI ytd have contracted 4.0% yoy and 2.3% yoy respectively, deteriorating by 0.4ppt and 0.6ppt from July. On a positive note, our estimated single-month FAI contraction narrowed to -10.7% yoy in August, improving from -12.7% yoy in July. With the recent push to accelerate FAI project implementation, we are likely to see a further easing in the contraction.
Mixed August Data
- Industrial production growth accelerated to 5.2% yoy (+0.7ppt mom) in August, above Bloomberg's consensus estimate of 4.8% yoy. FAI ytd growth fell further to -7.2% yoy (-0.5ppt mom), marginally below consensus of -7.1% yoy, dragged by property FAI ytd (-19.9% yoy, -0.7ppt mom).
- Retail sales growth slowed to 0.4% yoy, below consensus of 0.8% yoy and July's 0.6% yoy. The surveyed unemployment rate edged up to 5.3% (+0.1ppt mom).
- August's data was mixed and slightly market negative, with a narrowly sourced production beat set against further weakness in both consumption and investment; the policy outlooks are set to stay focused on accelerating project implementation.
What’s New
- Industrial production growth accelerated to 5.2% yoy in August (+0.7ppt mom), above Bloomberg's consensus estimate of 4.8% yoy. In August, 29 of 41 major industries maintained yoy growth in output value (vs 25 in July). High-tech manufacturing continued to stand out in terms of its growth (16.7% yoy, -0.2ppt mom), led by industrial robots (34.6% yoy), NEVs (21.9% yoy) and integrated circuits (20.6% yoy), whereas microcomputer equipment posted the steepest decline (-25.6% yoy). External demand remained a key driver of industrial production, with export delivery value rising 11.1% yoy.
- August's retail sales growth slowed to 0.4% yoy, down from July's 0.6% yoy and below Bloomberg's consensus estimate of 0.8% yoy, extending the weak run seen since April. By consumption type, catering revenue grew 1.1% yoy (-0.3ppt mom) while retail sales of goods rose just 0.3% yoy (-0.2ppt mom). Automobile sales continued to decline at -18.5% yoy (-1.5ppt mom), followed by gold, silver and jewellery (-17.5% yoy) and construction and decoration materials (-11.8% yoy, +2.4ppt mom). The main positives were communication equipment (27.3% yoy, +6.9ppt mom) and tobacco and alcohol (12.5% yoy, +6.5ppt mom).
- FAI ytd growth fell further to -7.2% yoy in August (-0.5ppt mom), marginally below Bloomberg's consensus estimate of -7.1% yoy. Property FAI ytd deepened to -19.9% yoy (-0.7ppt mom), though slightly better than consensus estimate of -20.1% yoy. The weakness remained broader than property: infrastructure and manufacturing FAI ytd have contracted 4.0% yoy and 2.3% yoy respectively, deteriorating by 0.4ppt and 0.6ppt from July. On a positive note, our estimated single-month FAI contraction narrowed to -10.7% yoy in August, improving from -12.7% yoy in July. With the recent push to accelerate FAI project implementation, we are likely to see a further easing in the contraction.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


