

Company Coverage
TMBThanachart Bank (TTB TB): 3Q26 Results Preview: Improving Loan Growth And Lower Credit Costs Support Stable Earnings
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt3.08
Bt3.20
3.90%
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
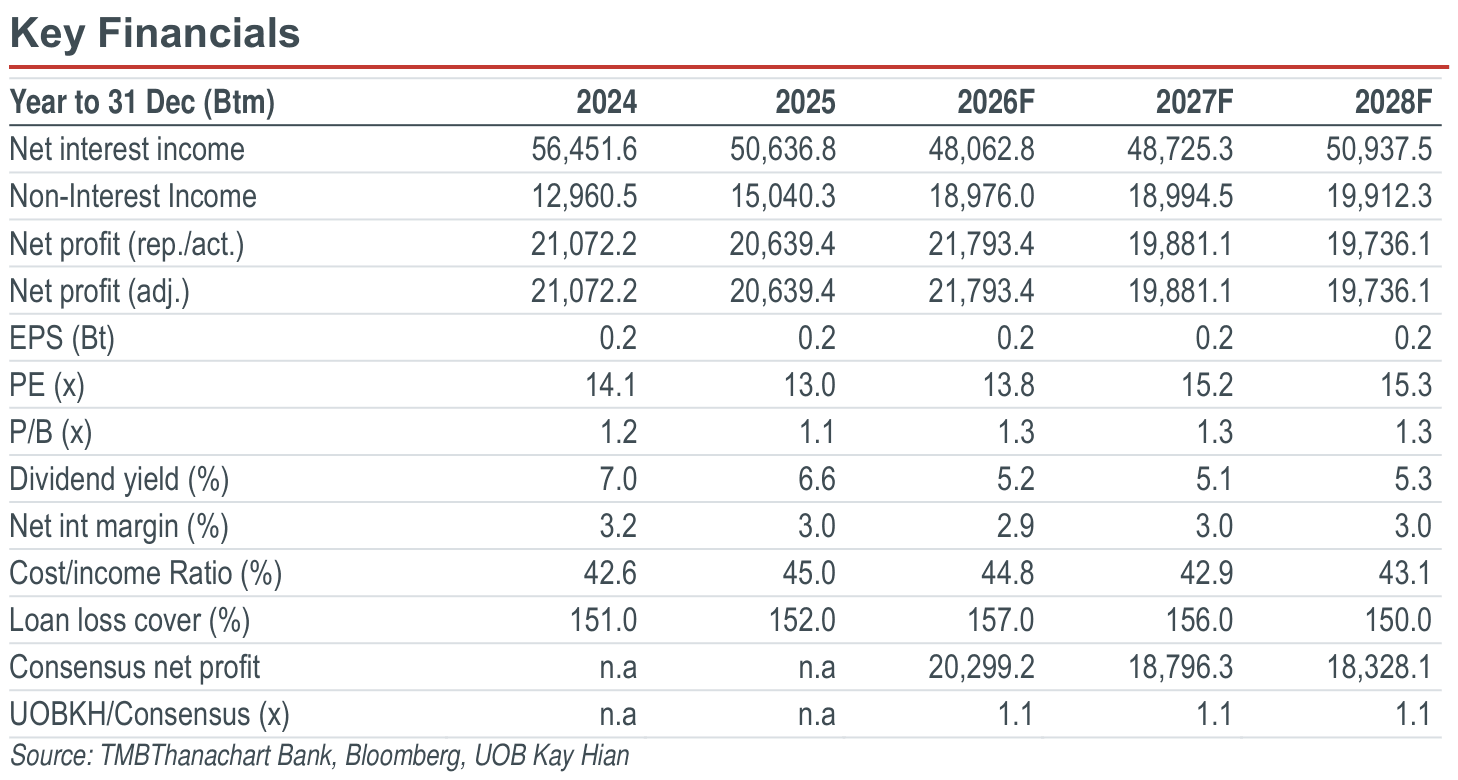
- We expect TTB to report a 3Q26 net profit of Bt5.45b, up 2.8% yoy but slightly down 1.2% qoq.
- Loan growth should improve, while credit costs are projected to ease qoq.
- Maintain HOLD with an unchanged target price of Bt3.20.
Analysis
- Earnings up yoy but down slightly qoq. We expect TMBThanachart Bank (TTB) to report a 3Q26 net profit of Bt5.45b, up 2.8% yoy but down slightly by 1.2% qoq. Excluding provisions, pre-provision operating profit (PPOP) is likely to increase 4.4% yoy and 0.1% qoq.
- Loan portfolios could expand qoq. TTB’s loan portfolio should grow 1.1% qoq, while slightly declining 0.1% yoy. The qoq growth should be driven by consumer loans, supported by risk-based pricing loans and growth in high-yield retail loans, while the yoy decline should continue due to ongoing loan repayments. Auto loans are expected to remain challenging.
- Non-II to normalise from 3Q26 onwards. We expect non-interest income (non-II) to decline 9.7% qoq but increase 17.8% yoy. 2Q26 non-II grew 11% qoq, mainly driven by customers shifting from wealth deposits to wealth products and portfolio rebalancing. This impact should normalise, as guided by management, given cooling market sentiment compared with 1H26 and continued competition among banks in wealth management.
- NIM to improve qoq. TTB’s continued focus on high-yield and risk-based pricing loans should support loan yields and NIM. Meanwhile, the ongoing reduction in time-deposit deposits through the shift towards hybrid products, together with deposit repricing, should further support funding costs. As a result, we expect NIM to improve qoq to 2.95% in 3Q26 from 2.88% in 2Q26.
- Credit costs expected to decline qoq. We forecast 3Q26 provisions at Bt3.86b, down 3.1% yoy and 4.5% qoq, following elevated provisioning in 1H26. TTB’s Bt1.1b management overlay in 2Q26, mainly related to higher probability of default assumptions and secured customers, should provide some cushion for credit costs. As provisions were already front-loaded in 1H26, we see potential for partial overlay releases going forward. Overall, 3Q26 credit cost is expected to decline to 129bp from 136bp in 2Q26.
Highlights
- We expect TTB to report a 3Q26 net profit of Bt5.45b, up 2.8% yoy but slightly down 1.2% qoq.
- Loan growth should improve, while credit costs are projected to ease qoq.
- Maintain HOLD with an unchanged target price of Bt3.20.
Analysis
- Earnings up yoy but down slightly qoq. We expect TMBThanachart Bank (TTB) to report a 3Q26 net profit of Bt5.45b, up 2.8% yoy but down slightly by 1.2% qoq. Excluding provisions, pre-provision operating profit (PPOP) is likely to increase 4.4% yoy and 0.1% qoq.
- Loan portfolios could expand qoq. TTB’s loan portfolio should grow 1.1% qoq, while slightly declining 0.1% yoy. The qoq growth should be driven by consumer loans, supported by risk-based pricing loans and growth in high-yield retail loans, while the yoy decline should continue due to ongoing loan repayments. Auto loans are expected to remain challenging.
- Non-II to normalise from 3Q26 onwards. We expect non-interest income (non-II) to decline 9.7% qoq but increase 17.8% yoy. 2Q26 non-II grew 11% qoq, mainly driven by customers shifting from wealth deposits to wealth products and portfolio rebalancing. This impact should normalise, as guided by management, given cooling market sentiment compared with 1H26 and continued competition among banks in wealth management.
- NIM to improve qoq. TTB’s continued focus on high-yield and risk-based pricing loans should support loan yields and NIM. Meanwhile, the ongoing reduction in time-deposit deposits through the shift towards hybrid products, together with deposit repricing, should further support funding costs. As a result, we expect NIM to improve qoq to 2.95% in 3Q26 from 2.88% in 2Q26.
- Credit costs expected to decline qoq. We forecast 3Q26 provisions at Bt3.86b, down 3.1% yoy and 4.5% qoq, following elevated provisioning in 1H26. TTB’s Bt1.1b management overlay in 2Q26, mainly related to higher probability of default assumptions and secured customers, should provide some cushion for credit costs. As provisions were already front-loaded in 1H26, we see potential for partial overlay releases going forward. Overall, 3Q26 credit cost is expected to decline to 129bp from 136bp in 2Q26.
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt3.08
Bt3.20
3.90%
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
