

Company Coverage
Alibaba Health Information Technology (241 HK): 1HFY27 Preview: Lowers FY27 Revenue Growth Target To 7-10% yoy On Subsidy Optimisation; Earnings Guidance Unchanged
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$3.06
HK$4.00
+30.4%
HK$5.20
Analyst
Analyst
Highlights
- Ali Health lowered its FY27 revenue growth target from 10-15% to 7-10% yoy, while keeping its adjusted net profit guidance unchanged at Rmb1.9b-2.3b. This reflects proactive optimisation of product-price subsidies, with savings redeployed into B2C+O2O supply-chain integration.
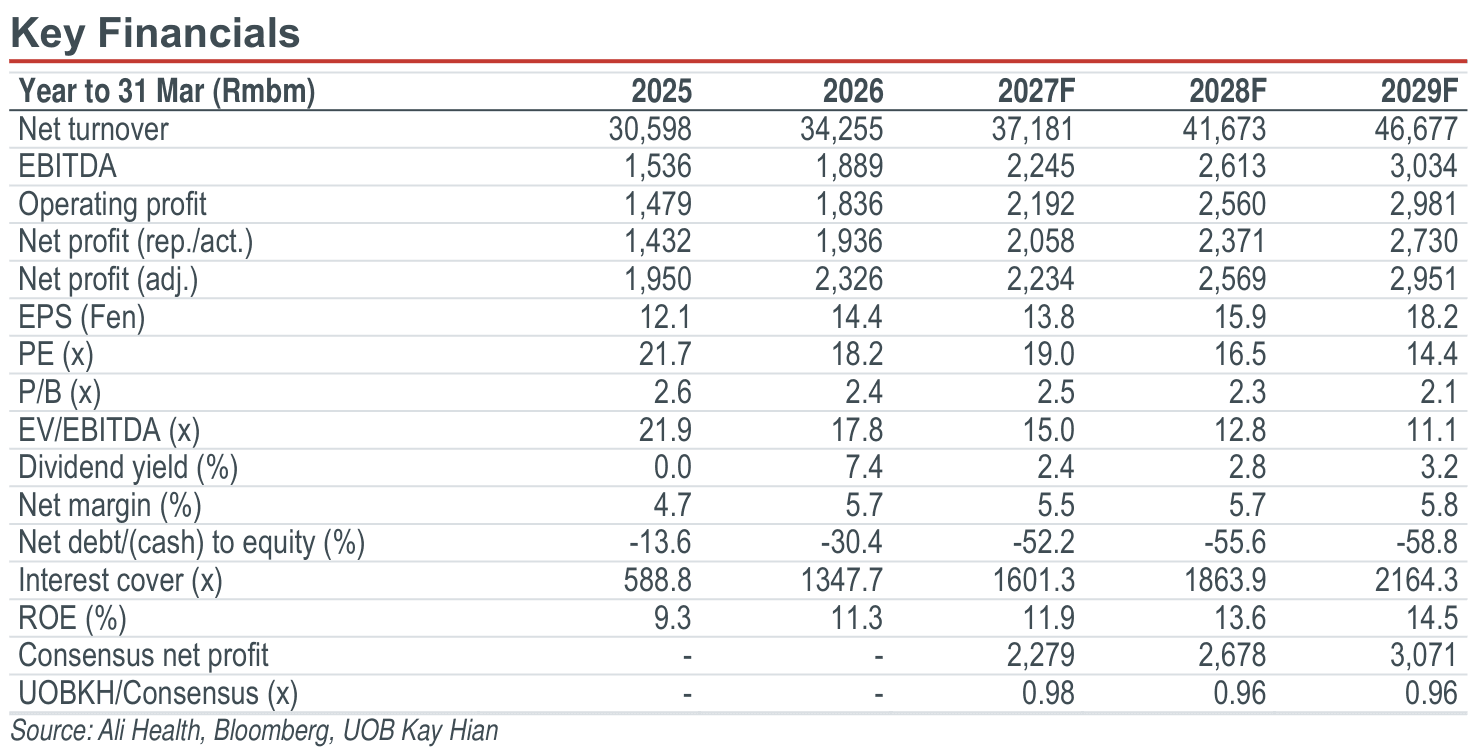
- We lower our FY27 revenue growth estimate from 12.4% to 8.5% yoy, while maintaining FY27-29 revenue and adjusted net profit CAGRs of 12% and 15% on innovative drugs momentum, deepened Alibaba synergies, and expanding AI adoption. Maintain BUY with a lower target price of HK$4.00.
Analysis
- Lowered FY27 revenue guidance to 7-10% yoy while keeping profit guidance intact. At its 1HFY27 results preview call on 18 September, Alibaba Health Information Technology (Ali Health) cut its FY27 revenue growth target from 10-15% to 7-10% yoy and reiterated its adjusted net profit forecast of Rmb1.9b-2.3b. The revision is a deliberate strategic choice. The company is actively reducing product-price subsidies. Transaction volume will be impacted, while the growth driver has already shifted from subsidy-driven to demand-driven. This is supported by a more mature online-pharmacy user mindset, expanding innovative-drug supply eg GLP-1 and cardiovascular products, and improving B2C+O2O fulfilment experience. Management expects the impact to be relatively even across 1HFY27 and 2HFY27.
- Subsidy savings to be redeployed into B2C and O2O supply-chain integration. Profit saved from lower subsidies will be redeployed into longer-term supply-chain capabilities and accelerated B2C+O2O integration, with flash-sale medicine transaction links already connected to the main search channel. Management emphasised that the priority is fulfilment speed, assortment breadth, and service consistency rather than price, viewing these investments as building structural user-experience and stickiness advantages. The gross-margin impact of lower platform subsidies should be limited, as most subsidies sit below gross profit. Self-operated original-drug subsidies will be reduced more modestly.
- Drugs remain the growth engine while non-drug categories turn softer. Ali Health’s growth is shifting from subsidy-led to demand-led, as online drug purchasing habits are entrenched, proactive search traffic rises, and repurchase behaviour becomes less price-sensitive. Drugs, especially innovative/original drugs, remains the primary growth engine and is guided for a high double-digit growth in FY27. Subsidies will remain concentrated on drugs. Non-drug categories are expected to deliver a low single-digit growth, as the company will no longer use heavy price subsidies to chase volume.
Highlights
- Ali Health lowered its FY27 revenue growth target from 10-15% to 7-10% yoy, while keeping its adjusted net profit guidance unchanged at Rmb1.9b-2.3b. This reflects proactive optimisation of product-price subsidies, with savings redeployed into B2C+O2O supply-chain integration.
- We lower our FY27 revenue growth estimate from 12.4% to 8.5% yoy, while maintaining FY27-29 revenue and adjusted net profit CAGRs of 12% and 15% on innovative drugs momentum, deepened Alibaba synergies, and expanding AI adoption. Maintain BUY with a lower target price of HK$4.00.
Analysis
- Lowered FY27 revenue guidance to 7-10% yoy while keeping profit guidance intact. At its 1HFY27 results preview call on 18 September, Alibaba Health Information Technology (Ali Health) cut its FY27 revenue growth target from 10-15% to 7-10% yoy and reiterated its adjusted net profit forecast of Rmb1.9b-2.3b. The revision is a deliberate strategic choice. The company is actively reducing product-price subsidies. Transaction volume will be impacted, while the growth driver has already shifted from subsidy-driven to demand-driven. This is supported by a more mature online-pharmacy user mindset, expanding innovative-drug supply eg GLP-1 and cardiovascular products, and improving B2C+O2O fulfilment experience. Management expects the impact to be relatively even across 1HFY27 and 2HFY27.
- Subsidy savings to be redeployed into B2C and O2O supply-chain integration. Profit saved from lower subsidies will be redeployed into longer-term supply-chain capabilities and accelerated B2C+O2O integration, with flash-sale medicine transaction links already connected to the main search channel. Management emphasised that the priority is fulfilment speed, assortment breadth, and service consistency rather than price, viewing these investments as building structural user-experience and stickiness advantages. The gross-margin impact of lower platform subsidies should be limited, as most subsidies sit below gross profit. Self-operated original-drug subsidies will be reduced more modestly.
- Drugs remain the growth engine while non-drug categories turn softer. Ali Health’s growth is shifting from subsidy-led to demand-led, as online drug purchasing habits are entrenched, proactive search traffic rises, and repurchase behaviour becomes less price-sensitive. Drugs, especially innovative/original drugs, remains the primary growth engine and is guided for a high double-digit growth in FY27. Subsidies will remain concentrated on drugs. Non-drug categories are expected to deliver a low single-digit growth, as the company will no longer use heavy price subsidies to chase volume.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$3.06
HK$4.00
+30.4%
HK$5.20
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

1 Sept 2026
Medlive Technology Co (2192 HK): 1H26: Softer Top-line Growth On Compliance Reset; Core Earnings Remain Resilient

27 Aug 2026
Hansoh Pharmaceutical Group Company (3692 HK): 1H26: Results Beat; Expects To Launch Five New Products In 2027

1 Sept 2026
Ganfeng Lithium (1772 HK): 2Q26: Results Beat, But Price Guidance Cut Clouds Outlook
Our latest research
18 Sept 2026
TA: Innovent Biologics (1801 HK) / Hansoh Pharmaceutical (3692 HK)
17 Sept 2026
TA: Semiconductor Manufacturing (0981 HK) / China Gold (2099 HK)

17 Sept 2026